Berger’s stellar performance

Berger price jumped on Friday after posting strong 2016 results.

Berger Paints released results to December, showing profit of $251 million and $1.17 per share for the nine months period, versus $110 million for 2015. Revenues climbed 17.8 percent in the December quarter, to $1.9 billion or 14.4 percent from $1.67 billion in 2015.
For the quarter, earnings were $185 million versus $80 million in the 2015 quarter, with revenues climbing 17.8 percent in the December quarter to $895 million.
Berger ended with cash of $158 million in December, having generated $370 million from operations before build up in working capital. The gross cash inflows, places it in a good position to continue to pay out a rich dividend, which they should do later in the year. According to the cash flow statement, receivables jumped by $378 million over the March 2016 position. That would put it at $700 million, as of December 2016. The majority of this amount should be cleared by the end of March.
Unfortunately, the Berger report does not conform to international standards for reporting interim results. The effect is there is no information on direct and indirect cost and gross profit and the balance sheet carries little information as to the composition of the current assets and liabilities. Accordingly, investors, cannot make proper assessment of its performance.
A final dividend of 20 cents per share totalling $42.864 million was paid July 2016. The stock responded well to the numbers, with investors pushing it to a new record high of $6.75 in early morning trading on Friday, on the Jamaica Stock Exchange. IC Insider.com forecast earnings of $1.10 for the full year to March 2017 and $1.60 for the 2018 fiscal year.
Main Event priced to bounce

The Main Event Entertainment Group Initial Public offer of shares seem set to deliver a strong increase in share price once the stock list on the junior market probably in February. There are a number of positives to greet the issue.
The stock market is in a bull run currently. The stock is priced at just $2 which many small investors will be attracted to. The historical PE is just 7, compared to an average of 15 for junior market stocks, based on 2016 earnings. IC Insider.com is projecting earnings in the order of $100 million for 2017, assuming a 15 percent revenue gain, for earnings per share of 33 cents. Based on this, the stock should more than double in 2017.
The company grew revenues by 11 percent in 2016 over 2015 to an estimated $1.13 billion and by 55 percent over 2014 while that for 2013 was flat at $517 million. The company indicates that they had to recently turn away business due to capacity constraints which the fresh capital will fix.
Gross profit has been strong at 36 to 38 percent level in 2016, but it may be somewhat lower, as some items in administrative and general expenses may be directly related to events, rather than overheads.
Main Event,should benefit from the strong growth in the tourism sector and pickup in economic activity locally, that should see a greater number of Jamaicans patronising entertainment events, allowing for more events to be staged.
Importantly, the profile of the company will grow with the listing, as they benefit from daily exposure based on trading activity. The expanded directorship and regular examination of operations by the board and the infusion of capital will result in even better performance going forward and that should boost revenues and hold cost in check. This is a factor that should not be lost on investors.
Only 60 million shares are being sold, with few being available to the general public. The issue opens at 9 am, Tuesday 24 January and is likely to close at the same time. On the negative side, the company suffered a large fall in digital signage income with $75 million inflows in the 11 months to September 2016 from $139 million in the similar period in 2015. Receivables tend to be on the high side of nearly 2 months of sales, tying up nearly $100 million in excess of normal levels, while payables are running at 2.3 months at $181 million.
IC Insider.com is according an investment in the stock to be BUY RATED.

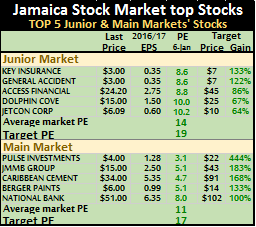
Jetcon Flavours in TOP 5

There were few changes in the TOP 5 listing this past week, but Jetcon fell out of the list having climbed to $7 at the close of the week, to help flavour in Caribbean Flavours into the top list.
Price movements saw Access Financial edging towards the exit with the bid now at $26.50 and buying pushing the price up during the week as a connected party bought stock at $25.50. The stock last traded at $25.20 and closed without any stock being offer for sale.
The stocks of the main market listing, remained without change but Cement saw its price moved up to close out the week at $36 as well as did JMMB Group with heavily trading during the week.

Paramount exits TOP 5 overvalued stocks

Paramount

Paramount Trading is out of the TOP 5 junior stocks to avoid, even as it just reported reduced profits for both the first and second quarters of 2017 fiscal year. Second quarter earnings slipped from $47 million to $37 million and for the year to date, it fell from $89 million to $52 million.
Iron Rock Insurance entered the junior list as operating results fall behind forecast.
There seems to be little rationale for Cargo Handlers to be selling at a PE of 35 based on estimated 2017 earnings and worse 51 times 2016 earnings. The stock is selling well in excess of the average market and the next highest valued in the junior market, Honey Bun that is at a PE of 21, based on 2016 earnings but a more moderate 14 times projected 2017 earnings.
It not surprising that Cargo Handlers heads the list of most overvalued stocks on both the main and junior market, followed by Kingston Wharves and 138 Student Living.
Iron Rock projected losses in the prospectus for 2016 of $30 million and a small profit of $3 million which includes foreign exchange gains of $7 million in 2018. Year to date losses to September last year, are running well ahead of the prospectus’ forecast with losses of $38 million with the September quarter’s losses ended at $14 million. More worrying is that projections of gross premium income of $169.36 million in 2016 rising to $414.97 in 2017 are well off what seems to be occurring in 2016 with results for the nine months showing gross premium of just $59 million well below forecast by $110 million. With all of this happening investors pushed the stock up to $4 for a premium above the listed price.

Jetcon & CWJ set for 2017 top spots

C&W set to be 2017 top stock from the main market.

By the end of 2017, the two top stocks on the Jamaica Stock Exchange is forecasted by IC Insider to be the 2016 listed Jetcon Corporation and previously battered Cable and Wireless that should be reporting good profits for the year.
In the just concluded week, Caribbean Cream (Kremi) and Lasco Financial that entered the IC Insider’s TOP 5 at the end of December, only spent one week in the list. Both stocks climbed during the past week with Lasco Financial moving up 18 percent to $3.67 and Caribbean Cream gained 14 percent to $8.55. Key Insurance rose 14 percent during the week and General Accident was up 7 percent.
Entering the TOP 5 for the first time, is Dolphin Cove, and returning is Jetcon Corporation at 4th and 5th spot, respectively. Investors have lost confidence in Dolphin Cove even as the company continues to produce decent results and having good prospects, with the major expansion in the tourism industry. Profit to September last year, was up 11 percent to $1.17 per share, exceeding the results for the entire 2015.
Jetcon reported in their September quarterly

Dolphin Cove moved into the IC Insider’s TOP 5 junior market stocks.

report that they “had another quarter of strong results with revenues climbing 86 percent over the September 2015 quarter, to $267 million and climbed 61 percent to $610 million for the nine months. Profit grew 275 percent to $35 million from $9 million in the September quarter, compared with the similar period in 2015 and is up 141 percent for the nine months period over the same period in 2015.” Profit for the nine months ended at $67 million and had exceeded the $40 million after tax, earned for the full year of 2015. In mid-September the company also reported that “subsequent to the Quarter, revenues continue be ahead of the same period for 2015 by approximately 70 percent,” suggesting that the final quarter should continue to reflect the robust performance seen in the earlier months. Jetcon is poised to be IC Insider’s top junior market stock for 2017, followed by ISP Finance, based on IC Insider’s forecast.
There were not much movement in the main market stocks during the week. Radio Jamaica moved out of the TOP 5, having gained in price during the week and is replaced by National Commercial Bank, at the number 5 position. The banking group is still selling cheaper than Scotia Group with earnings for the 2017 year to be released by the end of January. IC Insider is forecasting $8 per share earnings for 2017 with increased dividend payments around $3 per share, suggesting the stock has much room for growth. The number 1 main market stock is projected to be Cable & Wireless followed by Barita Investments. Last year this publication stated that Barita was the best main market stock back in September, it is now up by 93 percent since but has much more gains ahead with projected earnings of $1.75 for 2017.
Note: One of our writers is a director of two junior companies, Jetcon Corporation and Jamaican Teas. Connected parties to IC Insider.com may hold shares in companies commented on from time to time.

Kremi & Lasco Financial in TOP 5

Investors’ activity in the junior market resulted in changes to the IC Insider’s TOP 5 list from that for December 9. AMG Packaging with gains of 38 percent and Blue Power with gains of 46 percent dropped off the list.
Caribbean Cream and Lasco Financial entered the top listing with potential gains based on fiscal year 2015/16 of 81 and 71 percent respectively.
Derrimon Trading fell back during the period to $3.55 to re-enter the list but has since shot up to $5.50 to be sitting well below the TOP 5 with gains of 77 percent since it entered the top 5 initially. Announcement that the company deposited money to acquire a large block of the shares in Caribbean Flavours spurred the move in the stock price.
In the IC Insider’s TOP 5, the candidates remain unchanged for the main market, with investors’ interest being focussed on other stocks in the main market.
The list comprises potential gains based on current estimated earnings which are likely to drive stock prices before the 2017 earnings start to have a full effect.
The 2017 list based on IC Insider’s earnings forecast is likely to vary quite a bit from those on the current list.

Flavours out Blue Power in TOP 5

Investors pushed the price of Caribbean Flavours to $9.99 during the past week and out of the IC Insider’s TOP 5 of junior market stocks list, allowing Blue Power to return at the bottom of the list. AMG Packaging price fell back and the stock moved up on the list to number 2 spot.
Top 5 stks 9-12-16In the IC Insider’s TOP 5, the candidates remain unchanged but Caribbean Cement benefited from an announcement that the Cemex Group who are offering to but majority stake in Trinidad, if successful may consider delisting shares in Barbados and Jamaica including subsidiaries after a full review of the Caribbean operations. Carib Cement moved to 4th position and is worth watching in the week to come. There are 6 offers in the market at the close of trading on Friday, ranging from $36.48 to sell 10,000 units, 10,000 units at $37, the next is 2,300 shares at $44 with the next being at $45 and $60. Bids for the stocks are not very aggressive with the only meaningful one being at $34.01 to buy 69,000 shares.
Scotia hikes dividend on profit rise

Jackie Sharp - CEO Scotia Group

Jackie Sharp – CEO Scotia Group

Scotia Group raises dividend with the Board of Directors approving a final dividend of 45 cents per stock unit in respect of this financial year, which is payable on January 18, 2017 to stockholders on record as at December 27, 2016.
The proposed payment brings the total payment for the year to $1.71 and represents a 6 percent increase in dividends year over year and a dividend payout ratio of 47.08 percent of profit. The final payment means that the 2017 payout should be no less than $1.80, with the proposed payment setting the stage for future quarterly payments. Scotia Group released results with earnings per share ending at $3.63 compared to $3.19 for 2015.
At the same time Scotia Investments held dividends at 45 cents per share the same amount they have been paying in recent times although the company report net profit of $1.35 billion for the year ended October compared with $1.02 billion for the prior. The 2016 profits rose by 32 percent or $325 million net income of $537 million for the quarter ended October, up from $288 million the quarter ending October 2015.
Strong gains of $527 million in fee income, foreign exchange trading gains and gains on financial assets were the main contributing areas that gave rise to the increased profit for the year, for Scotia Investments with earnings per share of $3.19.

Barita up 61% & exits top 5 Pulse in

Barita is one of the top IC Insider's stock for growth over the next 12 months in the main market.

Barita is one of the top IC Insider’s stock for growth over the next 12 months in the main market.

Barita Investments looks like the stock to deliver the best returns in the main market of the Jamaica Stock Exchange, was the lead to IC Insider’s start to the TOP 5 series in September. The stock priced then at $3.15, is now out of the TOP 5 main market list with a 61 percent gain, when it closed the week at $5.
Barita has been replaced by Pulse Investments. The latter just released the September quarterly report with the best quality of earnings in years, with an improving cash flow compare with prior periods and increased earnings of 32 cents per share. Excluding fair value gains on real estate holdings, earnings per share would be around 23 cents or 90 cents per share annualised. The stock price has room for growth in the coming months.
Kingsley Cooper Chairman of Pulse

Kingsley Cooper Chairman of Pulse

The recommendation to buy Barita was a bold one, coming against the background of a stock that had not performed well in recent times before September as well as that a large brokerage house in August, recommended investors to sell the stock based on a number of factors. Specifically they said, “Initiatives implemented during the last financial year have thus far been successful in supporting both net interest income growth as well as fee income. The recent rally in Emerging Market bond prices should help Barita to recover from the decline experienced in the period. That said, we expect just a marginal increase in year on year net profit. Given this expectation we estimate BIL shares to be valued at approximately $2.35 by applying the market average P/E to estimated EPS. Therefore at a current market price of $3.10, we are recommending a SELL on BIL”. Interestingly, IC Insider assessment indicates that based on the extremely good quality of the company’s fourth quarter earnings, profits should be hitting a range of $1.50 to $2 per share for the current fiscal year and investors should be seeing a huge uptick in the price.
Top 5 stks 25-11-16Barita reported earnings excluding one off write down of investments of $171 million or 38 cents per share in the September quarter up 140 percent over the $70 million earned in the similar period in 2015.
Barita Investments is undergoing change and this has driven up fee income sharply which is replacing interest income formerly generated form the repo business. Net interest income climbed sharply in 2016 as new business jumping to $127 million from just $44 million in the September 2015 quarter. Barita has also built up a large pool of unrealized gain on investments which can be released to profit in the future.
The other selections in the top 5 have not changed much during the week, except for a rise in the price of Key Insurance to $2.45. The junior market listings are being generally held back due to a lack of supply of shares being offered for sale.

Key Insurance in at top of TOP 5

Key Insurance listing ceremony.

Key Insurance listing ceremony.

Key Insurance climbed into the Top 5 of the IC Insider’ junior market list, at the number one spot. The rise came about as a result of a turnaround in the company’s September quarterly results, to overcome a drag the losses reported in the June had on the profit and the stock price.
IC Insider’s forecast is for earnings per share of approximately 35 cents for 2016, for Key, suggesting the potential for a big rise in the stock price. It is noted that the only offer for the stock is 34,688 at $3.50 with the highest bid at $2.15 to buy 40,700 shares.
Jetcon Corporation has fallen out of the Top five due to a combination of a rise in Jetcon’s price, following strong third quarter results and the ascension of Key Insurance to the list. Access Financial that has been in the TOP 5 for a long time also reported strong increased profit, with a hike of 95 percent for the September quarter and a 60 percent rise to $353 million for the six months to September.
Barita could be the star performer from the TOP 5 main market stocks as demand has come in for the stock, while supply has declined.IC Top 5 18-11-16 While the investment bank reported 54 cents per share for the full year to September, earnings from ongoing operations is more like 65 cents per share. Most importantly, the information that says the stock is an outstanding buy candidate, is the quality of the final quarter results, with strong growth in fee income and net interest income and less reliance on investment and foreign exchange gains. The final quarter results, suggest earnings should end up around $1.50 in 2017. JMMB Group came in with big increased earnings, one off gains may have played a big role in the big increase but even without that, the stock is undervalued with earnings from ongoing operations in the $2 range.