NCB to go for 62% of Guardian

NCB Financial Group is to go after 62% of Guardian Holdings.

NCB Financial is to make a revised offer to acquire 62 percent of the Trinidad based Guardian Holdings (GHL), at a revised price of US$2.79, the group said today, in a release.
This is in line with the original offer made in 2017 but at higher price and above the 51.85 percent at US$2.65 they agreed to, after being investigated by the Trinidad Exchange Commission. The revised offer which will be published soon, with the exact timing is yet to be determined. The acquisition is to be partially funded by US$45 million to be provided by way of vendors’ loan from selected shareholders.
The acquisition is set to make a major impact on the NCB Group and ultimately the stock price. For one GHL is being bought for just less than 10 times earnings while NCB is selling at 15 times 2018 earnings as such the impact on the price of NCB shares will be seen in 2019 as GHL profit will be
Guardian Holding

valued more to NCB shareholders. Most importantly, majority ownership will permit it to reshape the group by merging the separate insurance companies and securities operations into one and allow it to rationalize various back office operations within the group into one unit and thus cut considerable cost out of the enlarge group.
NCB already owns 29.99 percent of Guardian. The GHL shares last traded in Trinidad at TT$16.95 or approximately US$2.53. NCB closed trading on the Jamaica Stock Exchange at $148.
ICreate to open January

The ICreate initial public offer of shares is expected to open on January 4 with the prospectus set to be released either later this week or next week.
Information gleaned by IC Insider.com is that 74 million ordinary shares will be offered for sale to the public at approximately $1 each and is slated to list on the Junior Market of the Jamaica Stock Exchange. Revenue is said to be running at just under $50 million per annum with prospects for strong growth going forward. Already the company is making a small profit IC Insider.com gathers. The business is the training of students in graphic designs and animation.
The majority shares are owned by EMedia Limited with Sagicor Investments holding a minority position in it.

IC Insider.com article stings JSE into action

Marlene Street Forrest – General Manager of the JSE is said to have intervened to reset the price Express Catering could trade at on Tuesday.


The article, The stock exchange needs radical overhauling seems to have stung the exchange into action as all the errors that were left unattended for months, are now corrected.
Delisted stocks that were being carried as if they were still listed are now out of the trading sheet. Eppley 7.5% preference share that was recently listed, is now correctly placed in the preference section. Barita Investments 52 weeks’ high is now at $33.50 instead of $60 that was being carried for weeks. Hopefully, the exchange would have corrected all other erroneous highs and lows that resulted from cancellation of trades in the past. Importantly, the errors in the All Jamaica Composite Index for the early days of November are now correctly stated.
The Stock Exchange is to be commended for moving speedily to correct the errors that were brought to their attention. It would also be good in order to better protect their integrity that compensated investors who were firstly advised of an allocation of 16.56 percent of Seprod shares only to see it adjusted down to 16.26 percent. That would be the correct thing to do in the circumstance that prevail that led to the adjustments that took place. The phrase, the customer is right is still a valid principle to operate by.
When all is said and done just correcting the errors IC Insider.com pointed out is only a first step, the exchange needs to put in place quality control mechanisms to prevent such occurrences. It also appears that the exchange needs a qualified lawyer and accountant on board with sufficient securities experience to help police the systems effectively. If they do it could prevent matters such as prospectuses and financial statements being issued with the types of errors that are showing in the public space.

Barita proposes $15.50 rights issue

The directors of Barita Investments on December 13, passed a resolution for a Rights Issue of 10 shares for each 17 owned at the record date, to take effect in early January which if taken fully will results in 258 million new shares and bring the capital issued to 707 million units.
The board resolution states:- The Board approves the issue of 258,064,516 ordinary shares (in this resolution “New Ordinary Shares”) part of the authorised capital, the same to be offered to the holders of Ordinary Stock Units by way of a Non-Renounceable Rights Issue on the following terms:
(i) Offer Price of J$15.50 per New Ordinary Share. (ii) Offer to Stockholders of the Company as at a Record Date of December 31, 2018. (iii) Offer to Open on January 8, 2019
(iv) Last date for splitting to be January 15, 2019. (v) Offer to Close on January 22, 2019 for acceptance by Existing Ordinary Stockholders/Renouncees
(vi) Offer to Close on January 25, 2019 for acceptance by applicants for Excess Shares (not taken up by Allottees under the Letter of Provisional Allotment).
2. The Directors are hereby authorized to dispose of all such New Ordinary Shares not taken up by Allottees on terms and conditions as the Directors may consider expedient in their absolute discretion, in consultation with the Arranger for the Rights Issue, Sagicor Investments. BIL further advised that the share ratio allocation for the Rights Issue will be as follows: Ten (10) additional shares for every seventeen (17) shares owned by existing stockholders of Ordinary Shares in Barita Investments.
Apart from a rights issue, the above resolution speaks to the last date for splitting being January 15, which raises the question if a stock is to be considered as well.
Barita stocks that trades on the Jamaica Stock exchange at $33.45 on Friday and is up 346 percent for the year to date.

Scotia hikes dividend

David Noel new Scotia Group’s CEO.

Scotia Group delivered below par performance in that final quarter of the 2018 fiscal year, with profit falling to just $1.6 billion from $3.36 billion in 2017.
The quarterly results, however, is not an indication for what can be expected for the 2019 fiscal year as one time fall in revenues and in some cases, expenses are unlikely to be reflected for the full year to come. In keeping with expected pick up in profit the banking group hiked their dividend from the usual 48 cents per share to 51 cents in their latest announcement. Based on Scotia’s long held policy, when dividends are raised it is usually an indication that future dividend payments will continue at the elevated level for the ensuing period. Investors in the stock can therefore look forward to at least $2.04 cents for all of 2019. That will be a return on the latest stock price of $54.01 of 3.8 percent. Dividends paid in 2018 amounted to $1.92 per share. The total amount of dividends to be paid in January will be $1.59 billion which is alomost all the profit reported for teh quarter. The dividend will be paid on January 18, 2019, with the ex-dividend date set for December 24.

Strong food & insurance sales gains at Grace

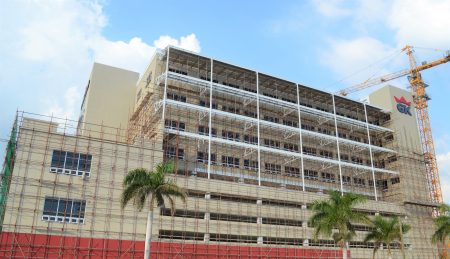
Grace new HQ close to the end of construction in downtown Kingston

Grace Kennedy reported net profit attributable to shareholders of $3.26 billion for the year to September compared with $3.3 billion in 2017 on strong gains in Food and Insurance segments. For the September quarter, the group earnings of $1.06 billion was realized, down from $1.5 billion.
The current quarter’s result is negatively impacted by one off expenses.
Segment results show declines in the Money transfer business with segment results down to $2.34 billion from $2.46 billion in 2017. Banking was flat with results of $401 million but both Insurance and Food trading recorded healthy increases. Food reported $1.35 billion in 2017 and climbed a strong 12.5 percent to $1.52 billion and Insurance jumped a robust 22.7 percent from $508 million to $734 million.
When adjusted for non-recurring gains in 2017 and one-time expenses of $236 million in the September 2018 quarter, profit for the nine months would have been greater by approximately $600 million.
For the nine-months, the Company revenues rose 7 percent to $73.8 billion but climbed a healthier 11 percent to $25.46 billion for the September quarter, over the same period in 2017. Group Chief Financial Officer, Frank James, informed IC Insider.com that the savings from the rationalisation exercise will generate savings considerable higher than the cost, due partially to some former employees being retired and not incurring separation cost.
Operating cost rose faster than revenues, with an increase of 13 percent to $24.6 billion for the

Group Chief Executive Officer, Don Wehby.

quarter and an increase of 8 percent to $71.4 billion for the nine months. Unfortunately, Grace continues the backward practice of not breaking out direct selling cost from other costs in their interim results as such investors cannot determine how movement in cost is affected by changes in revenues versus fixed and administrative cost.
Shareholders’ equity increased of $3.2 billion to $48.4 billion over 2017. Loans receivables remained flat at $26.4 billion compared to $26.58 billion in September 2017 and is down from $27.55 billion at the end of 2017. At the end of the period total assets increased $7.3 billion to $137 billion since September in 2017 and liabilities rose by a smaller $3 billion to $86.44 billion.
In speaking to the recent performance, Group Chief Executive Officer, Don Wehby, affirmed, “The Company is investing strategically for future growth and efficiency to achieve this objective. We are seeing a 12.6 percent increase in profit over prior period, with the one-off adjustments, and we expect continued growth based on our strategy.”
Since 2018, the Group embarked on a programme which aims to improve its return on investment and shareholder value. The process involves a review of its overall organizational design, cost structure, and business processes at all levels resulting in restructuring which affected a number of positions in August. In expounding further Wehby stated, “Although the restructuring costs of $236 million impacted the quarter’s performance, I am confident that the Company will realize the benefits of this in subsequent periods.”
Grace pays an interim dividend of 50 cents per stock unit on December 13, bringing dividends to date to $1.35 per stock unit of more than $1.3 billion.
Wehby and the group’s chairman Gordon Shirley in their report to shareholders stated that Grace Kennedy anticipates continued growth for the fourth quarter, subsequent to the quarterly report the group announced changes in their Florida distribution with an investment in the company that manufactures it patties that will take over Graces distribution and warehousing in that area. The new arrangement will mean less cost and more profits for Grace.
IC Insider.com projects earnings is $4.80 for the current fiscal year to December and $6 for 2019. The stock is listed on the Jamaica Stock Exchange and trades at $60 for a PE of 12.5 times current year’s estimated earnings versus an average for the market in the region of 15, with a premium of a mere 20 percent above net book value per share and seems undervalued, currently. The stock looks like a good long term investment.

I Create another IPO coming soon

iCreate, a fairly new company that is involved in the creative industry is at an advanced stage of planning to raise funds publicly by way of an IPO, ahead of a potential listing on the Junior Market of the Jamaica Stock Exchange.
According to the company’s website, they are a Creative Institute, developed with the aim of filling the gap in skills training and development of creatives in Jamaica and the wider Caribbean. As a part of the creative eco-system, students are provided with a wide range of career opportunities in the Creative Economy, while being a key partner of the Advertising Industry, Film Production Companies, Animation and Gaming Companies, and Creative Outsourcing initiatives.
iCreate partners with the University of the Commonwealth Caribbean (UCC) as its Creative Training arm for courses offered in Jamaica and the Caribbean. iCreate is also partnered with the Digital Marketing Institute, to become the only institution in the Caribbean licensed to deliver their Digital Marketing Diploma programme.
The majority shares are currently owned by eMedia Interactive Group with Sagicor Investment said to hold 19 percent of the shares. The total of just over 123.5 million shares issued are issued currently that will go to 196 million if the IPO is fully taken up. The issue should be coming to the market place soon, by the end of the year or early in 2019. Tyrone Wilson is the Managing Director of the Group.

Also expected to list in 2019 are Wigton Wind Farm which will provide an investment more for income than growth. Also exploring listing are a paint company and a manufacturing company from central Jamaica.

Blue Power profit jumped 55%

Sales at Blue Power for the half year of its 2019 fiscal year to October, increased 13 percent to $862 million from $761 million for the same period in 2017, while sales for the second quarter to October were up nearly 12 percent to $426 million from $381 million for the same period in 2017.
Profits for the six months grew 55 percent to $87 million, from $56 million in the same period last year. For the second quarter profit after tax jumped 52 percent to $26.6 million from $17.5 million in 2017 in spite of picking up foreign exchange losses in the current period. Earnings per stock rose from 10 cents to 15.4 cents for the half year.
Lumber Depot sales rose 9 percent from $544 million to $592 million and the Blue Power division increased 25 percent from $217 million to $270 million for the six months
The Lumber Depot contributed $38 million before tax compared to $32 million in 2017 while Soap Division jumped to $61 million from $2 million in 2017.
Net finance cost was $9.5 million compared to $2.7 million for the quarter and for the six months it was a net inflow of $13 million in 2018 and was flat for the 2017 period.
For the half year, “exports sales of soap accounted for 24 percent of overall soap sales,” Noel Dawes, Managing Director told shareholders, in a report accompanying the financials. He further stated that “sales in the Caribbean market continue to be brisk as greater interest, acceptance and satisfaction of our product range materialize. The increase in export sales over the same quarter in the previous year was 64 percent from $47 million to $77 million.”
The company should earn around 30 cents per share for the current fiscal year and close to 40 cents for the next fiscal year ending April 2020. The stock trades at $5.45 at a PE ratio of 18 times estimated current year’s earnings.
Blue Power has investments and cash funds amounting to $247 million, with current assets of $655 million versus current liabilities of just $131 million and shareholders equity of $839 million.

Why is Fontana IPO priced so low?

Owners and directors along with their advisors ought to know the value of their company. But this publication must ask the question if Fontana has really done so well and will continue to expand, why is it priced so low?
At a premium over net book value of 88 percent, the stock is one of the cheapest of Junior Market listings, with the vast majority selling at a premium of 3 to 4 net book and an average PE of around 13 excluding the extreme highs and lows. One would expect the stock to be priced closer to 10 times earnings before tax, that would put the price closer to $3 than $1.88 and that would place price to net asset value at a premium of 200 percent, still below the market average. The fact that the company is setting up a new branch and looking for more expansion, makes the case for a higher price more compelling as investors are most likely going to rake in much profit from this stock. The only problem the general public will not get many shares  to buy up front as it is set tobe heavily oversubscribed. Investors can expect this one to at least double shortly after listing.From where we sit we think the brokers did the owners out of several million dollars on this issue but then the owners may want Jamaicans to party with them on the 50th anniversary.

Scotia Group stuck in neutral

Investors could find themselves in shark infested waters if they are not careful with the prices of several stocks now at very high levels. Investors need to be careful of being sucked into attractive profit results that are not based on sustainable earnings.
A case in point is Scotia Group. In the July quarter the interim results showed a big jump in profits, but that was based on an unsustainable rise in foreign exchange earnings due to the slippage of the Jamaican dollar, resulting in nearly $2 billion raked in for the quarter. For the October quarter only $396 million is reported for that line item, but the year shows a big jump from $2.5 billion to $4 billion. Net interest income is on the slide, falling from $26.64 billion in 2017 to $25.2 billion in 2018 and in the quarter the decline continues with October falling to $6.1 billion from $6.3 billion in July and $6.7 billion in the October quarter in 2017. While loan provisioning is down, year over year to October, to $1.9 billion from $2.2 billion it rose in the final quarter to $744 million from $695 in 2017 and $620 million in July this year. Net fee income has been steady for the various quarters at just over $2 billion but fell in the fiscal 2018 year to $8.1 billion from $8.6 billion.
Operating expenses rose to $5.74 billion in the October quarter from $5.1 in July and $5.18 billion for the 2017 final quarter. For the full year operating expenses rose to $22 billion from $21.3 billion. The group had a gain on disposal of a subsidiary of $753 million which saved profit from falling for the latest year with a rise to $12.78 billion from $12.17 billion in 2017. For the quarter, profit dropped to just $1.6 billion from $3.36 billion in 2017.
Importantly, the loan portfolio that rose strongly in the July quarter to $177 billion is up at a slower pace of 3.2 percent to $183 billion, an annual pace of 13 percent, but it needs to increase further to really deliver a reasonable increase in profit going forward.
The stock closed at $54.05 on the Jamaica Stock Exchange on Thursday, but its recent profit performance does not send very encouraging signals to buy.