Another big quarter for Jetcon

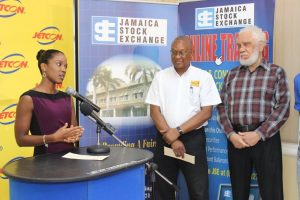
Sanya Goffe addressing the audience at the listing of Jetcon's shares in March.

Sanya Goffe addressing the audience at the listing of Jetcon’s shares in March.

Jetcon Corporation enjoyed two good years in a row with another good quarter results for the June 2016 quarter, with profit rising 91 percent to $23 million up from $12 million for the similar period in 2015. For the year to June, profit rose to $41 million, an increase of 71 percent over the $24 million earned in 2015 before corporation taxes.
The company accounted $4.7 million in tax, in the first quarter but none in the second quarter, with the shares listing on the junior market in March, this year. Earnings per share ended at 12 cents versus 8 cents for the June quarter and 21 cents for the six months to June compared with 12 cents for 2015.
Having been listed on the junior market our profit will be tax free for 5 years. With just half the year completed, profit is 9 percent off from the after-tax profit of $40.3 million reported for the full 2015 financial year and the company seems poised to surpass the 2015 earnings in the September quarter, if recent trend for 2016 to date continues.
Revenues climbed 39 percent for the quarter to $194.9 million and 45 percent for the six months to $342.9 million. Gross profit margin declined to 18.54 percent from 19.24 percent in the quarter and 19 percent for the six months versus 18.38 percent in 2015. Sales are usually greater in the second half of the year than in the first half.
honda civicIn a release by directors accompanying the financials, the company stated that “Administrative and other costs rose by approximately $5.2 million due to listing on the market which accounted for $2.5 million while salaries adjustments accounted for $2.7 million of the increase. Part of the increase in salaries is directly tied to the increased sales that took place.”
“Sales in June were the highest for the half year with sales for July is ahead of June in volume and sales revenues. Bookings which have been ahead of 2015 for each month this year continues to be positive.”
Inventories stood at $236 million at the end of June, compared to $125 million in June 2015 and $84 million at the end of December last year. Supplies peaked in June and is slated to start to decline by the end July onwards to the end of the year as deliveries to customers exceed new inflows of cars. Payables increased as a result of increased purchase of motor vehicles.

Junior market legislation draft ready

A Shaw address ptlLegislation is ready to come to parliament to make the junior market tax incentive retroactive to April 1, this year to restore the incentive to its original benefits of 100 percent tax-free status for 5 years and 50 percent of the regular tax for the second 5 years, Minister of Finance, Audley Shaw recently.
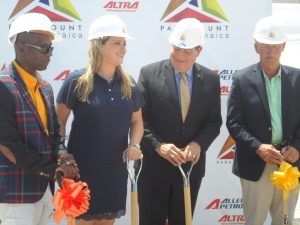
Shaw made the announcement when he delivered the keynote address at the official ground breaking of the Allegheny Petroleum and Paramount Trading joint venture lubricant factory in July to be built at 39 Waltham Park Road in Kingston.
Benefits far out weight the loss in revenues given up by the government, Shaw said. He stated that while corporate taxes were foregone, government saw increased intake from other taxes as a result of the expansion of junior market companies. He indicated that GCT intake grew by 337 percent by junior market companies, with NIS, NHT rising by 100 percent.
“Shaw went on to state that the time for fooling around is long past” we must chart a course to a better future urgently and commended the thrust Prime Minister Holness was pursuing to focussing on growth in an aggressive way. He said that “with 13,000 new hotel rooms to come on stream over the next 5 years that an avenue is being provided for additional goods for the sector to be provided by local goods producers for the sector.”
Shaw commended the joint venture partners and stated that is what he expects to see with a more economically friendly environment that should encourage local production for exports or import substitution.

Expansion for Paramount

PTL Lub Grnd bkingAllegheny Petroleum and junior market listed company, Paramount Trading joined forces to establish their jointly owned lubricant plant to be housed at 39 Waltham Park Road the same site as Paramount other operating facility.
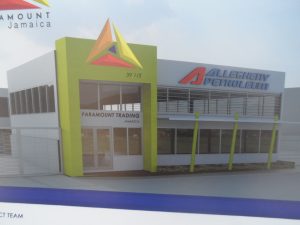
The plant for which ground was broken in July, is expected to replace imports amounting to approximately US$4 million now being supplied directly by Allegheny Petroleum, according to Hugh Graham, Managing director of Paramount.
Establishing operations in Jamaica, adds more value and will allow for a greater customer reach and create greater margins than that which applies to imports. The initial investment is US$4 million and includes the warehouse, equipment, software and lab testing equipment. The venture will have the capability to test lubricants in use for customers in Jamaica rather having to send samples overseas for testing. There are plans to expand product range in the future and provide products for exports. The plant is expected to start production in January next, Graham confirmed with IC Insider.
According to Graham in 2012, when they listed on the junior market, Paramount had 36 workers and now has 76 employees and the number will increase to 100 employees, with the latest expansion.
The ground breaking ceremony was addressed by Minister of Finance, Audley Shaw, who indicated that this venture vindicated the decision of the government to provide the tax incentive for the junior market as well as the economic policies being pursued that is geared to encourage more production of goods in Jamaica as opposed to relying on direct imports.
Robin Levy, assistant general manager of the Jamaica Stock Exchange indicated that the company has done well since it has listed and said “since listing in 2012 the company has gone on record higher revenues and tripled profit with the stock price rising from $2.45 to just under $11.” Since the ground breaking, the stock traded at $11.50 and now has a bid at $12.
In the year to May, the company posted an 18.5 percent increase in profit, to reach $173 million, from sales revenues of $1.02 billion with other income accounting for $39 million for the year, up from $869 million versus $16 million in 2015, respectively. Administrative, selling & distribution cost rose sharply by 34 percent to $181 million as the wage bill and rental expenses grew appreciably.
PTL All buidWhile profit grew in the year, segment results show mix out turn for each division. For 2016, Chemicals grew revenues by 12 percent and gross profit by 19 percent over 2015, for Construction and Adhesives, for the same periods, revenues grew by 59 percent and gross profit by just 6 percent. Manufacturing sales fell by 16 percent with profits remaining unchanged, while Transport enjoyed a 16 percent growth in sales leading to a 61 percent rise in profit and Lubricants sales climbed 403 percent with profits jumping 127 percent. Graham indicated to IC Insider that the fall in manufacturing sales is due to a customer reorganising their business. The data suggests that the new lubricant plant is likely to be the area of growth for Paramount.
In 2015, Graham indicated that a rights issue was likely, asked about that source of funding for the expansion, Graham stated “I can’t talk about that now,” he however, stated that “some other revenue announcement should be made soon.”

Sagicor Group flat Q2 profit

Sagicor Group HQ - the stock closed at $21.45 on Friday.

Sagicor Group HQ – the stock closed at $21.45 on Friday.

Sagicor Group recorded a 15 percent increase in profit attributable to Stockholders of $4.31 billion for the six-months ending June 2016, over last year, resulting in earnings per stock unit of $1.10 compared to 96 cents. The company was not as fortunate in the second quarter as earnings were flat at $2.4 billion from a jump of 10 percent in revenues to $15.3 billion.
Total Comprehensive Income jumped sharply in the quarter to $5.7 billion from $1.9 billion at June 2015 and for the six months it stood at an impressive $8 billion versus $3 billion in 2015.
Expenses climbed 13 percent to $12.28 billion including administrative cost that rose 16.4 percent to $3.88 billion. Segment results show mixed fortunes, with Individual Lines slipping 9 percent to $800 million, down from $875 million, Employee Benefits jumped sharply by 49 percent to $1.87 billion, while Investment Banking grew by 6 percent, to $850 million. Commercial Banking fell 28 percent or $228 million to $585 million as write down of tax recoverable, took $250 million out of profits, in 2015 the group indicated that results for this segment was boosted by higher than expected recoveries on delinquent loans. Other segment jumped $220 million or 148 percent to $368 million while the company share of Sagicor Real Estate Fund contributed $153 million in the quarter and $329 million for the six months against no earnings in 2015.
Sagicor’s main focus is on the sale of personal insurance related products and banking, its success will be its ability to manage funds it receives and use in investment.
The group reported earnings of $2.51 for 2015 and with the performance this year to June, full year earnings should end up around $2.90, suggesting the stock should rise in the months ahead with the PE ratio at 7 times 2016 earnings versus an average of 9 for the main market. The stock last traded on Friday on the Jamaica Stock Exchange at $21.45.
At the end of June, equity attributable to stockholders climbed to $51.69 billion up from $46.57 billion, while total assets climbed 7.3 percent to $322.4 billion from $300.4 billion at the end of December 2015.
Outlook – “Our Group continued to produce good results in all areas. We are seeing the benefits of our business growth, digital and service-oriented strategies. We expect the second half year to be even better than the first,” Chairman, Danny Williams and CEO, Richard Byles, told shareholders, in the report of directors accompanying the financials.
Sagicor paid an interim dividend of $2.58 billion to stockholders or 66 cents per share, in April this year which is 69 percent higher than the $1.52 billion or 39 cents per share for the similar period in 2015. A second dividend is expected before the end of 2016. An interim dividend of 34 cents per share was paid to shareholders in November 2015.

Flat results, increased profit at tTech

tTech closed at $4.50 on Thursday.

tTech closed at $4.50 on Thursday.

tTech enjoyed a big 42 percent growth in revenues for the June quarter to $58.4 million from $41 million at June 2015, well ahead of the 14 percent growth in the March quarter. For the six months, revenues are 30 percent to $105.6 million from $81 million in 2015.
Profit after tax, is up to $16 million from $12.4 million for the six months and $9.2 million versus $7.6 million in 2015, but for tax expense saved in 2016, profit for the year to date would be flat. Profit for 2015 was subject to $1.4 million in taxes and for the six months, $3 million. A sharp rise in operating expenses due to a 50 percent rise in staffing, pushed the spend by 54 percent to $50 million for the quarter and 36.4 percent to $91 million for the half year.
Earnings per share ended at 9 cents for the quarter and 15 cents for the half year and should end up around the 35 to 40 cents range for the full year based on the results to date. The strong revenue gain is a signal for growth going forward for the company.
Management stated that “the increase in revenue was due to growth in all areas of our services including the Consulting Division. Increase in expenses was driven primarily by increases in our workforce to increase capacity to meet the growth in demand. At June 30, 2016 the company had 31 full-time employees compared to 21 at the same date in 2015.”
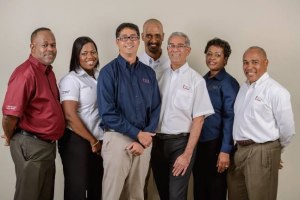
From Left: Mr. Hugh Allen, Resolution Manager and Executive Director; Mrs. Natalya Petrekin, Service Desk

From Left: Mr. Hugh Allen, Resolution Manager and Executive Director; Mrs. Natalya Petrekin, Service Desk

Demand for the company’s services remains strong. Going forward improving our efficiencies by automating more processes will be an area of focus. Work has already started in this area and more
opportunities for automation will be explored to facilitate increased efficiencies and improved service delivery.”
The company ended with cash and investments amounting to $115 million at June, up from $67 million at the end of December last year with net current assets ending at $130 million with payables at $34 million, while shareholders’ equity is at $146 million.
The stock traded as high as $5 on the JSE junior market today but fell back before the close to $4.50 for a PE of just over 11 times projected 2016 earnings. For investors will the strong growth continue and deliver increasing profit for them to buy and hold at these prices for long term gains.

Cargo Handlers’ share goodies

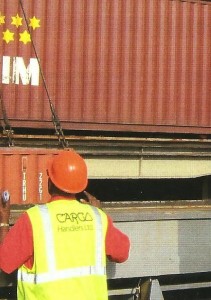
Cargo Handlers to split stock 10 for 1.

Cargo Handlers to split stock 10 for 1.

Cargo Handlers‘ shareholders will see a 10 to 1 stock split when they vote on the recommend stock split by directors. Stockholders will also be asked to authorize an increase in the capital of the company to 466,200,000 shares from the existing amount of 40 million units, to accommodate the split. No date has been set for the meeting to approve the split.

The shares now issued amounts to 37,465,830 units but the stock trades infrequently as very few are in the hands of the general public. The stock split is expected to enhance liquidity of the stock.
The stock last traded at $56 on the junior market of the Jamaica Stock Exchange having shot up from $46 after the announcement was made that the directors were meeting to recommend a split. There are currently ids to buy the stock between $60 and $64.01 for 10,877 units, the last offer was 919 units on at $66, at the close on Monday.
The directors declared an interim dividend of $1.35 per share to be paid on September 13, with the ex-dividend date set for August 17.
The company enjoyed a buoyant June quarter, with revenues rising 55 percent from $56 million to $87 million and for the nine months by 36 percent to $245 million from $182 million. Profit before tax rose to $53 million from $29 million in 2015 and after taxation, profit ended at $46 million from $29 million. For the nine months, profit rose from $108 million to $143 million before tax, with the 2016 results ending at $125 million after tax, there were no taxes in 2015.
Management attributes the strong growth in third quarter revenues and profit, to increased activity in the Montego Bay region and increased port activity, flowing from the conversion of the Jamaica Public Service power plant to LNG gas.
Earnings per share for the quarter ended at $1.23 and $3.32 for the nine months. Full year’s earnings should be just under $5 per share but scarcity of the stock is driving the valuation up.

Access post good Q1 results

Access Financial Services' profit jumps 29% in Q1.

Access Financial Services’ profit jumps 29% in Q1.

Investors have not reacted positively to the 29 percent gain in Access Financial Services profit for the June 2016 quarter over the results of the 2015 quarter, but they probably should, with earnings set to exceed $2 for the full fiscal year with the stock price below $20.
The company reported a moderate 10 percent growth in loan interest revenues to $301 million in the quarter over that of 2015. The loan portfolio for the June is 8.6 percent ahead of March, if the rate of growth continues, loans would end at $2.84 billion versus $2.1 billion as of March.
Total revenues moved by 10 percent from $315 million to $347 million for the June quarters while profit after tax for the quarter grew 29 percent to $146 million or 53 cents per share, compared to $112 million or 41 cents for the June 2015 quarter.
Cost was well contained at $184 million for the quarter, down from $186 million in 2015. Loan loss provisions fell from $54 million in 2015 quarter, to $43 million in 2016. IC Insider projects the provision to rise to $187 million for the full year, up from $184 million for the 12 months to March 2016, while earnings of $800 million or $2.90 per share are projected for the 12 months to March 2016, with growth to $4 per share or $1.1 billion in profits after tax, for 2017.
At the end of March, shareholders’ equity stood at $1.3 billion and borrowings at $1.1 billion with cash and equivalent at $299 million out of total assets of $2.7 billion.
The stock which remains BUY RATED last traded at $17.50 giving it a PE based on the above forecast at an attractive 6.

Simply Impressive

Honey Bun shot up by more than 500% in 2016 shortly after stock split.

Honey Bun shot up by more than 500% in 2016 shortly after stock split.

Junior market listed bakers, Honey Bun, is enjoying a glorious period of surging revenues and profit that fueled a huge jump in the stock price of 355 percent for 2016, after rising over 500 percent, earlier in the year.
In continuation of a successful year, revenues climbed 36 percent in the third quarter of financial year to June, spawning a 124 percent increase in profit before taxes to $38 million over the June 2015 quarter. Revenues climbed 35 percent to $903 million for the nine months to June, up from $672 million in 2015 while profit jumped 109 percent to $138 million before tax and $132 million after tax of $6 million.
Gross profit for the nine months climbed at a faster pace than revenues, at 40 percent while for the quarter, gross profit rose 34 percent, just below the growth in revenues for the quarter. Expenses excluding cost of sales, rose even slower than revenues, at 20 percent, with administrative expenses rising sharply by 33 percent to $147 million and selling and distribution costs increasing by 10 percent to $104 million, while depreciation rose by 4 percent to $28 million. For the June quarter administrative, selling and distribution expenses rose at a slower pace than for the nine months, at 12 percent.
One Honey Bun's Products.

One Honey Bun’s Products.

The company generated gross cash flows of $171 million for the nine months, before expending $75 million on the acquisition of property, equipment and fleet. Honey Bun is in a healthy state with cash balance and investments at $104 million after the company repaid $38 million in long term loans, leaving loans at $16 million. Current assets stood at $212 million and current liabilities ta $71 million. Shareholders equity climbed to $491 million.
The Company that listed on the Jamaica Stock Exchange Junior Market in June 2011, is now subject to taxation on profit for the next 5 years at 50 percent of the normal corporate income tax rate of 25 percent.
Earnings per share for the quarter came in at 8 cents and 28 cents for the nine months. IC Insider projects 34 cents or $160 million for the full year to September, with $147 million or 52 cents per share projected for 2017. The stock traded at $5.60 on the Jamaica Stock Exchange junior market for a PE of 16.5 times 2016 earnings, making it one of the highest valued stock on the market.
The stock was accorded a BUY RATED ranking in November 2015 but has since been placed on a watch list when it shot to over $7 per share.

Loans to surge at Jamaica National

JNB HQJamaica National enjoyed a 10 percent increase in loans at the end of March this year over March 2015 to $66 billion inclusive mortgages that rose from $56 billion to $61 billion. Based on loans approved and not disbursed at the end of March, the loans portfolio seems set to climb at a much faster pace than for 2016 fiscal year.
According to the societies’ financials, loans approved but not yet disbursed jumped by a sharp 168 percent to $7.36 billion or 12 percent of outstanding loans, up from $2.75 billion or 4.9 percent of the loan portfolio at March 2015.
Jamaica National, Jamaica’s largest building society had a mix fortunes in fiscal year 2016 with assets climbing by 8.8 percent to $181 billion. Investment securities made up the bulk of the assets at $94 billion. Equity capital stood at $31.2 billion and savers deposits of $101.4 billion up from$90 billion in 2015.
The society suffered a sharp drop of 44 percent in profits to $1.42 billion from $2.53 billion in 2015. For the year to March 2014, profit jumped to $2.3 billion from only $908 million in the previous year.
Contributing to profit for the year was net interest income growing from $8.5 billion to $8.8 billion, other operating income that fell from $6.2 billion to $5.9 billion and operating expenses climbing from $11.8 billion to $13.3 billion.

Huge 25% jump in Q3 results for NCB

NCB posted a 16% jump in nine months' profits & declared a dividend of 50 cents.

NCB posted a 16% jump in nine months’ profits & declared a dividend of 50 cents.

Jamaica’s National Commercial Bank (NCB) posted a strong increase in profit after tax, for the June quarter with earnings jumping 25 percent or $789 million over the 2015 June quarter, to $3.9 billion. For the nine months to June, profit is up 16 percent to $9.9 billion compared to $8.6 billion in the 2015 period.
Earnings per share ended at $1.88 for the quarter, up from $1.29 in 2015 and for the period to June $4.31 versus $3.48, with full year earnings are set to exceed $6.
The gains were helped by an 11 percent climb in loans and advances to reach $180 billion and a reduction in a number of areas of cost, including a fall in loan loss provisioning to $157 million in the quarter from $472 million in 2015 and for the nine months from $1.4 billion to $904 million.
Customer deposits increased by 18 percent or $38.9 billion over June 2015 to $256 billion.
Total operating income net of interest cost and fee and commission expenses increased to $12.76 billion from $11.68 billion, for the quarter and to $38.4 billion compared to $35.3 billion for the period to June. Net interest income increasing by 8.8 percent, or $1.7 billion, due to growth in the net loans and investments and a reduction in interest expenses driven by a decline in funding costs.
NCB management stated that for the nine months, net fee and commission income increasing by 10.3 percent, or $743 million, mainly due to credit related fees from growth in the loan portfolio, higher volumes of point of sale transactions and unit trust commissions arising from growth in the portfolios. Premium income grew by $388 million, or 6.8 percent, due to higher levels of life insurance and annuity contracts. Gain on foreign currency and investment activities increasing by 10.8 percent, or $305 million to $3.1 billion.
Overall expenses grew slightly from $7.46 billion to $7.64 billion for the quarter and for the nine months by 3.8 percent from $24.1 billion to $26 billion well below the increase in revenues.
NCB declared an interim dividend of 50 cents per ordinary stock unit payable on August 29, to stockholders on record as at August 15. NCB remains an IC Insider Buy Rated stock. In Trading the stock closed at $42.50 today on the Jamaica Stock Exchange for a PE of 7 and on the Trinidad and Tobago Stock Exchange at TT$2.75 or the equivalent of J$52.