 NCB Financial Group reported net profit of $4.6 billion for the quarter ended December 2017 and hiked their dividend. Profit increased 28 percent or $1 billion over 2016. Revenues net of interest cost rose 17 percent to $16.7 billion from $14.2 billion in 2016.
On the surface the gains in profit sounds great, but closer examination reveals that $1.5 billion comes from a one off gain resulting from the acquisition of majority shares in Clarien. The group incurred cost associated with staff separation that help swell staff cost to $5.9 billion from $3.75 billion in 2016 while Policyholders’ and annuitants’ benefits and reserves rose from $1.03 billion in the first quarter of 2016 to $1.78 billion.
Return on average equity increased to 15.7 percent from 14.0 percent in 2016. Net loans grew 63 percent to $322.4 billion from $197.9 billion and from $218.6 billion at the end of September 2017. Growth was due to the consolidation of Clarien Group, accounting for $93 billion and increases in retail loan portfolio
Segment results were mixed with consumer and small and medium enterprise Retail and SME being worse off in 2017 than 2016 by $290 million and Payment Services for the sector increasing profit by $325 million to $1.2 billion. Corporate banking enjoyed lower operating profit of $95 million leading to $710 million in the quarter, Treasury & Correspondent Banking was virtually flat at $1.6 billion. Wealth, Asset Management and Investment Banking grew strongly by $440 million to $1.2 billion, Life and Pensions had strong growth of $438 million to $1.3 billion but general Insurance was $536 million worse off in ending with a loss of $108 million.
NCB hiked interim dividend to 70 cents per share up from 60 cents in 2017. The dividend is payable on February 26, for stockholders on record as at February 9, 2018.
NCB Financial, closed at J$100.85 trading 59,911 shares on the Jamaica Stock Exchange and TT$6.60 ($J$123) trading 261,082 shares, on the Trinidad and Tobago Exchange on Thursday.
NCB reports 28% profit growth but..
Elite interim figures lack credibility
Elite Diagnostics interim figures are wrong and need auditing.
Elite Diagnostic issued an addendum to the prospectus for the public issue of shares. They should withdraw the issue, until they have the interim figures audited and fixed. For even after they amended them to correct for errors, $15 million is still unaccounted for.
The interim results, initially included in the prospectus and in the addendum to them, send a shocking picture of the amateurish approach to the company’s financial stewardship.
The company reported first quarter numbers without the significant cost of depreciation, which when included, reduced the profit by approximately 40 percent. To compound the matter, the figures are presented in cents which is shown is no other place in the prospectus, no experienced accountant would provide public results with cents included. The presentation tells a sorry story as to the errors that are in the report and are still there.
In a report of a missing $11 million, IC Insider.com pointed out the error re depreciation and fixed assets. In the addendum, fixed assets are up by $3 million but the figure is still short of what the data in the report suggests it to be.
At the end of June last year, fixed assets amounted to $187 million, with the cash flow to September showing $74 million being added and would bring the total amount to $262 million, before depreciation of $9 million for the first quarter and would result in net fixed assets of $253 million. The interim results have the figure at $238 million, a huge difference of $15 million.
Deferred tax liability of $9.5 million reported in the June year end audited report disappears in the interim figures and may actually be a part of the error in the report. Without a proper checking of the data along with documentations of large transaction is difficult to say where the error may be and that is why the figures should audited at this stage to ensure integrity of the numbers.
$11M missing from elite figures
 $11 million are missing from the first quarter figures included in Elite Diagnostic prospectus to raise $141 million in an IPO.
While the 2017 audited accounts show depreciation and amortization of $28 million and administrative expenses of $81 million,the interim figures show no amount for depreciation, with administrative cost of $24 million which is just over 25 percent of the full years cost to June. Direct cost is $87 million for the fiscal year or just under $22 million per quarter, in line with $21.7 million in the September quarter. The conclusion is that the cost of depreciation is not included and would result in profits falling from $23 million reported to $14 million and would reduce the expected full year earnings below the annualized figure of $92 million down to a much lower amount, assuming that the new location at Old Hope Road just break even.
Elite Diagnostics is the first 2018 IPO out of 9, that is expected this year.
The intrigue does not end there. The movements in fixed assets show a missing $11 million, with fixed assets at June being $187 million and the cash flow statement showing additions of $71 million, that should result in a total of $257 million which would be reduced by approximately $9 million for depreciation for the quarter, bringing the net figure to $249 million but the interim figures have fixed assets at $238 million. For short, a material amount of $11 million is missing and it is unclear what items are under or over stated.
On the face of it, the reported profit for both years appear overstated, on that basis, IC Insider.com reduced earnings per share for the full year to 20 cents, with the stock being priced at 10 times earnings, but that still leaves the stock a buy.
NCB offer for Guardian extended
 NCB Financial Group extended the closing date for its offer to buy up to 62 percent of the Trinidadian based, Guardian Holdings’ shares to February 2 instead of the original date of January 12.
According to a release by NCB “while the majority of the terms and conditions of the Offer have been satisfied or otherwise waived and the Offeror has received the sign-off from most of the relevant regulatory authorities in respect of the proposed acquisition, the Offeror has applied for and is awaiting certain other regulatory approvals required to be obtained by it before it may take-up and pay for any tendered Offer Shares. Such regulatory approvals are required as a result of the Offeror and GHL, along with several of GHL’s subsidiaries, being regulated in Trinidad and Tobago and elsewhere in the region. Given the foregoing, the Offeror has elected to extend the Closing Date to the 2nd day of February.”
In May 2016 an interest in 69,547,241 GHL Shares were acquired by NCBFG at US$3.24 per share. At the time of the acquisition, NCBFG entered into a shareholders agreement with Arthur Lok Jack and Imtiaz Ahamad and several of their affiliate entities. The shareholders’ agreement included a lock-up provision in relation to both NCBFG’s and the  Key Shareholders’ GHL Shares by which the parties agreed to limit their rights to dispose of any GHL Shares until the expiry of three years from May 12, 2016. The agreement required NCBFG to make a take-over bid within three years to gain a minimum of 62% of the outstanding GHL shares and that the Key Shareholders agreed to tender all their GHL Shares (approximately 21.84 percent of the GHL shares) pursuant to such take-over bid. The price of the take-over bid would be, an offer up to May 12, 2017, a minimum price of TT$17, or an offer after May 2017 but up to May 2018, at TT$18 and TTS19 if made after May 2018 to May, 2019.
In November 2017, the shareholders agreement was amended to provide that should the offer be made by February 12, 2018, the price of the offer would be US$2.35 per share instead of TT$18 for an offer made up to May 12, 2018.
Elite Diagnostics IPO is now here
The initial public offer for Elite Diagnostics will open on January 22 at a price of $2 per share, with the issue scheduled to close on January 29, an advertisement in the Jamaica Observer indicates.
A total of 70.68 million shares are offered to raise $141 million. The shares are expected to be listed on the Junior Market of the Jamaica Stock Exchange, if the issue is successful and will bring the total company listings on the Junior Market to 35 and the total listings to 39 and the total listings on the entire exchange to 96.
The proceeds from the offer will be used for expansion. The company operates from Holburn Road in Kingston and now have a new office on Hope Road. The 5 year old company provides imaging and Diagnostic Medical Facility offers services such as MRI, CT Scan, X-Ray, Ultrasound and Fluoroscopy.
The offer which was expected in December last year, is one of nine the Jamaica Stock Exchange expects to list in 2018. Elite will be the second medical related company to seek to list on the Jamaica Stock Exchange Junior Market and the second within two months. One doctor when quizzed about the company informed IC Insider.com that the company is recommended highly from a professional viewpoint, due to the high level of professional skills the team posses.
IC Insider.com will provide a detailed review and recommendation when the prospectus is posted on the Jamaica Stock Exchange on Monday.
CAC 2000 profit rise but
 CAC2000 the air condition engineering company, reported improved profits for the year to October 2017, after accounting for a provision of $104 million for court judgement claim in the 2016 results.
Profit excluding the amount of the claim fell slightly to $100.5 million in 2017 from $115 million in 2016. Revenues rose 19 percent to $1.2 billion. The situation would have been worse but for a $20 million swing around in bad debts which reduced cost in 2017 by $9.8 million compared to cost of a similar amount in 2016.. Operating cash flows before movements in working capital brought in $121 million up from $49 million in 2016.
Even as revenues climbed strongly, gross profit hardly moved rising to $424 million from $410 million in 2016 as direct cost rose faster than revenues with an increase of 29.5 percent to $786 million.
Directors’ remuneration climbed 25 percent to $41.2 million from $32.5 million, well ahead of the 5 percent increase in staff cost to $116.3 million for the year. Legal and professional fees jumped 47 percent, to $33 million.
Earnings per share ended the year at 78 cents, the stock traded at $7.50 on Friday, before the close of the market. Borrowings ended the fiscal year at $260 million up from $165 million at the end of the 2016 fiscal year, shareholders’ equity rose to $423 million from $322 million in 2016. Cash funds stands at $192 million even as trade receivables climbed $180 million to $536 million but inventories fell $80 million to $209 million.
.
Profit surge 79% at Main Event
Main Event was the 4th best performing Junior Market stock for 2017.
The improvement in the topline, was sufficient to deliver a strong 79 percent increase in profit for the year, to reach $101 million after tax, up from $56.5 million, as the company made profit in the last half compared to a loss in 2016. For the final quarter, in spite of the reduction in revenues to $234 million versus $277 million in 2016, a small profit of $7 million was achieved versus a break even position in 2016.
Cash flow from operation provided $188 million up from $118 million in 2016, but the company purchased fixed assets of $137 million and reduced net liabilities having received proceeds from the issue of shares amounting to $103 million.
Importantly, direct cost fell by $94 million for the year compared to 2016, but administrative and depreciation cost rose by the same amount. With the rise in revenues, gross profit margin improved leading to a strong increase profit for the year. Some of the improved gross profit seemed to have been achieved by cost ending in administrative and depreciation expenses.
The company’s working capital has improved over 2016 with current assets at $292 million compared to current liabilities of $184 million, in 2016 it was $186 million to $212 million. Equity capital is up to $446 million from $242 million in 2016 while borrowings are down to $170 million versus $204 million, with cash funds of $91 million.
Earnings per share adjusted for tax is 38 cents and IC Insider.com projects 55 cents for 2018.
The stock traded at $5.80 on the Junior Market of the Jamaica Stock Exchange at the close on Thursday for a PE ratio of 11.
The nature of the business exposes it to possible swings in revenues some of it being weather related and others based on the timing of major entertainment events. The effect of such movements suggest that investors may be best rewarded based on a longer term investment posture to benefit from positive surprises in increased business.
Mayberry restructuring
Mayberry to spin off 10 % of its subsidiary to shareholders.
Dogged by a share price that is bogged down mostly below $5, with a net asset value of $6.54, Mayberry’s directors are recommending distributing a portion of Mayberry West Indies Limited (MWIL), a wholly-owned subsidiary in the form of dividend to Mayberry Investments‘ shareholders.
MWIL is to list on the Jamaica Stock Exchange before the end of the first quarter of 2018 as a result of the move.
Arising from a Board meeting of the Company, on December 29, 2017, a dividend in specie equal to 10% of the Net Book value of its MWIL was declared. This dividend will be effected by the Company transferring, pro rata among its stockholders, shares in MWIL held by the Company and constituting 10% of MWIL’s issued share capital. The record date will be February 16, and shall be effected by transfer of the relevant MWIL shares on February 28 to stockholders. The Ex-dividend date will be February 15.
Based on MWIL’s book value as at November 30, 2017, the dividend in specie is equivalent to approximately $688 million, the Mayberry release said. Mayberry West Indies Limited name is to be changed to “Mayberry Jamaican Equities Limited”.
The Jamaica Stock Exchange requires a minimum of 20 percent of a listed company’s shares to be issued to the public, accordingly, it appears that the plans will be to raise around $700-800 million from the general market prior to listing.
Wisynco Group cut some prices
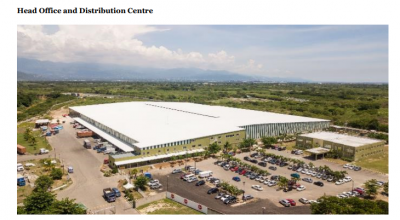
Wisynco operates at two main locations situated in St. Catherine: White Marl and Lakes Pen.
Recent Jamaica Stock Exchange listed Wisynco Group, announced a reduction in the prices for the majority of its imported portfolio of products, effective January 2. The reduction that the company said is 3 percent, is due to a revaluation of the Jamaican dollar to the US dollar in recent months.
The adjustment is in line with the appreciation in the value of the local currency versus the US dollar since it peaked at $131 in September.
The company who shares were issued to the public for sale in December further advised that it has commenced distribution of the Unilever Portfolio of Food products throughout the island. The portfolio includes: Red Rose Tea, Lipton Tea, Knorr, Ben & Jerry’s, Breyers Ice Cream, Hellman’s, Blue Band, Flora, Country Crock, I Can’t Believe It’s Not Butter and several other popular items.
The company’s shares traded on the main market of the stock exchange at $12 at the close on Wednesday and is up from the IPO price of $7.87.
NCB pre-announces dividend dates
 NCB Financial Group has announced the dates when their board will consider dividend payments for 2018, in a break from the historical practice of making an announcement a few days before the board meets to consider the quarterly payment.
The practice is in keeping with what obtains in Trinidad with several listed companies pre-announcing dates for dividends, publication of quarterly reports and annual general meetings. The move enhances transparency in the capital market where all concerned are aware of important announcements. NCBFG advises that the board of directors intends to consider the payment of dividends to stockholders on the following dates this year, January 25, April 26, July 26 and November 8. The dates usually coincide with the release of the quarterly reports.