 Start up C2W Music is reporting its first quarter of profits since it was listed on the junior market in 2012. The company that had chalked up losses in each quarter since listing, shows a profit of US$16.6000 for the June 2014 quarter, in its latest release of results.
The company booked copy right income of US$30,000 in the quarter and royalty of only US$189, but with administrative expenses of $12,193 and finance cost of US$1,396 the income was enough to leave a surplus for the quarter. This compares with a loss of US$157 million in the 2013 quarter. For the six months to date, losses are down to $66,000 versus $346,000 in 2013. Is this the light at the end of the tunnel? Management seems to think so as the quote to shareholders show below suggest.
“The Company negotiated an extremely strategic joint venture music publishing deal with one of our songwriters and an extremely successful music publisher, Rebellion Corps/Notting Hill Music. In this joint songwriters and an extremely successful music publisher, Rebellion Corps/Notting Hill Music. In this joint venture, they will help us in securing homes for more of our copyrights, which will result in increased revenue for the Company. The Company continues to work closely with the Caribbean Performing Rights Societies to recognize our rightful revenue, as their new royalty distribution systems are now in place. The Company continues to exploit our own catalogue and continues to have success in this area. We are also proud and happy to know that the Maxi Priest album is doing very well with two of our songs on the album, and the Etana album is heating up to be a success story also,” Ivan Berry the company’s CEO stated in commenting on the results.
At the end of the quarter, the company had equity of only US$34,000 having racked up net losses of US$1.25 million, loans of $75,000 and cash of only $2,000.
C2W Music reports 1st profit
Medical Disposables revenue up 26%, profit 13%

Winston Boothe – Chairman Medical Disposables & Supplies
Profit after tax is up 55 percent as there was no tax charge in the June 2014 quarter, but tax ate up $4 million of the 2013 profit. “The main reason for the growth in revenue is the strategic focus on new and wider product offerings and greater market penetration”, Kurt Boothe, General Manager stated in his report to shareholders.
Gross profit grew 27 percent to $65.6 million from $51.66 million and gross margin moved to 36.24 percent in the quarter, from 33.78 percent in the 2013 June quarter but down from 42.15 percent in the March 2014 quarter. “This improvement was due to the product sales mix, increases in sales of products with higher margins and consistent review of our pricing structure to maintain the gross margin efficiency” Boothe stated. The audited accounts showed Gross profit margin of 35 percent for 2013-14 fiscal year.
Operating expenses climbed 49.7 percent in the June quarter over the 2013 quarter and “was driven mainly by staff related expenses, professional fees and special bank charges. Staff related expenses, in particular, were driven by the strategic decision to realign the staff complement and compensation to sustain the current growth, development and expansion of the business,” the general manager stated.
Earnings per share for the June quarter was 6 cents per share with the full year set to come in around 25 to 30 cents per share based on existing operations. At a stock price around $2 there is not much room for the price to make any major moves in the short term, unless the stock market becomes bullish.
Medical Disposables was listed on the junior market of the Jamaica Stock Exchange in December 2013, when it sold 63,157,895 Shares at $1.83 each and raised $113.7 million in its IPO.
Year over year current assets climbed from $370 million to $514 million due mainly to the IPO funds raised, while current liabilities stood almost static at $221 million. Shareholders’ equity jumped to $369 million from $163 million in March 2013 while borrowed funds are down from $147 million to $128 million, or just under two years’ cash flow.
Big jump in RJR Q1 profit (BUY RATED)
Radio Jamaica’s (RJR) profit for the first quarter to June jumped by 829 percent to $15.2 million up from only $1.6 million in 2013. The bottom-line improvement came from an increase of 7 percent in revenues for the June quarter, to $507 million.
Revenues from operation actually rose by 10 percent but a fall in other income from $35 million to $21 million, pulled the overall revenue gains down. Gross profit grew 27.6 percent to $272 million and gross margin hit 127 percent in the quarter, up from 94 percent in 2013. The improvement came primarily from new revenue streams outside of Jamaica in the Caribbean region, Management stated in their commentary on the results as well as shared sporting activities and some cost reduction in the cost of covering sports.
Operating expenses climbed 11 percent in the 2014 quarter over the 2013 quarter, to hit $268 million. The audited accounts showed gross profit margin of 35 percent for the last fiscal year to March. For the twelve months to March this year, RJR made profit after tax of just $59 million, having just breaking even on its main operation. In 2013, the group made a loss of $77 million before taxation and $30 million, after recording a tax credit of $47 million. The group would have benefited from increase sponsorship and advertising income emanating from the broadcast of the world cup football on radio as well as the staying of commentary on Television. As such some of the improvements in both revenue and profits may not repeat any time soon. What seems of import is that the worse seems behind them now and with prospects of an improving economy ahead, added revenues should flow mostly to the bottom-line as most cost are substantially fixed. The stock is now accorded a BUY RATED rating.
IC Insider is forecasting $131 million or 35 cents per share earnings in 2015. They should generate gross cash of $250 million for the full fiscal period which should a far way in reducing their indebtedness.
On the negative side cash is down from $155 million in March this year to $113 million and receivables is up to $456 million from $370 million and borrowings are stable at $246 million.
What were these directors hiding?
 Cable & Wireless (CWJ) nearly 5 months to report insider trades by it senior directors. What were they trying to hide must be the question? Most companies report trades by insiders, a few days after the event.
There can be little excuse for this to have happened, in the case of the CWJ trades. Are there more trades that have not been reported, is an obvious question? The situation in the case of Cable & Wireless is most important, in light of the increased interest in the stock since the start of 2014, with what appears to be a trend of improving revenues and gain in market share, in a number of its business segments.
On Thursday the Jamaica Stock Exchange was informed by Cable & Wireless that that Senior Directors purchased a total of 5,290,069 shares, during the period March 17, 2014 to April 3, 2014.
The trades involved more than one person and at a senior directors’ level. As directors they have a duty to ensure information as critical as this is reported promptly, within a reasonable time to the exchange. Five months after the trades, is not reasonable.
Mayberry Investments advised that related parties conducted trading activity of 122,500 of the company’s shares on August 11 and 12, 2014.
Another director jumps KLE
 Craig Powell one of the directors and shareholder of KLE Group when the company had its IPO in 2012 finally gave up trying to turn the struggling entity around and resigned as a Director with effect from August 11, 2014, the Jamaica Stock Exchange was informed today. The signs were on the table for all to see when Powell in July, sold 7,181,043 units out of the 10,693,750 share he owned, at a huge discount to the IPO price.
Trinidad Cement making strides but debt a bother
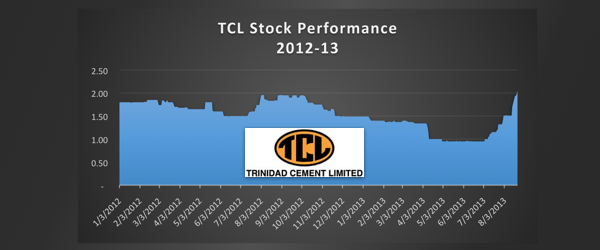 Trinidad Cement’s June quarter profit before tax bettered by a small amount the results of last year, coming in at $26.5 million versus $23.4 million, but after accounting for a non-recurring charge of nearly $26 million and lower finance cost.
Profit after tax due to shareholders of the company, amounted to $19 million for the quarter and in 2013 $46 million, helped by a tax credit of $33 million and for the year to June, the group reports profit after tax of $30 million versus $70 million in 2013. The non-recurring charge arose from a provision for retroactive pay increases and a charge of $16 million, mainly legal expenses incurred on the aborted debt refinancing exercise initiated earlier in the year. Had these charges not occurred, profit before tax would have been $52 million in the latest quarter. IC Insider is forecasting earnings of 45 cents per share for the full year.
“Key markets of Trinidad, Guyana, and Suriname remain buoyant whilst the others have stabilized and accordingly, the Group expects better second half results from operations, as the annual plant stops at the two largest plants have already taken place in the first half,” management, in its comments of the outlook stated.
Revenue in the quarter grew 9 percent to $512 million and for the 6 months from $994 million to $1.07 billion or 8 percent. Operating profit came out at $132 million in the June quarter, versus $114 million in 2013 and for the half year $232 million for 2014 versus $233 million in 2013. Finance cost slipped from $58 million in the June 2013 quarter, to $47 million, due to minimal devaluation in Jamaica compared to 2013. For the six months finance cost fell to $97.5 million from $123 million in 2013.
For the half year, Trinidad Cement generated cash flow of $144 million before loan repayment, up from $90 million last year. After loan repayment and the funding of investment activities, the group was left with $77 million of cash funds, up from $52 million at the end of June 2013. According to the 2013 audited accounts, the group was committed to repay $179 million during 2014 but that would still leave them with total loans of $1.77 billion and equity at the end of June of $573 million, therefore remaining in a highly over leverage position.
Investment in the stock is not without risk, with the heavy debt, in addition, the shareholders’ squabble to change directors, can create negatives for the group as well as it could be positive when everything is resolved. No one really knows how that will pan out. Based on the profit out turn and the likelihood for increased profits to come, IC Insider still accords the stock a BUY RATED status.
Pan-Jamaican hikes dividend, Eppley holds at $9
 Pan-Jamaican Investment announced a hike in the upcoming dividend, as the directors approved a third interim dividend for 2014, of 70 cents per stock unit, to be paid on September 26 to stockholders on record, at the close of business on August 27.
The X-Dividend date is September 24, 2014. Interim dividends of 60 cents per share were paid on June 20 and on March 31, this year.
Eppley Limited approved an ordinary dividend of $9 per share, payable on September 2, 2014, to shareholders on record as at August 26, 2014. The EX-Dividend date is August 22. Eppley paid an ordinary interim dividend of $9 per share on February 28, this year.
Supreme Ventures declared a dividend of 3 cents per share, to be paid to shareholders on record, at August 22 and to be paid on September 5, 2014. The stock trades EX-Dividend on August 20, 2014. Supreme Ventures declared a dividend of 3 cents per share payable on March 26, this year and paid a dividend of 3 cents per share, on January 8, 2014. In 2013, dividends per share were paid as follows: 3 cents on September 2, 8 cents on June 17 and 10 cents on March 28.
Cargo Handlers declared a dividend of $1.30 per stock unit, to be paid on September 16, to stockholders on record at August 26, 2014. The stock will trade EX dividend on September 12. The company paid a dividend of 50 cents per share on March 6, this year. In 2013, a dividend of $1 per share was paid on March 28, 2013.
Barita recovering slowly from Debt swap
 Profit at Barita Investments doubled for the nine months to June this year, compared to same period of previous year. Profit amounted to $156 million against $79 million but profit for the latest quarter was down from $99 million in 2013 to $63 million before tax. After tax, profit dropped to $51 million versus $99 million in 2013, a period when no tax was booked.
The big turnaround in the nine months figures, is due mainly to a huge hit the 2013 profits got when Barita entered into the debt swap arrangement, with government of Jamaica, in the March quarter of 2013. There was no such charge in 2014.
The bottom-line performance came from net interest income that declined from $327 million for the 9 months to June 2013, to $260 million in the 2014 period and from Non-interest income of $249 million, up from $205 million, excluding a loss on investments of $117 million in 2013.
For the quarter, net interest income amounted to $75 million, compared with $78 million in the June quarter of 2013 and non-interest income of $105 million versus $117 million in 2013. Fees and commission income rose, Rita Humphrey-Lewin stated in her comments on the results that the launch of a new unit trust scheme in April, contributed to fee income. Foreign exchange earnings while slightly up in the June quarter over that of 2013, is down to $108 million from $125 million in 2013. Dividend income fell as well, form $20 million for the nine months last year, to $10 million.
Gains also came as a result of trading opportunities in an improved international market, Humphreys-Lewin said, in addition, the depreciation of the Jamaican dollar against the three major international currencies returned $109 million in foreign exchange gains for the year to June, but that was lower than the $125 million enjoyed in 2013.
Administrative costs, fell 9 percent from $172 million in the 9 month period of last year, to $156 million this year, but was up from $39 million in the 2013 quarter to $56 million in 2014. Staff costs is up 9 percent in the June quarter as well as for the nine months to $179 million, for the year to June.
Earnings per share for the June quarter was 11 cents compared to 22 cents from the June 2013 quarter, Barita should end up with earnings per share around 46-50 cents for the 2014 fiscal year and looks like improving that in 2015 all things being equal.
Barita’s assets grew for the nine months to June to $13.5 billion from $13.3 billion last year, over the same period shareholders’ equity grew from $1.3 billion to $1.6 billion.
Big improvement in Berger’s Q1 numbers
 Revenues rose 10 percent, for Berger Paints Jamaica in the June quarter to $387 million, up from $353 million for June 2013. Loss after taxation, fell to only $372,000 from $3.16 million in 2013.
For the full of year to March this year, the company reported profit after corporation tax of $55 million, from revenues of $1.74 billion. IC Insider is forecasting earnings of 43 cents per share earnings, for the current year ending March 2015. Berger paid a dividend of 8 cents per share in July this year, based on the 2014 profit.
Cash and bank balances rose to $68 million at the end of June from $41 million in March and shareholders’ equity was $411 million.
20% revenue hike pumps up profit at Carreras
 In 2013, revenues at cigarette company, Carreras, plummeted from $3.1 billion in June 2012 quarter to just $2.155 billion, a sharp 30 percent drop. IC Insider in reporting on the company’s performance last year, stated “that is not all coming from the recently announced smoking ban.
Profit after tax fared even worse than the fall in revenues, dipping by 40 percent. The interesting development, is that gross margin improved to 100 percent from 90 percent, similar quarter in 2012 and 86.5 percent for all of the 2013 fiscal year. Price increase earlier this year (2013) clearly had a negative impact with the company’s customers, and seemed to have taken a big bite out of sales. A look at sales in 2012, showed a big jump in the last half of the year, coming into the March quarter this year (2013), suggesting that distributors where stocking up on the product, in anticipation of price increase and stopped stock piling once the price adjustment was implemented, as such the fall off in sales may not be as bad as it appears on the surface”.
The company’s first quarter results for 2014, show a marked improvement over 2013, sale have recovered by 20 percent over the poor June quarter, last year, to hit $2.59 billion. Volumes are clearly down but not as bad as they were last year. Gross profit climbed by 15.6 percent to $1.257 billion and profit after tax ended at $589 million from $485 million, in 2013. Gross profit margin fell to 94 percent in the latest quarter from 100 percent last year.
The tax rate has been reduced to 25 percent thus helping more than normal with the after tax profit gain. Distribution cost fell from $207 million to $185 million but administrative cost was up, from $320 million to $372 million.
Carreras had cash funds of $3.3 billion at the end of June this year and tax recoverable of $870 million. They are also to recover interest on the taxes the government is to refund them for. The latest results points to earnings in excess of $5 per share for the current financial year.