 Trinidad Cement’s June quarter profit before tax bettered by a small amount the results of last year, coming in at $26.5 million versus $23.4 million, but after accounting for a non-recurring charge of nearly $26 million and lower finance cost.
Profit after tax due to shareholders of the company, amounted to $19 million for the quarter and in 2013 $46 million, helped by a tax credit of $33 million and for the year to June, the group reports profit after tax of $30 million versus $70 million in 2013. The non-recurring charge arose from a provision for retroactive pay increases and a charge of $16 million, mainly legal expenses incurred on the aborted debt refinancing exercise initiated earlier in the year. Had these charges not occurred, profit before tax would have been $52 million in the latest quarter. IC Insider is forecasting earnings of 45 cents per share for the full year.
“Key markets of Trinidad, Guyana, and Suriname remain buoyant whilst the others have stabilized and accordingly, the Group expects better second half results from operations, as the annual plant stops at the two largest plants have already taken place in the first half,” management, in its comments of the outlook stated.
Revenue in the quarter grew 9 percent to $512 million and for the 6 months from $994 million to $1.07 billion or 8 percent. Operating profit came out at $132 million in the June quarter, versus $114 million in 2013 and for the half year $232 million for 2014 versus $233 million in 2013. Finance cost slipped from $58 million in the June 2013 quarter, to $47 million, due to minimal devaluation in Jamaica compared to 2013. For the six months finance cost fell to $97.5 million from $123 million in 2013.
For the half year, Trinidad Cement generated cash flow of $144 million before loan repayment, up from $90 million last year. After loan repayment and the funding of investment activities, the group was left with $77 million of cash funds, up from $52 million at the end of June 2013. According to the 2013 audited accounts, the group was committed to repay $179 million during 2014 but that would still leave them with total loans of $1.77 billion and equity at the end of June of $573 million, therefore remaining in a highly over leverage position.
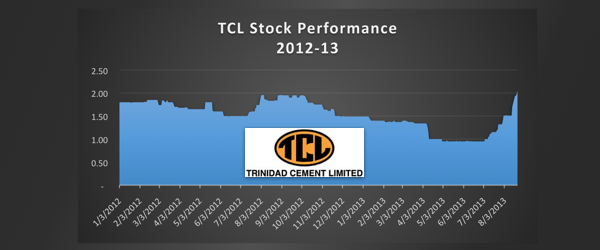
Investment in the stock is not without risk, with the heavy debt, in addition, the shareholders’ squabble to change directors, can create negatives for the group as well as it could be positive when everything is resolved. No one really knows how that will pan out. Based on the profit out turn and the likelihood for increased profits to come, IC Insider still accords the stock a BUY RATED status.
Trinidad Cement making strides but debt a bother
August 14, 2014 by