 Pulse’s directors put before the annual general meeting held on Tuesday at the company’s Villa Ronai complex a resolution to increase the capital of the company but agreed to withdraw it after a number of shareholders suggested that it should be postponed.
The resolution was incorporated into the agenda after the annual reports were printed and was asking shareholders to vote to increase the authorised capital from 336,835,181 shares to 450 million shares without par value. Shareholders argued that the request was being presented without any explanation for the increase. In addition, based on the points put forth by the directors that the expectation is to raise funds to help finance the property expansion with the building of townhouses, shareholders were of the view that thye needed to be presented with a plan for the development and its funding. Such plans shareholders felt should include some debt financing that could include preference shares or bonds issued to the public.
Pulse released interim results to December showing profits of $131.9 million for the six months up by 33 percent from the $99 million reported in 2014. For the December quarter profit amounted to 51.6 million or 26 percent higher than the $41 million in 2014.
Operating revenues rose 25 percent to $65 million from $63 million for the quarter and percent for the half year to $151 million from $132 million in 2014.
The net profit results include fair value appreciation on investment property of $25.4 million for the latest quarter versus $20.7 million in 2014 and $51.8 million for the six months to December 2015 and $42.3 million in 2014.
Earnings per share for the quarter came in at 19 cents and 49 cents for the six months and should reach $1 per share for the full year.
Pulse pushes back capital increase
Margaritaville Turks profit up 86%
 The Turks and Caicos based Margaritaville Turks, a Jamaica Stock Exchange US dollar market listed company, reported a big 86 percent jump in profits of US$518,134 in the six months to November last year versus $278,508 in the prior year.
The improved profit came from revenues that climbed 11 percent to $3.376 million. For the quarter ending November, the company reported improved results with net profit of $247,253, a whopping increase of 728 percent over the profit of $33,611 for the same quarter in 2014. Sales revenue for the quarter rose a very strong 24.7 percent to $1.65 million, compared to $1.32 million in 2014. Gross profit grew by 25 percent, slightly faster than sales revenue and for the six months by 10.7 percent.
Administrative expenses rose by 5.3 percent to hit $1.68 million for the six months and for the quarter to November to $829,364 for an increase of 8.7 percent. Management fees fell from $212,614 in 204 for the six months to $125,000 and for the quarter from $92,628 to $62,500. Depreciation charge was essentially flat at $123,748 for the six months and $62,444 for the quarter.
The company generated earnings per share of 0.77 US cents to November and 0.37 US cents for the quarter. IC Insider expects earnings for the full year to May to be around 2 US cents per share. This puts the PE of the stock at a low 5 times current year’s earnings.
Cash flows from operating activities amounted to $642,173 for six months versus $399,202 in 2014 before increase in related party receivables of $1.24 million and $685,495 in 2014 and ended with cash of $24,977. The equity capital stood at of $4.3 million and the company had no borrowed funds.
Massy’s profit jumps 32% in Q4
 The Trinidad based conglomerate Massy Holdings reported improved 2015 results with net profit of $252 million attributable to shareholders for the quarter ending September, up a strong 32 percent over 2014.
For the year, profit rose by a much slower 15 percent to $638 million. Pretax profits grew at a slower pace of 21.5 percent for the September quarter and 10.4 percent for the full year.
The group had a poor June quarter with 24 percent lower profits of $175 million than in 2014, before cost of rebranding the group. The group operates in 6 segments but only the automotive and industrial segment showed any meaningful increase in profit, moving from $230 million in 2014 to $285 million, the others were virtually flat, with insurance and other investments suffering declines.
For the full year ongoing profit grew much less than the above stated rate as 2014 incurred $58 million in rebranding cost with virtually none in 2015. Massy generated earnings per share of $2.58 for the September quarter and $6.53 for year, up from $5.69 in 2014. IC Insider expects earnings for the full year to be around $7.50 per share. Falling oil prices on the world market could complicate the outlook for Massy as the Trinidad economy now in recession, could get worse as government put in place measures that will trim demand. The company’s other regional businesses with revenues of just under 50 percent could offset some of any possible decline in Trinidad.
Sales revenue for the quarter rose 8.3 percent to $2.98 billion, compared to $2.75 billion in 2014 and by 11.6 percent for the year to $11.94 billion.
Cash flows from operating activities amounted to $1.14 billion for the year versus $1.04 billion in 2014. The group has assets of $10.4 billion and equity of $4.4 billion and borrowings of $2.17 billion.
Massy Holdings plans expansion into new areas of methanol and DME plants being constructed. Methanol is used as a raw material in the making of traditional petrochemicals, including formaldehyde and acetic acid. DME (Dimethyl Ether) is a form of liquefied gas that can be made from natural gas or from other raw materials such as coal or biomass.
Shareholder pumps millions into KLE
KLE closed at a 52 weeks’ high in closing at $1.83 on Tuesday.
KLE Group operators of the Famous nightclub and Usain Bolt Tracks & Records received US$650,000 loan from its largest shareholder Joe Bogdanovich this financial year, IC Insider understands as the music promoter deepens his interest in the struggling junior market entertainment company.
KLE was listed in late 2012 after raising $90 million in an initial public offering.
Bogdanovich acquired 23 per cent of KLE Group at market value between $0.90 and $1 on the Jamaica Stock Exchange in 2014 when two directors exited the company. The loan listed on the books as other loan at J$73.59 million, represents more than four-fifths of its total loans payable at $87.6 million.
The loan propped up the cash position at the company to record cashflow and equivalents at $30 million in December 2014 but it now returned to a cashflow deficit of $6.9 million at September 2025. The loan was in part utilised to pay down debt, particularly trade payables but left very costly statutory debts at higher levels than before at $21 million, as well as credit card debt at $11 million, with the latter increasing from $2.5 million in 2014.
 The company, however, continues to operate with huge negative working capital and negative equity capital of $8 million with accumulated deficit at $130 million.
On the positive side, the company made a rare profit of $2.6 million or 2.8 cents per share from flat revenues of $48.3 million, for the three months ending September 2015 which reversed the $8 million loss for the corresponding quarter a year earlier. Over the nine months, it however, recorded a $32 million loss. The quarterly profit came as the company cut administrative and interest cost sharply by $20 million, partially by limiting the number of days its operates the Portmore based Famous Nightclub. If the bottom-line trend were to continue, the struggling group could end up with profit of $12 million in a full year, and although small, would represent a major turnaround for a company that has been bleeding badly for the past 3.5 years, with losses amounting $139 million during that period.
The group continued its restructuring exercise from 2014 with base operating costs reduced to reflect the leaner organization. Further changes will be made to ensure total alignment with the company’s portfolio and its strategic direction. The Famous operating model was changed in August from a weekly 3 night per week club to a promoter model which saw the location being marketed to promoters as a venue. This has allowed for significant reduction in operating costs with a major shift from fixed to variable expenses,” stated management in the financials adding that it continues plans to franchise its Tracks & Records restaurants globally.
Since the release of the results were released on the December 2, last year, the stock has climbed from 73 cents to trade at $1.87 after bottoming at 43 cents in October.
Strong profit gains at Broilers
 Chicken meat and feed processors, Jamaica Broilers recorded an impressive 297 percent increase in net profits attributable to shareholders for the quarter ending October 2015 amounting to $408 million and earnings per share of 33.8 cents according to the interim financial results.
For the six months, profit rose a very strong 242 percent to hit $740 million with earnings per share of 61 cents. IC Insider forecast earnings for the full year at $1.30 and $1.70 for the 2017 fiscal year. Broilers generated $1.76 billion in gross cash flows from operating activities during the half year.
The stock last traded on The Jamaica Stock Exchange at $10 for a PE of 7.7 times this year’s earnings, leaving room for moderate growth based on 2015/16 results and current valuation of stocks.
Sales revenue for the October quarter rose 6 percent to $9.17 billion, compared to $8.68 billion in 2014 and by 9 percent for the half year to $18.1 billion. Gross profit for the quarter increased 30 percent to $2.28 billion, from $1.75 billion of the corresponding quarter last year and grew by 31 percent for the six months to $4.56 billion.
The “US Operations performed as expected with respect to the sale of our main product –fertile eggs for the broiler industry. The year to date segment results amounted to $538 million. Our presence in the markets remains strong, with a broad customer base and we are seeing the benefits of the US dollar hard currency earnings. We expect steady growth in other product lines in this segment. We are recording increased sale volumes in poultry and feed products, consequent on targeted marketing strategies,” the company’s management stated in their report to shareholders.
“In the Other Caribbean Operations, Haiti Broilers SA has increased production and sale of table eggs to 14% of the market, compared to 12% at the end of the second quarter last year. The positive effect of this volume growth has however been neutralized by significant increases in operating costs due to the continuing depreciation of the Haitian Gourde against the US dollars”, the management report went on to state.
 Cost overall climbed with some increasing much faster than revenues. Distribution and selling cost rose in line with revenues with an increase of 9 percent in the quarter and year to date with cost of $260 million in the quarter and $508 million for the half year. Administrative costs, tripled the growth in revenues in the October quarter to be up by 19 percent to $$1.4 billion and increased by 18 percent for the six months to $2.9 billion. Finance cost fell in the quarter and grew slightly or the half year while interest income rose strongly.
Cash and short-term investments totalled $2.36 billion, Current Assets amounted to $11.4 billion and current liabilities at $6.8 billion, shareholders’ equity stands at $12 billion and borrowings at $6.3 billion, down from $7 million in 2014.
Cargo Handlers growth slows
 Cargo Handlers profit for the year to September was barely higher than for that of 2014 at $136 million versus $132 million but the company had some one-off expenses amounting to $16 million. Revenues climbed to $252 million from $236 million in 2014.
The final quarter of the year saw lower revenues of $67 million, down from $79 million in the September 2014 quarter while profit fell 40 percent to $29 million from $48 million in 2014. Cargo Handlers recorded earnings per share of $3.63 versus $3.52 in 2014.
Going forward, the tax free holiday the company enjoyed from December 2010, ends in November this year and moves to 12.5 percent for the next 5 years. This will dent profits a bit, added to that, the company made $6 million in foreign exchange gains in 2015, that looks uncertain going forward with the adjustment in the value of the Jamaican dollar that now seems appropriately valued, but for likely moderate movements in 2016.
Unless there is a dramatic change in revenues, profit after tax for 2016 should grow marginally to around $145 million or $3.87 per share.
The company ended the year with $151 million in cash included in current assets of $203 million and only $15 million in current liabilities. Equity is $245 million with virtually no interest bearing debt. The stock which is listed on the junior market of the Jamaica Stock Exchange last traded at $37.50. Two dividends amounting to $2.35 per share were paid during the year.
First Citizens flat 2015 numbers
 As Trinidad and Tobago struggled with recession in 2015 profit for the year ended September 2015 resulted in a marginal increase from TT$627 million in 2014 to TT$630 million for First Citizens Bank, a Trinidadian based and Trinidad Stock Exchange listed bank.
The performance emanated from revenues of $1.76 billion net of $282 million in interest cost, compared to $1.68 billion net of interest cost of $315 million in 2014. For the September quarter profit fell to $148 million from $157 million reported for the June quarter.
While interest income was marginally down to $1.45 billion from $1.47 billion for the 12 months, fees and commissions rose sharply by 28 percent to $415 million from $360 million, gains on sale of financial assets, netted only $27 million versus $66 million in 2014 while foreign exchange gains, rose to $12 million from $76 million.
Driven mainly by a 19.5 percent increase in the wage bill that hit $425 million administrative expenses rose 13.8 percent to $594 million from $522 million and other operating expenses were flat at $390 million as technical and professional fell to $21 million from $38. Loan losses fell to $6 million from $13 million in 2014 but taxation climbed to $160 million from $146 million thus reducing a 4.7 percent increase in pretax profit to a virtually flat net results for the year, with earnings per share of $2.51.
Investment assets amounted to $12.3 billion up from $10.4 billion in 2014 while loans grew to by $1.6 billion in the final quarter to $17.3 billion and is up from $14.9 billion at September 2014.
With Trinidad now in recession and the price of oil under US$40 per barrel, institutions such as banks could see their income and profit under pressure in 2016 as demand for loans remain weak. The stock last traded at $35 on the Trinidad Stock Exchange with a PE of 14 and don’t seem to have much room for growth in the months ahead.
JSE stock up 887% could end higher
 The Jamaica Stocks Exchange stock rocketed from $1.57 to a record $15.50 topping the market as the best performing stock over 52 weeks with gains of 887 percent. The JSE benefitted from a big jump in profits from $8 million in 2014 to $139 million in nine months to September this year, as revenues jumped from $242 million in 2014 to $521 million.
For the quarter, profit amounts to $37 million up from $11 million in 2014, from operating revenues of $157 million versus $89 million in 2014. In addition to operating revenues, the JSE earned $16 million from investment income in the latest quarter, compared to $8 million in the September 2014 quarter and $34 million in the nine months in both years.
Earlier in the year, IC Insider stated, “the stock remains IC Insider BUY RATED and is now available at $3.50 which it last traded at, but won’t remain that way forever and investors should be buying this one for big long-term gains,” since then the stock has shot up to $15.50 for a gain of 933 percent for the year.
 For the September quarter, cost rose from $90 million to $109 million due mainly to staff cost jumping b $12 million. For the nine months, cost rose from $273 million to $340 million with staff cost accounting for $20 million of the increase and securities commission fees jumping to $37 million from $10 million in 2014.
The exchange has cash and investments of $448 million with a working capital ratio of 2.4:1 and equity of $624 million, there is no borrowed debt on the books.
Factors that investors should be considering looking forward which will be critical to the fortunes of the stock exchange are the levels of trading that could point them to future income and profit. Up to December 4, this year, the JSE traded $8.4 billion in normal trades compared to $3.7 billion in December 2014, in the September quarter, trading amounted to $8.68 billion up from $3.74 billion in the June 2015 quarter and $5.15 billion in September 2014. The increase in the 4th quarter stock trading activity to date, is just below the 3th quarter level, in addition there will be a full quarterly income from repo business.
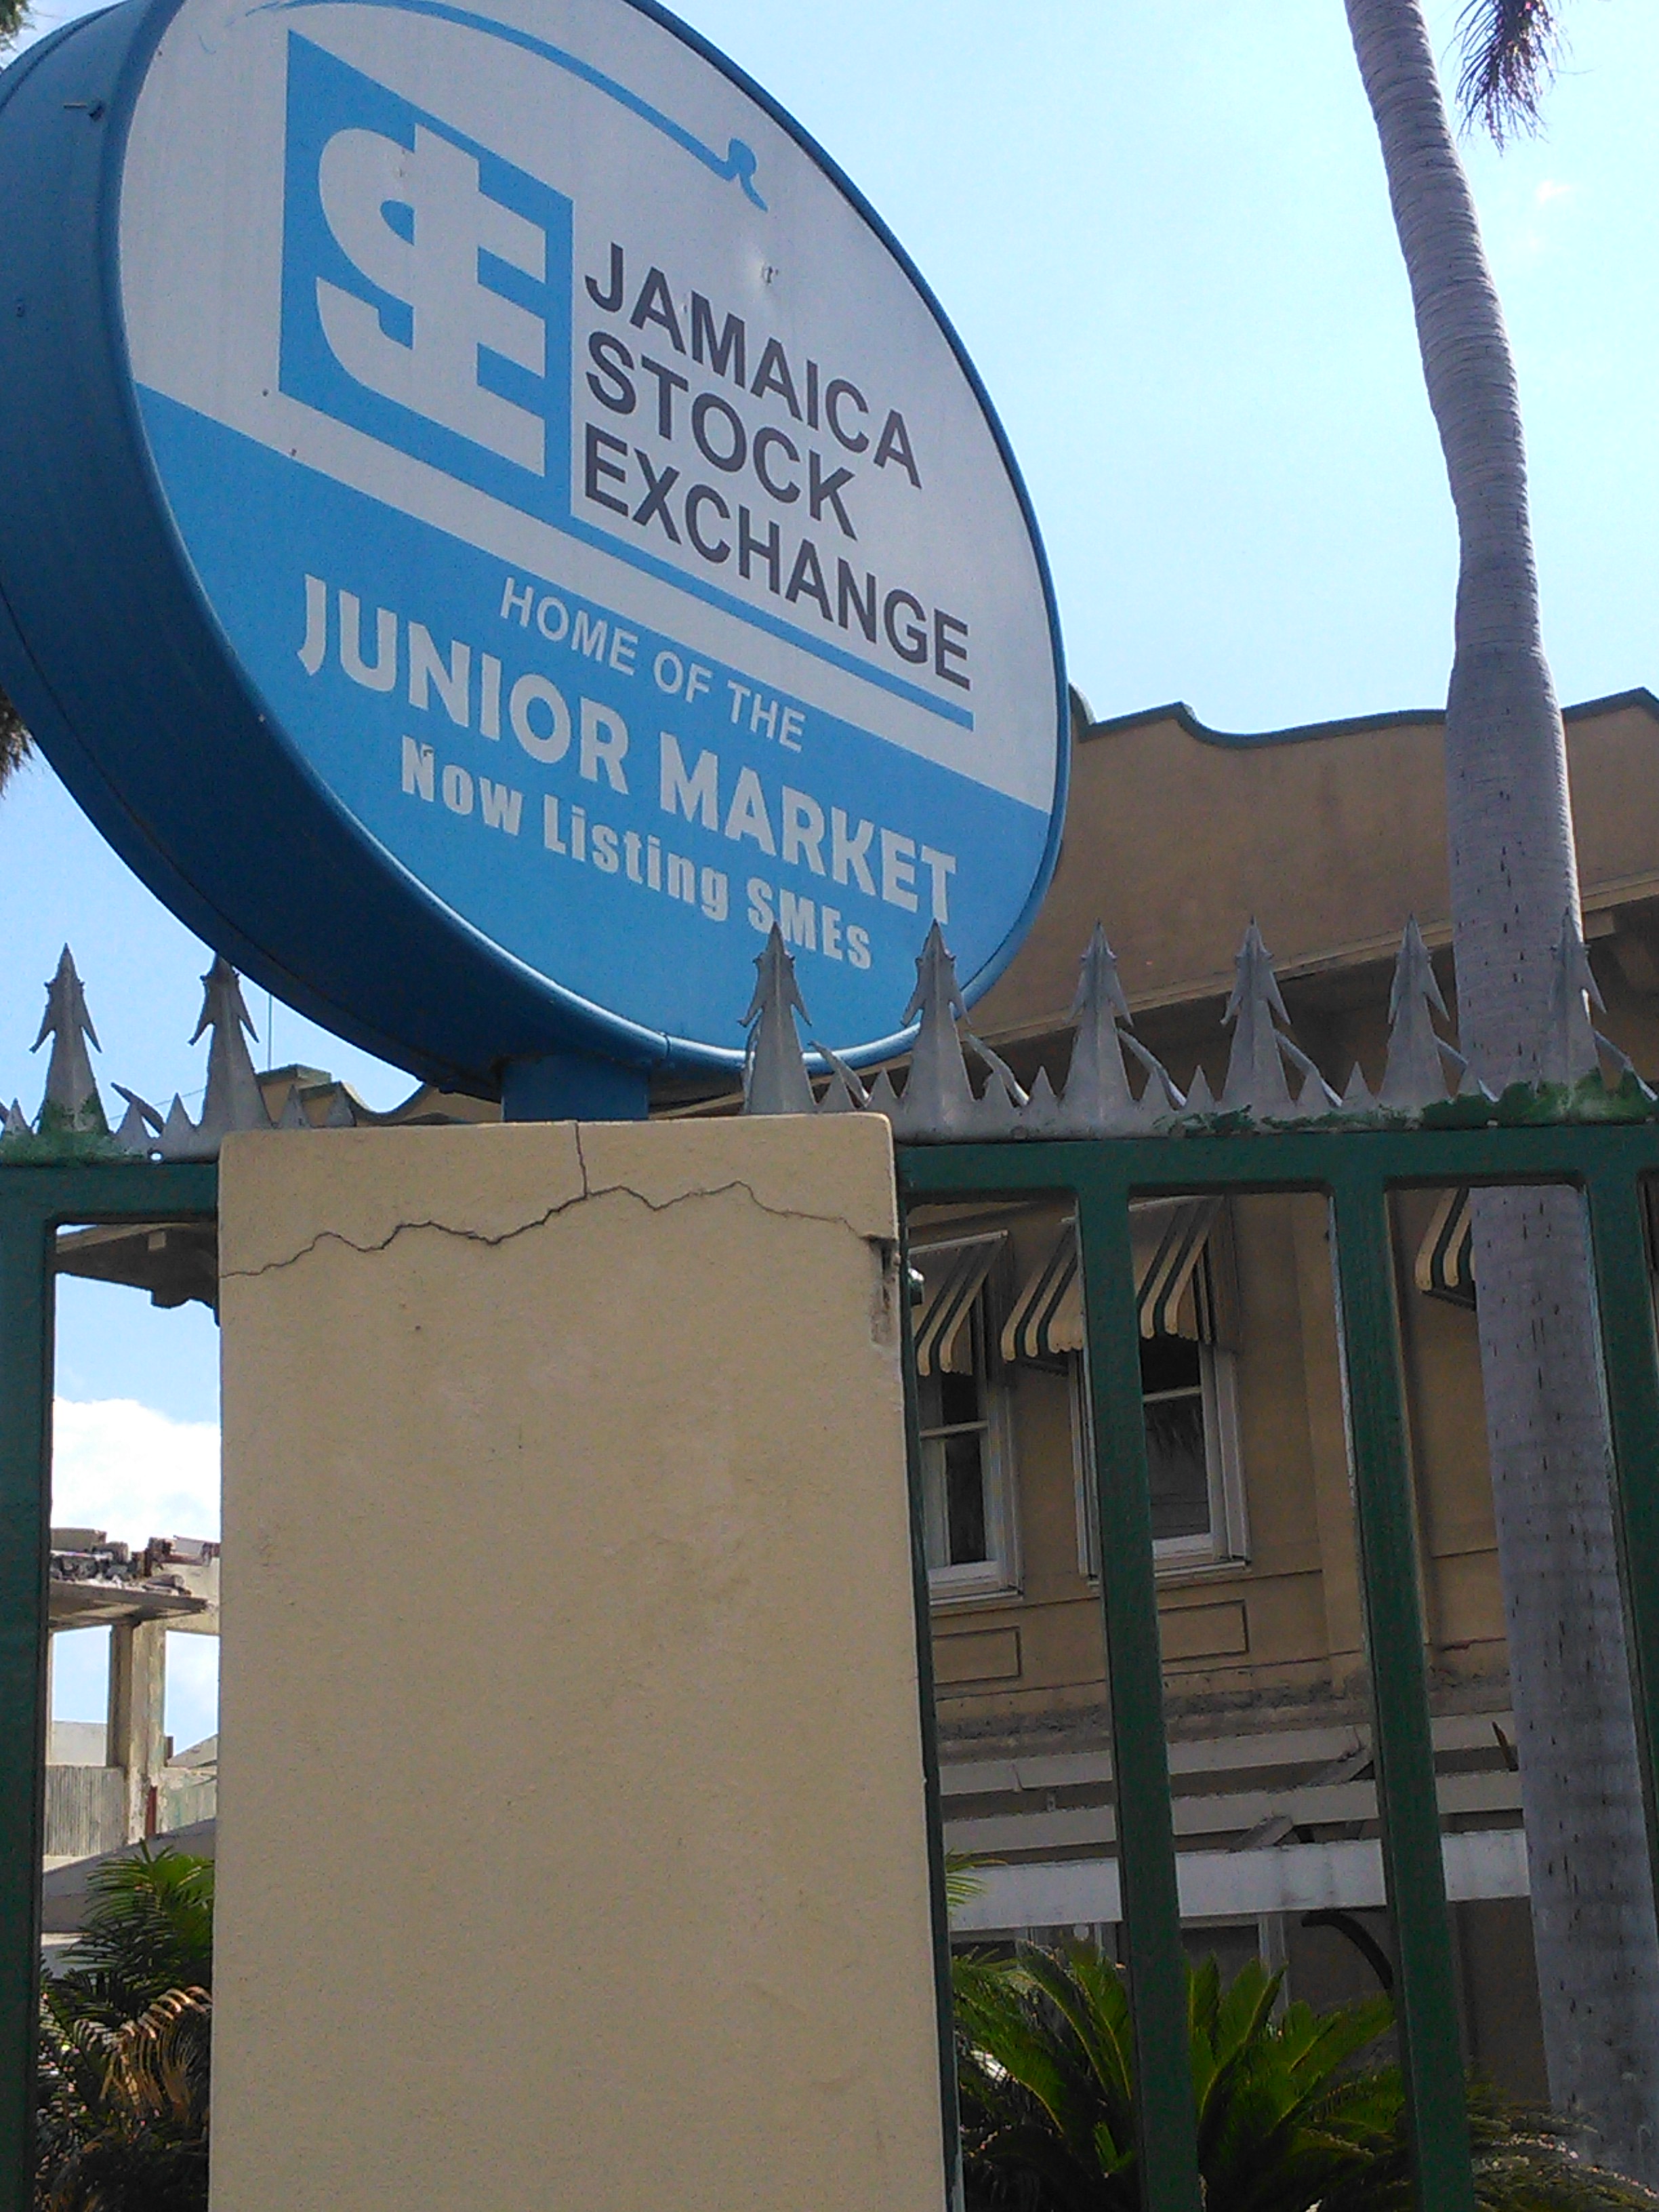 In the March quarter 2015, a total of $4.9 billion was involved in trading up from $3.8 billion in March 2014. Both the December and the March quarters in 2015 have a few one off type trades, regardless the trend is pretty clear pointing to the possibility of a strong 2016. The last two quarters suggest that trading levels in dollar terms could be up around 40 percent and it could be more. That would mean a sharp increase in revenues for the exchange in addition the managing of the repo business will provide added income for the entire year compared with two months in the September quarter and 5 months for the year to December.
Back in 2004, the market traded $28 billion in regular trading activity when the Jamaican dollar was trading around $62 to the US dollar with trading in 2005 being slightly behind at $26 billion. Trading would need to get to $51-55 billion for a year to match trading levels back in 2004 and 2005.
Profit should close out the year on a high with monetary trading levels set to exceed that of the third quarter and well ahead of the fourth quarter of 2014. IC Insider is forecasting earnings of $1.40 for the 2015 not factoring the trade that could flow from the Heineken buyout of the minority shares in Desnoes and Geddes.
Profit break out for Scotia in 2016?
Scotia Group Montego Bay.
Net interest income after impairment losses for the year was $22.9 billion, marginally above 2014 resulting in a reduction in the impairment losses on loans by $241 million or 15.0 percent, this is “due to enhanced adjudication, monitoring and collection efforts. The Group continues to report strong growth in loan volumes during the year, particularly our Residential Mortgages, Consumer, Small Business and Commercial portfolios; however net interest margins continue to decline due to lower market interest rates and the competitive environment”, Scotia stated in their media release accompanying the financials.
Jackie Sharp – CEO Scotia Group
Total assets increased year over year by $25.9 billion or 6.4 percent to $433 billion as at October 2015 due primarily to increases of $8.8 billion or 6 percent in Loans to $154.5 billion, increase in investment and pledged assets and $9.2 billion in other assets
The group reported earnings per share of $3.19 for the year and $1.26 for the last quarter and seems poised to generate earnings around $4 for the 2016 fiscal year.
Caribbean Flavour(ing) future profits
 “With the price of the stock, trading at $2.55 for a PE of just over 3 and 2.3 based on IC Insider’s forecast, (is) indicative of much upside potential,” was how Caribbean Flavours was assessed back in August this year, as the stock was elevated to the BUY RATED ranking after the company released its full year results to June.
In the June posting, IC Insider stated, “The company seems poised to hit earnings of 65 cents per share, for the June 2015 financial year, making it attractive for some short-term gains, with the current price of $2.09, at a PE ratio of 3 times earnings.”
Focusing on the end results of Caribbean Flavours & Fragrances for the year to June 2015 with increased profit of 22 percent over 2014 would lead one to look elsewhere, but that would be a big error. For while the nine months to March showed profit down marginally to $39 million from $40 million, profit for the March quarter was up 20 percent over March 2014 quarter, the June quarter increased by 143 percent to $18.77 million from just $7.6 million for June 2014.
The company followed up the improved results for the March and June quarters, with another quarter of strong performance to September, with a 51.3 percent increase in net profit to $20.36 million over the $13.46 million recorded for the similar period in 2014. The improved profit flowed from sales for the quarter jumping 38.20 percent to $87.46 million, compared to the $63.29 million recorded for the same period in 2014.
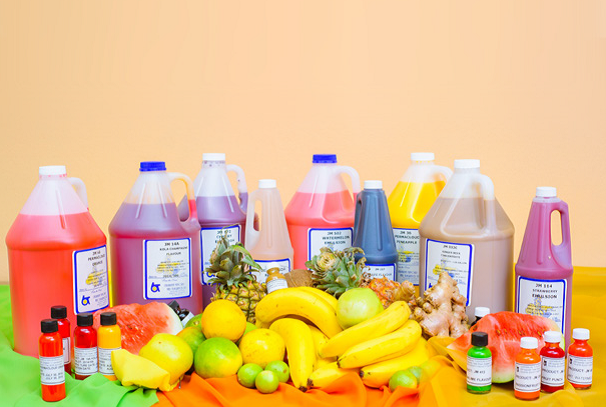
Caribbean Flavours’ produce with ingredients – the stock closed at a new high.
“The gross profit showed an increase of 28.91 percent moving from $25.487 million to $32.856 million as per our first quarter’s performance. The Company will continue to refine and improve our purchasing strategy in order to extract the necessary efficiencies and improve our cost of sales and gross profit.
The company continues to manage its administrative and general expenses within budget and compared to the 2014 quarter, there was only a 4.4 percent increase,” the report went on to state.
The future looks much brighter than the past year, for the company that manufactures and distributes flavours mainly for the beverage, baking and confectionery industries and also sells food colouring and fragrances. In responding to questions posed at the annual general meeting held on Wednesday 25 of November, directors indicated that the strong performance enjoyed in the September quarter continues into the December quarter.
“We have hardly scratched the surface of the potential market” Derrick Cotterell indicated, “we have moved into the Dominican Republic and Canada where there is much potential for growth and with renewed efforts and products the locally Jamaican market as well”. Cotterell stated that they have increased research into new products such as fragrances and this has opened up new opportunities for them. Trinidad, Cuba and Haiti are countries with potential for growth, they indicated but Haiti is said to be a difficult market to break into but they have contacts there that should make it possible. In addition to the focus on research and developments for new products and new customers the company said they were able to source some of its raw material more cheaply than before.
According to the company’s board, in their comments on the 2015 annual results “the economic environment has allowed the company to grow its revenues and profits by securing new markets for fragrances and increasing the volume of sales of flavours to existing and new customers in foreign markets. Based on the outlook for the coming year, it is expected that the company will continue to improve its profits whilst increasing its market share in the domestic and overseas markets”.
IC Insider projects profits for 2016 at $99 million or $1.10 per share with increased sales and improving profit margins and $1.50 for the 2017 fiscal year. Company is free of interest bearing debt and has net current assets of $221 million including cashfunds of $103 million.