Carib Producers now out of ICTOP10


In another week with investors’ attention split between the existing listings and two public stock issues on the market, the Main Market fell and the Junior Market rose marginally with the ICTOP10 ending with three stocks rising in the Junior Market listing while 5 declined. In the Main Market listing 5 stocks rose and three declined with Caribbean Producers falling from the All JSE ICTop10.

In the Junior Market ICTOP10, Dolphin Cove rebounded sharply from its recent fall, with a 9 percent climb during the week to $18.50 and AMG Packaging rose 4 percent to $2.90.
Kintyre Holdings fell 18 percent to 33 cents, Express Catering declined 10 percent to $2.60 and Dolla Financial lost 5 percent to close the week at $2.75.
In the Main Market ICTOP10, QWI Investments rose 6 percent to 82 cents and Jamaica Broilers popped 5 percent to $37, while VM Investments fell by 7 percent to close at $2.19.
The All JSE ICTOP10, compiled from all listed ordinary stocks on the Jamaica Stock Exchange ended the week with Caribbean Producers falling out and replaced by another Montego Bay company, Express Catering.
There is one change to the Junior Market ICTOP10 and none in Main Market ICTOP10, with the Junior Market Iron Rock Insurance returning as Dolphin Cove drops out with the B recovery continuing for the stock price following the sharp fall two weeks ago.
The average PE for the JSE Main Market ICTOP 10 sits at just 5.7, well below the market average of 15 and the Junior Market TOP10 stands at 7.6, more than half of the market, with an average of 13.9.
Based on the earnings estimates for 2024, the Main Market ICTOP10 is projected to gain an average of 251 percent by May 2025, providing better values than the Junior Market, that is projected to achieve a 189 percent increase for the same period.
In the Main Market ICTOP 10, there are 19 stocks with the highest values representing 37 percent of the Main Market, with PEs between 15 to 44, with an average of 21 and a PE of 20 for the top half of the market with the highest values.
In the Junior Market IC TOP10, 13 stocks or 28 percent of the market have PEs ranging from 15 to 32 with an average of 19 and a PE of 18 for half of the market with the highest PEs.
ICTOP10 focuses on likely yearly winners. The list includes some of the best companies in the market and non-blue chip stocks and in some cases weaker companies that may be oversold and therefore end up on the list. ICInsider.com ranks stocks based on projected earnings, allowing investors to focus on the most undervalued stocks and helping to remove emotions in selecting stocks for investments that often result in costly mistakes.

IC TOP10 stocks will likely deliver the best returns on or around May 2025 and are ranked in order of potential gains, computed using projected earnings for the current fiscal year. Expected values will change as stock prices fluctuate, resulting in weekly movements in and out of the lists. Revisions to earnings are ongoing, based on receipt of new information.
Persons who compiled this report may have an interest in securities commented on in this report.
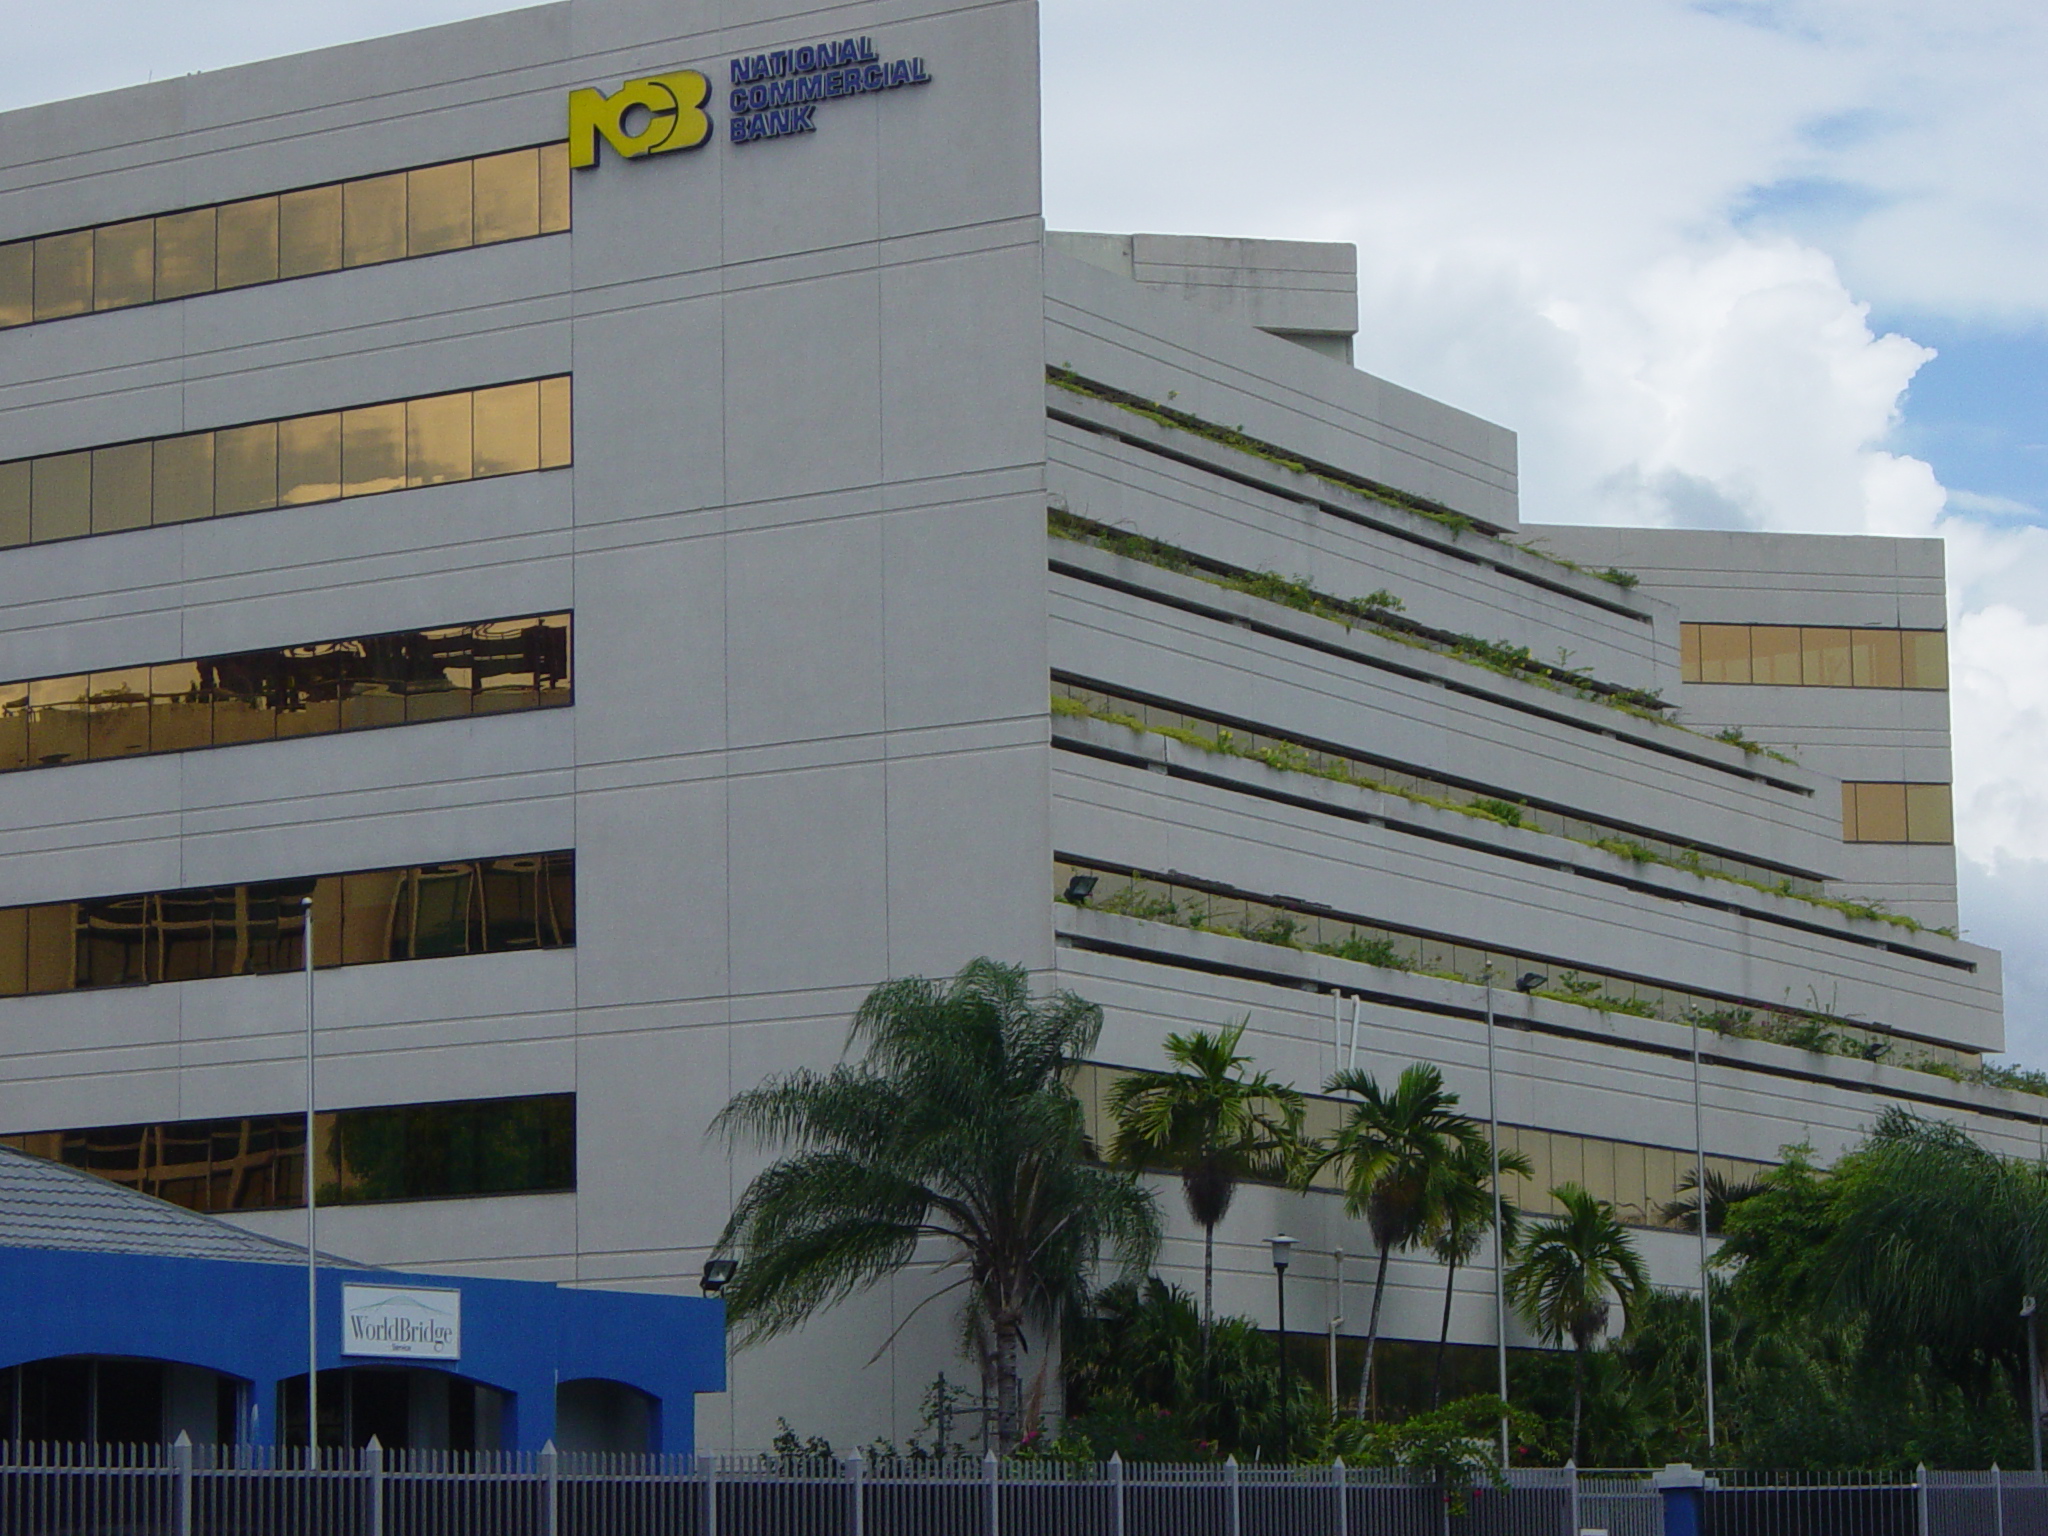
NCB 2014 profit trumps 2013 by a KM

NCB hqtrNational Commercial Bank net profit for 2014 hit $11.6 billion, a big jump from the NDX affected $8.58 billion in 2013. Earnings per share for the year ended at $4.73 just below IC Insider forecast of $4.80.
The 2013 profit was negatively affected by a huge $1.5 billion charge, from losses picked up when they exchanged high yielding government bonds for lower yielding ones and $680 million written off relating to the attempt to list on the New York Stock Exchange. The group is reporting net profit of $2.87 billion, for the September quarter compared to $1.8 billion in 2013, the latter was affected by a number of one off charges.
The 2013 full year was also negatively impacted by a $281 million hit from receivership expenses, an increase over the amount spent in 2012 of $172 million and a healthy rise in Technical, consultancy and professional fees of $1.09 billion compared with $846 million in 2012.
This year results benefited from a few one off items as well. Gain on acquisition of subsidiary contributed $301 million and gain on sales of shares in Kingston Wharves added $349 million but this is in lieu booking their share of profits for the quarter had they not sold. The group suffered a loss of $200 million on securities impairment and critically, although loan loss provision is up $200 million, the large increase in the final quarter is $700 million more than at the same time in 2013. For the full year, loan losses amount to $2.2 billion versus $2.1 billion for the previous year.
Salaries allowances and benefits cost was down in the quarter to $2.6 billion from $2.9 in the similar quarter, and for the year to $11.5 billion versus $11.2 billion in 2013. Other operating cost was up to $10.4 billion for the full year, from $9.4 billion in 2013 and for the quarter $3.1 billion from $2.8 billion.
Growth| For 2014, loans grew pretty strongly by 12 percent, moving from $143.6 billion to $157 billion and customer deposits of $202 billion, increased by $23.8 billion, or 13 percent, resulting in net interest income being steady, in the September quarter, for both years, as well as in the June quarter at roughly $6 billion each. Net interest income was up $1 billion for the year over 2013 to reach $24.66 billion from $23.56 billion. Fees and commission income moved up to $10.6 billion net, compared to $9.7 billion in 2013. Premium income grew to $7 billion from $5 billion in 2013. Gains on sale of debt securities and foreign exchange trading gains jumped to $2.6 billion versus $1 billion in 2013.
Segment| Segment results were mixed with strong increases in some, while other areas fell below the 2013 performance. Retail & SME, reported improved profits for 2014 of $1.56 billion versus $793 million in 2013. Payment Services climbed down from $2.1 billion to $1.57 billion in 2014, Corporate Banking ended 2014 with $500 million versus $850 million previously, Treasury & Correspondent Banking jumped from $1.87 billion in 2013 to $3.7 billion in the latest year. Wealth, Asset Management and Investment Banking moved down from $3.88 billion to $3.6 billion, Life Insurance and Pension Fund Management climbed from $2.17 billion to $2.9 billion and General Insurance income of $557 million in 2013 jumped to $1.28 billion.
NCB hiked their final dividend for the year to 96 cents per shares. IC Insider’s forecast for the 2015 earnings is $5.75 per share and with the current price at just over $18 per share the stock is severely undervalued with significant upside potential.