Berger Paints Jamaica enjoyed a 25 percent jump in after tax profit, for the December quarter and 12 percent for the nine months to December, thanks to lower tax rate as profit before tax was up 16 percent and only 4.5 percent respectively.
 Sales revenues were up 9 percent in the quarter, to $679 million and 6 percent for the nine months to reach $1.496 billion. Profit before tax, amounted to $84 million for the quarter, up from $72.5 million and $95.3 million versus $91 million.
After providing $21 million for tax, net profit for the quarter ended at $63 million or 30 cents per share, and for the nine months, earnings ended at $71.5 million or 33 cents per share.
At year end, cash ended at $48 million compared $41 million at the end of March, but current assets climbed to $891 million from $674 million at March and $792 million at the end of 2013. Current liabilities rose as well, to $422 million from $390 million at the end of 2013 and $290 at March last year.
Going forward, Berger should benefit from the lower price for oil on the world market as a major input into producing paints is oil based products. Profits for the year to March, should end around 34 cents. Investors should be seeing a large portion of the profit being paid out as dividend, with the stock price now at $1.56, the yield could exceed 10 percent. IC Insider forecast 54 cents per share for the 2016 fiscal year.
Berger Paints Jamaica is listed on the Jamaica Stock Exchange.
25% jump in Berger Jamaica profit
$46 PS for Eppley’s dividend
 Eppley Limited will be making a dividend of $37.19 per share payable on March 17, 2015 to ordinary shareholders on record as of March 10, 2015.
The stock will trade X-dividend on March 6. The payment will bring the total dividend out of profit of 2014 of $46.19 providing a dividend yield of 12.15 percent per share based on the stock price of $380. The total dividend paid out of profit for the year, amounts to $36.77 million.
The company paid a dividend of $9 per share on September 2, 2014. Eppley reported profit of $51 million or $64.19 per share for 2014, an increase over the $39 million for 2013.
Eppley’s Profit up 31%, Q4 flat
Eppley is reporting a miniscule increase in profit after tax to reach $11.4 million for the December quarter and a 31 percent increase, to $51 million for 2014.
 The company that mainly does insurance premium financing, generated a 62 percent increase in revenues for the quarter to reach $43.8 million and a 68 percent increase for the year, landed revenues at $150.7 million.
Expenses were climbing much faster than income, with interest cost climbing 196 percent in the quarter, hitting $16.9 million and 194 percent increase for the year to end at $48.7 million. The increase in interest cost squeezed margins on lending sharply as new funding received in the last quarter was only partially used to generate high yields. Administrative cost climbed 51 percent in the quarter and 50 percent for the year.
At year end, cash funds not fully deployed amounted to $519 million up from $161 million at the end of 2013. Borrowing stood at $1.08 billion and equity at $343 million. A significant part of borrowings is quasi equity, in the form of preference shares, moving borrowings from $395 million at the end of September to what it ended at, in December. Amounts lent out totalled $843 million, up from $595 million in 2013 and $689 million at the end of September.
With the increased funding, Eppley should be able to increase business in 2015 and with that profits, as such earnings could be in the range of $100 per share for 2015. Earnings per share for 2014 ended at $64.19.
The stock is thinly traded and listed on the Jamaica Stock Exchange junior market and last traded at $380.
$450m rights issue for Sterling
 Sterling Investments Limited is setting to raise around J$450 million by way of a renounceable rights issue by April this year. The opening date of the issue will be March 18, with closure set for April 8.
Before the issue, the directors are planning to get approval for a stock split which IC Insider understands is likely to be 10 new shares for each one now existing. This means that the right issue price should be under $13.40, the price that the stock has traded at recently, assuming the split takes effect at the above ratio.
The company has called an extraordinary general meeting of shareholders for February 21, 2015 in St. Lucia to consider increasing the share capital, approving the stock split, authorizing the Directors to implement a Rights Issue and to carry out all steps and documents needed to give effect to the stock split and to implement the Right Issue.
Sterling is primarily involved in investing funds in mostly debt capital denominated in foreign currencies. At September last year, profit from operations totalled $48.36 million or 16 cents per share and total comprehensive income ended at $62.8 million. For the September quarter, profit amounted of $9.9 million down from $12.57 million in 2013 with negative total comprehensive income of $2.3 million. At end the end of the period equity capital amounted $544 million. NCB Capital Markets are the brokers to the rights issue.
The Directors intend to consider the payment of a final dividend at the Directors meeting that is scheduled on February 21, 2015. The company paid a dividend of J$1.35 in June last year.
Odeon closure to boost Palace’s profit

Carib cinema, the largest money generator for Palace
The improved profit out turn comes from flat revenues in the quarter but down from 7 percent for the six months. But profit should get a big boost with the close of the Odeon Cinema in Mandeville. The Mandeville cinema had revenues of nearly $23 million in the six months to December 2013 and $10.7 million in the first quarter of 2014, there was no income in the December quarter. Odeon also contributed over $4.6 million to losses in the half year versus $5.7 million in the 2013 period. In 2013 fiscal year the company lost $17 million or nearly $12 per share in the Mandeville operation. Some assets at that cinema was sold off, resulting in gain on sale of fixed assets of $2.3 million reflected in other income.
The segment results suggest that box office, the main revenue generator is a loss leader, as profit is coming only as result of advertising income of $23 million and other income of $5 million for the half year. This situation is unlikely to change even with higher gate receipts in the second half of the year. The segment numbers also indicate that the revenues from this area is contributing more in 2014 as percentage of box office sales than in 2013 and 2012. In 2014 the two Kingston cinemas raked in 43 percent from confectionary sales, up from 41 and 42 percent respectfully, while Montego Bay moved from 37 percent to 38 percent. For the financial year ending June 2012, the ratios were 40 percent, 43 percent and 39 percent respectively.
 Going forward Palace is likely to benefit from increase in ticket prices implemented at the end of 2014 and lower utilities cost, with a fall in the price of oil and by extension electricity cost. In 2013 fiscal year utilities cost $65 million, but that would include water light and telephones, regardless there should be a few million dollars shaved off cost.
Gross profit margin jumped by 35 percent in the December quarter, from 17 percent to 23 percent, partially helped by the closure of the Mandeville cinema, and improved by 12 percent, for the year to December, as the margin moved to 23 percent, from 24 percent in 2013. Administrative expenses were flat for the last quarter and up slightly for the year to date.
Interest bearing debt is down to $27 million, cash is at $70 million but working capital is only $12 million.
Agostini’s acquires Facey in Barbados
 Agostini’s Limited, a Trinidad and Tobago listed company said on Friday that it acquired all the shares in Facey Trading a fast moving consumer goods Barbadian company.
Facey Trading is a distribution business operating in Barbados and was owned by Facey Group with headquarters in Jamaica. Paul Scott of Facey Group, confirm the sale to Agostini’s. They approached us with an offer and we decided to sell, we sold the business but kept the property which is leased to the new owners of the business Scott, confirmed in an interview with IC Insider. It would appear that the size and state of the Barbadian economy played a role in the decision to sell. Facey Group continues to operate in Barbados in the IT and telecom phone card sector Scott said.
 Agostini’s reported profit of TT$27 million for the first quarter to December 2014 from revenues of TT$408 million compared with profit of $27 million from revenues of $378 million in the 2013 period. For the year to September 2014 revenues came in at $1.36 billion resulting on full year’s profit of $80.5 million. Earnings per share for the quart was 46 cents and $1.36 for the full year. The stock last traded at $17.60. Agostini’s is involved in pharmaceutical, personal care, food and construction product distribution.
Profits up 28% at Jamaican Teas

The Orchid property being developed that should add to Jamaican Teas’ profits in 2015 & 2016.
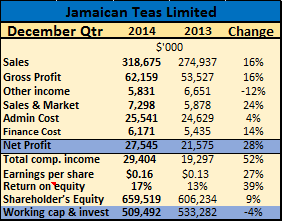
Sales were helped by 91 percent jump in exports, moving from $55 million to $103 million. The increase in exports, relate mainly to supplies to the US market and is partially due to the appointment of a new Distributor for the North East USA and expect that this will result in further improvement in sales. Revenues for the group, in the prior year, included $21.75 million in Real Estate sales. Excluding these sales, revenues would be up 26 percent for the quarter. Group sales also benefited from the launch of four new products during the period. Sales for Supermarkets are up 9 percent compared to the comparative quarter, in 2013, however, profits are flat. The jointly owned Supermarket in Montego Bay showed a reduction in losses which was helped by certain actions taken to reduce cost in 2014.
Gross profit margin increased to 24.3 percent from 24 percent in 2013, while gross profit increased 16 percent to $62 million but cost rose in other areas, with marketing climbing 24 percent to $7.3 million, administration by only 4 percent to $25.5 million and finance used to generate revenues in the period, is up 14 percent to $6.2 Million.
 Property Development| The group has completed construction of more than 50 percent of units in phase 1 of the development in Yallahs, St Thomas. Approximately a half of the units in the first phase have been sold, delivery to the purchasers should start in April. The group should enjoy increased profits from this development which should start reflecting in the June quarter.
Borrowed funds stand at $320 million including long term debt of $228 million and equity capital at $660 million.
Barring any unforeseen developments, 2015 could produce the best financial performance far. The stock which is now at $2.55 seems to have much room for growth.
Profit up 137% for RJR in Q3

TVJ one of RJR’s subsidaries
The major improvement should be great news to shareholders who have seen the price of the stock tumble to a low of $1 per share last year, as profit melted away with sluggish revenues growth. The final quarter based on history, is likely to be a small profit at best, hence investors should not be looking at too much more in profits when the financial year ends. Earnings per share ended at 29 cents for the quarter and 32 cents for the nine months.
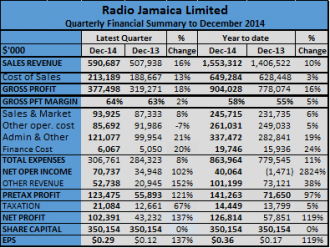 Gross profit margin improved in both the quarter and year to date, versus the prior year as sales grew 16 percent to $590 million in the quarter and 10 percent in the nine months, to reach $1.4 billion. Other revenue jumped sharply in the quarter due to foreign exchange gains, management states. Gross profit also increased at a faster pace than sales revenues. Cost increases were kept to 8 percent in the December quarter and 11 percent for the nine months.
RJR is in a healthy financial state with cash funds amounting to $130 million, loans of $2036 million, working capital of $565 million and equity capital of $1.3 billion.
The stock last traded at $1.10 on the Jamaica Stock Exchange on Friday.
Is Carreras set for price rise?
 A price increase cannot be far away for cigarettes sold by Carreras, with margins under pressure flowing mainly from slippage in the value of the Jamaican dollar taking a toll on the margins, since the last price increase in 2013.
With the squeeze in margin, sales also fell in the December quarter by 11 percent, bringing the year to date sales increase to only 5 percent. Cost slipped 1 percent in the December quarter, with a sharp reduction of 57 percent in sales and marketing cost for the quarter and 24 percent for the year to December. Administrative cost jumped 22 percent for the quarter and 16 percent for the nine months. The decline in sales may just be a normalisation in sales. In the past, there was speculation around the end of each year that the company will increase the price of cigarettes which encouraged the trade to stockpile ahead of such price movements and profit from it.
Carreras has entered into an agreement to sell the factory location that it operates from in Spanish Town to Kingston. Cost is expected to decline as a result and should ease some of the pressure on the bottom line. Those savings will be inadequate to cover the fall in gross profit suffered in the December quarter of more than $220 million.
 At the end of the year the cigarette marketers, reported profit of $763 million for the quarter and $1.97 billion for the nine months to December earnings per share for the quarter amounted to $1.57 and $4.05 for the nine months and is on target to hey close to $6 per share from continuing operations. During 2013 the company booked a large gain for interest due on debt owed to them by the tax authorities. Investors should expect high dividend payment and periodic spurt in profits after the company adjust prices higher. Price has been on the move since bottoming at $32 last year and is now at $44 but seems headed higher in the months ahead as interest rates continue to fall.
Rights for TCL shareholders
 Shareholders in Trinidad Cement will be offered additional shares in the company by way of a rights Issue of 124,882,568 new shares, to be priced at TT$2.90 per share. Shareholders will be offered the right to purchase one new share for every two shares held. The stock last traded at $2.70 on Thursday on the Trinidad Stock exchange. The issue if fully taken up will raise $362,159,447 for the company.
The issue will be underwritten by up to US$45 million by Sierra Trading an affiliate of Cemex SAB to ensure that the minimum funding targeted of US50 is met. In order to have the underwriting of that magnitude the company needed to and got permission of shares at an extraordinary meeting to lift a 20 percent shareholding limitation, in case the shareholders did not subscribed to enough of the rights they are entitled to.
Sierra Trading will take up the rights due them on their 20 percent ownership of the group. The agreement stipulates that if after the rights issue the underwriting company does not get up to 35 percent of the shares of TCL then there will be a private placement of TCL shares to bring the holdings to 35 percent of TCL issued shares.

Carib Cement One of the groups subsidiaries
TCL is loaded down with debt at relatively high interest rates. The debt at the end of 2013 was just under TT$2 billion all of which has been switched to current liabilities as a result of the default occasioned by the decision of the company to suspend payment on the debt pending negotiation of the terms. Equity stood at TT$570 million at the end of September, well below the debt. All amounts are in TT dollars. If the fresh capital is raised equity will reach around $1 billion and loans should decline to around $1.3 billion by the end of 2015 or close to a one for one relationship between debt and equity. The improved capital profile of the company should allow them to finance the remaining debt at a more advantageous cost than currently.
The rights is not badly priced as the stock an IC Insider BUY RATED seal of approval is severely undervalued on the TTSE. Investors will of course take into consideration negative economic development in Trinidad its main market with the fall in oil prices world wide an its impact on revenues for the country.