 Trinidad Cement posted strong first quarter results for 2015 with profit after tax rising sharply to $42.5 million versus just $13 million the year before, from revenues of $515 million.
Revenues were just slightly better than the $513 million generated in 2014. Group revenue increased, due mainly to cement price increases implemented during 2014 and 11,100 tonnes increase in clinker sales volume. Cement sales volume declined by 4 percent, Management stated in their release of the results to the stock exchanges on which it is listed in Trinidad and Jamaica. Vastly improved results in Jamaica, was one of the major contributor to the improvement.
During the quarter interest cost rose to $56.4 million, compared with $50.8 million but depreciation fell from $31.5 million to $27.7 million incurred in 2014. Taxation charge however, increased from $4 million to $10.4 million.
The company had effectively defaulted on its loans but that has been remedied with the execution of the restructured debt agreements. The loans have now been re-classified from short term to long term, thus improving the working capital from a deficit of $1.5 billion at December 31, 2014, to a surplus of $650 million at March.
The company’s rights issue was successfully concluded in March, with 124.9 million shares issued to raise $361.5 million. In addition, restructured debt agreements with lenders came into effect as at the end of March, the main elements of which include: Interest rate savings of 2 percent reduction; forgiveness of the default moratorium interest from September 30, 2014 and a discount offered by the financiers if the loan is repaid in 90 days.
Funds generated from operation based on the results and the rights issue resulting in net cash balance at the end of March of $548.3 million.
The stock which was elevated to BUY RATED in 2013 continues to hold that status as earnings for the full years heads towards 60 cents per share.
TCL continues to gain strength
Carib Cement impressive profit
 Caribbean Cement posted impressive first quarter results for 2015, with profit after tax rising sharply to $248 million versus just $35 million the year before, from revenues of $3.58 billion. Revenues were just slightly less than the $3.6 billion generated in 2014.
Domestic sales volumes fell 3 percent, while exports declined sharply from 61,000 tonnes to 40,000, however, an increase in clinker sales from 44,261 tonnes to 55,371 mitigated the decline in cement sales somewhat. Lower energy costs, improvements in operational efficiencies, effective control of fixed costs and lower financing costs, were the major factors helping in the improved profit out turn. These results suggest that full year earnings could rise to $1 per share for 2015 and may well exceed it, if energy cost remained contained at current levels.
During the quarter interest cost remained fairly static with $65.5 million incurred, compared with $66 million in 2014 but depreciation charge climbed from $84 million to $93 million.
At the end of the period, cash increased from $178 million to $543 million. As impressive as the results are, the company has an operating deficit of $7 billion that will take years to wipe out, even at the level of profits now being generated. There are capital gains on the books of $1.4 billion, that can be used to offset the operating deficit, thus reducing the overall amount, nevertheless, the resumption of paying dividends is years away.
The stock which was elevated to BUY RATED in 2013 continues to hold that status and traded at $3 on the Jamaica Stock exchanged on Tuesday in response to the results.
NCB post increased Q2 profit
 National Commercial Bank is reporting net profit for the three months ended March 2015 of $3.27 billion versus $3.05 billion in the 2014 period.
Changes in the manner the tax of the groups assets are now being treated with all amounts due being booked as expenses up front has distorted the results in the early months of the fiscal year which are front loaded with these cost. Normalising the expenses would result, according to NCB in net profit for the three months ended March 2015 of $3.34 billion, 20 percent or $563 million over normalised net profit for the December 2014 quarter of $2,778 million, and 12 percent or $349 million over the previously reported net profit for the three months ended March 2014 of $2.99 billion. For the six months to March the banking group reported profit of $5.4 billion or $2.19 per shares compared with $5.55 billion in 2014. The up-fronting of the asset tax, resulted in the lower 2015 profit compared to 2014. NCB should go on to earn around $7 billion in the second half of the year or around $5 per share for the full year.
For the six months to March 2015, operating income increased by 14 percent, or $2.9 billion, compared with the six months ended March 2014, mainly as a result of gain on foreign currency and investment activities, up by $1.5 billion. This was due to higher levels of foreign exchange income and gains from the sale of debt securities compared to the prior year, NCB said.
Also contributing to the increased profit is net fee and commission income, increasing by $652 million or 16 percent, mainly due to Payment Services fees related to card usage and transaction volumes, credit related fees from the growth in loans and greater corporate finance and unit trust fees booked in the current period, the banking group stated in its release to the Stock Exchange. Net interest income, increasing by 4 percent, or $542 million, primarily due to growth in the net loan portfolio.
Loans and advances, totalled $157.9 billion (net of provision for credit losses) at March 2015, grew by 5 percent, or $7.4 billion, compared to the loan portfolio as at March 2014.
NCB declared an interim dividend of 45 cents per ordinary stock unit which is payable on May 21 for stockholders on record as at May 8, 2015.
Paramount’s Q3 sales fell cost rose
 Declining sales and rising cost in the February quarter over the November quarter were the noticeable features for Paramount Trading. The result, lower profit only $26.4 million versus $49.2 million.
Profit nevertheless jumped 121 percent to $109 million for the nine months to February this year with the February quarter rising 82 percent over that of 2014.
The slippage in performance in the latest quarter came from a drop in sales to $209 million from $228 million in the November quarter and a fall in gross profit margin from 37 percent to 32 percent as cost of sales remained at roughly $146 million in both quarters. Total administrative and other expenses also rose in the last quarter over that of November by close to $6 million or 13 percent but they were lower than in the 2014 quarter as finance cost fell sharply from $8 million to only $2 million.
Total revenues rose 18 percent in the February quarter and 25 percent for the nine month period to hit $213 million and $651 million respectively.
The company reported earnings of 17 cents per share for the quarter and 71 for the nine months and is on its way to reporting profit of $1.10 per share for the current year ending in May and $1.50 for the following year.
 Finances| Paramount has seen a slight improvement in receivables with a reduction in the number of weeks amounts are due for falling from around 10 weeks in February 2014 down to 9 weeks in 2015 even as the amount increased from $139 million to $151 million. Inventories rose to $275 million from $216 million in 2014 and cash funds rose to $79 million. Amounts due to suppliers is steady at $127 million with the 2014 year-end figures and down from the amounts due at February 2014.
The company deals mainly in chemicals and is listed on the junior market of the Jamaica Stock Exchange, the last price is $3.55, giving it a PE of 3.2 thus maintaining its BUY RATED status.
Knutsford riding high
 Junior market Knutsford Express, enjoyed a very profitable 2014 with a 92 percent increase in pretax profit for the February quarter of $19 million and 45 percent increase for the nine months to $48.5 million.
Contributing to the big jump in profits is a 46.9 percent climb in revenues to $334 million for the nine months and $126.5 million for the quarter, for a 39.6 percent gain. Administrative and other cost rose 33.7 percent in the quarter and 46 percent for the nine months. The earnings translate to 19 cents per share for the quarter and 49 cents for the nine months.
Borrowed funds amount to $23 million with cash funds of $55 million. The company added to its fixed assets which moved from $126 million as of May last year, to $173 million as it expands the fleet of buses on the road and now covers Jamaica with land transportation from north to south and east to west.
The company’s stock traded at $5.60 with a gain of 40 cents after the results were released. the stock remains IC Insider Buy Rated, but it is not expected that there will be much more gains in the short term with a current PE of 8 times 2015 earnings.
VMBS raises profit in 2014
 Victoria Mutual Building Society (VMBS) reports a slight increase in profit of $1 billion for 2014 up from $943 million in 2013.
VMBS generated income of $7.2 billion in 2014 and in 2013 revenues of $6.5 million. The group ended with assets of $97 billion up from $86 billion. Equity capital rose to $11.35 billion from $10.37 in 2013. Mortgage loans rose $31 billion from$27 billion in 2013 and cash funds of $10 billion. Other major assets are Repos amounting to $16 billion, investments mostly in government securities $33.5 billion. VMBS is primarily in the business of providing home mortgages.
Kremi profit up 40%
Kremi profit jumped 184% in the February quarter over that of 2014.
Revenue increased 11 percent for the February 2014 quarter, reaching $274 million but most of that is due to price increase and 19 percent to $1 billion for the twelve months.
Gross profit margin climbed to 28.44 percent in the latest quarter from 25.9 percent in the 2014 period but for the full year, the margin was at 27.59 percent compared to 23.67 percent for the 2014 period. Going forward, the margin should improve even more with the blast freezer installed in November, which management says will reduce utility cost and create capacity for greater production to enhance sales volume.
 Administrative cost rose by 37.7 percent to $168.8 million for the full year and by 6.9 percent to $44.5 million for the quarter. The slower growth in the latest quarter is an indication that cost increase in the area is normalising and that is a god sign going forward. The company should also benefit from lower marketing cost in 2015 with the upfront cost for the rebranding and advertising picked up last year repeating in the current year. The last quarter reflects the lower on going marketing cost at just $6 million compared to $11.4 million in 2014 and $37.8 million for the full year versus $27 million in 2014. Finance cost in the quarter jumped to $10 million from $4 million in the prior year and an average of just over $5 million in the prior quarters. Based on the funds borrowed the cost going forward should be around $5 million per quarter subject to repayments and changes in interest rates if any.
Going forward the benefits of blast freezer will be reflected for the full year, while it only partially impacted the last quarter of the just concluded fiscal year. They increased prices around 15 percent ahead of the Christmas period and may have seen some cut back in volume in the quarter as a result. They should be able to recover volumes going forward and even expand on it as the shock effect of the price increase wears off and more retail outlets are added.
Importantly, electricity cost will fall from two standpoints one is the lower electricity cost around 20 percent from the peak last year and lower cost due to the faster freezing of ice cream thus using less energy. The cost of milk or milk powder is down quite sharply as well. With all of the above earnings of 2015/16 could land at 60 cents.
AMG profit up 35%
 AMG Packaging, managed a 35 percent growth in profits of $31.7 million for the six months to February this year, the company’s latest financial report shows, thanks to a 194 percent jump in second quarter profit that reached $16 million up from only $5.5 million in 2014.
IC Insider’s forecast, is for profit of $85 million or 85 cents per share for this year and $1.50 for 2016. While profit surged, revenues rose a modest 8 percent in the February quarter and only 4 percent for the six months with sales volume having declined by 9 percent for the half year. The volume decline comes against the background of a 24 percent increase in units sold for the period to February 2014, resulting in a 42 percent jump in revenues. Helping to boost profit, was an improvement in the gross profit margin for the latest quarter to 24 percent versus only 16 percent in 2014 and 23 percent for the six months, compared to 19 percent in 2014.
Gross profit for the quarter amounting to $35.5 million, increased by a very strong 63 percent from 2014 and 27 percent for the six months, to near $70 million. Flat inventory cost and a reduction in other direct cost laid the foundation for the improvement in direct input cost and a swelling of the profit margins. Administrative cost rose 30 percent for the quarter and 29 percent for the year to date period well ahead of revenue growth, thus negating some of the top line improvement.
 Cost got hit, with the Jamaican dollar losing value, resulting in 28 percent more Jamaican dollars having to be found to purchase one US dollar, since September 2012. The price of paper on the world market, increased by 22 percent, from US$720 per tonne at September 2012, to US$830 in August 2013 and to US$875, which it has been since June last year.
Receivables are down by $13 million from the amount of $81 million at the end of August last year and so too is amounts in payables by $10 million from $71 million. Cash funds fell slightly to $19 million from $22 million while inventory is up from to $118 million at August to $120 million, which is nearly 4 months supplies based on sales in the quarter and is up from just two and a half months back in 2013 and seems to be a hedge against devaluation of the Jamaican dollar. Borrowings fell from $97 million at February 2014 to $58 million with $14 million to be repaid during the next twelve months, the decline will help reduce cost with lower interest payments going forward.
JN General doubles 2014 profit
 JN General Insurance more than doubled profit for the year to December 2014 with after tax profit hitting $566 million, a 95 percent increase over the $291 million reported for 2013.
The impressive increase came from a mere 8.6 percent increase in premium income amounting to $3.59 billion which helped in leading to an underwriting profit of $160 million compared to a loss of $149 million in 2013. Investment income contributed $471 million to the bottom-line and foreign exchange gains $83 million. The company donated $10.4 million to the JNBS Foundation during the year up from $9.7 million in 2013.
The company which is a subsidiary of Jamaica National Building Society boast assets of $8.5 billion and equity of $3.97 billion at the end of 2014.
JMMB profit down slightly but…
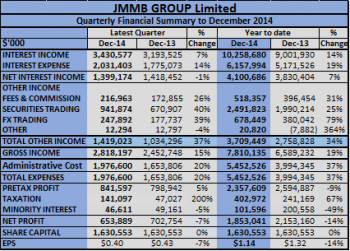
 JMMB Group posted a 14 percent fall in net profit compared to 2013, with profit after tax of J$1.85 billion. Earnings per share amounted to J$1.14 for the nine month period to December 2014, and $644 million after tax, for the December quarter or 40 cents per share, in line with the September quarter results of $651 million but just 8 percent below 2013. Operating expenses, however, rose by $220 million in the quarter above that of the September quarter, helping to keep profit down.
Earnings for the full fiscal year to March, should end around $1.60 per share, at a stock price of $7 and a PE of 3.5, the stock is undervalued. Profit before tax was higher for the latest quarter, a near $100 million increase in corporate tax provision resulted in net profit falling behind the December 2013 quarter. Operating revenues grew 18.1 percent over prior period, to J$7.8 billion, due mainly to acquisition of two subsidiaries and $2.8 billion for the quarter versus $2.45 billion for the December 2013 quarter.
 The group’s Net Interest Income grew J$270 million or 7.1 percent year-over-year to J$4 billion. Management attributed the growth to “expanded business lines through the acquisition of Intercommercial Bank (IBL) in October 2013, coupled with effectively managing the group’s investment portfolio and cost of funds. Other operating revenues, namely, gains on securities trading, foreign exchange margins from cambio trading, and commission income also reflected increases of 25.2 percent, 78.5 percent and 30.7 percent respectively, these were driven largely by volume increases and taking advantage of market opportunities. Our operations in the Dominican Republic continue to produce positive results contributing J$508 million to the Group and IBL contributed J$162 million to the group’s earnings.”
Operating expenses increased from J$3.99 billion to J$5.45 billion. ”Expenses associated with the expansion of the group through the acquisition of IBL and AIC Securities accounted for J$796 million (54.6 percent) of this increase and the remaining J$662 (45.4 percent) is attributable to costs associated with integration, growth in subsidiaries in the regional markets, increase in asset tax and normal inflationary increases”, management advised shareholders.
One of the effects of the increase in operating costs was that the group’s efficiency ratio (administrative costs as a percentage of operating revenue) moved from 60.4 percent in 2013 to 69.9 percent. Management is taking medium to long-term measures to correct this increase, mainly through extracting synergies from its recent acquisitions through its integrated financial services model across regional territories, the company stated.
 Concerns|Insider selling of the company’s stock has been high, raising concerns about the prospects going forward, with the likely impact on earnings that could arise with the restrictions being placed on repo trades that will see smaller amounts no longer acceptable to be booked directly by dealers. This change will affect margins on such funds, even if they are shifted to unit trust. The company made much income from foreign exchange trading which could be curtailed with what seems set to be greater stability in rate of the Jamaican dollar against the US dollar. IBL is operating in Trinidad where the economy is facing reduced income from the energy industry with the fall in the price of oil and gas, the country also is faced with high inflation, these developments are likely to see measures being implemented that could constrain business activities and so affect income and profits in the subsidiaries in that country.
Locally, Treasury bill rates have been falling since the first half of 2014 and seem set to decline some more, this can be both positive and negative, depending on the length of time, funds are placed on the asset and liabilities sides. Lower rates mean less income being earned by the company’s own funds, some investments will see an increase in values and greater activity in the stock market which can lead to more fee income as well as appreciation in any stock portfolio it may hold.
JMMB Group will replace shares in Jamaica Money Brokers shortly, and become the listed company. Shareholders of the group were paid 33 cents in dividend last year.