 Jamaica’s Berger Paints reported big improvement in profit flowing from a near 14 percent increase in sales revenue to $440.6 million up from $387.3 million, in the 2014 first quarter, with profit ended at $17 million after tax well up on the reported a loss of $372,000 in 2014.
Earnings per share ended at 8 cents and for the year earnings should be in the 55 cents per share region, if the present trend continues which should be helped by the low price of oil on the world market as a major input into the production of paints is fuel oil based.
For 2015 fiscal year to March, Berger reported profit of $67 million after tax and earnings per share of 31 cents from sales revenues of $1.85 billion.
Gross profit was slightly up on 2014 with $1.286 billion realized in the March 2015 quarter and $1.257 billion in 2014. ”The company continues to yield benefits from process improvements, energy cost savings and its plant and Machinery upgrade, these along with growth in sales contributed to the profit performance” Mustafa Turra, General Manager reported in a short report to shareholders.
Berger last traded on the Jamaica Stock Exchange at $2.55 but that is before the above results were disclosed on Friday.
Berger Jamaica in big profit upturn
Kingston Properties pulls in $650m

One of Kingston Properties units at Red Hills Rd, Kingston
The Rights Issue which opened on Wednesday, July 22 closed on Friday; August 7, 2015 after an extension by a week. The company stated that there were over one hundred (100) subscribers to the issue.
The plan was that the issue would raise at least $954 million from the 136,271,694 units on offer at $7 each. The amount raised more than doubled the issued share capital that was just over 68 million shares, moving it to 160 million units and the overall equity base to $1.5 billion.
KPREIT reports currently owning fifteen units in the Miami Loft II condominium building, as well as a nineteen unit residential complex in South Florida and an office and warehouse complex in Jamaica. The company will use the proceeds to pursue expansion plans in various real estate markets in the United States and Caribbean countries.
The company is yet to release the second quarter results. For the first quarter, rental income of $25.6 million was recorded versus $25 million in the prior year, with profit before tax of $2.9 million compared to a loss $680,000 in 2014 and total comprehensive income came in at $12.3 million for the March 2015 quarter versus $18.2 million in 2014.
Huge jump in National Flour’s profit
 Trinidad’s National Flour Mills reported a 200 percent jump in profit for the six months to June to $20.57 million versus only $6.79 million in 2014 and earnings per share of 17 cents and 10 cents for the quarter.
Profit fell in the June quarter from that of last year to $11.7 million versus $14.3 million but from higher revenues as profit margin shrank to 23 percent from 26 percent. Revenues climbed 15 percent for the six months to $245 million and a 10 percent gain to $124 million for the June quarter.
Helping the company is the sharp fall in the price of wheat on the world market from a high of more than US$700 to just over US$500 now but below US$500 per tonnes for quite a bit of the reporting period this year. National Flour earnings for the full year to December should end around 40 cents per share.  The stock trades at $2.10 around 5 times earnings, a low valuation and if the company can maintain the level of profit now being generated and hopefully improve on that in 2016, the stock stands to generated a good level of appreciation. Investing in the stock is not without risk. The largest item of cost, wheat and the ability for management to adjust prices if wheat prices increase can be critical.
Borrowings have declined from $122 million at the end of the financial year in December last year to $57 million at the end of June while cash fuds are at $57 million while equity stands at $215 million.
The company shares are listed on the Trinidad Stock Exchange.
Product expansion at AMG
AMG Packaging (AMG) a junior market listed company advised the Jamaica Stock Exchange of their decision to expand into the manufacturing of toilet paper and hand towel. AMG will be manufacturing these additional products, at a facility leased on Orange Street, downtown Kingston and anticipates starting production by the end of October 2015.
 The company says it “ is confident that this new venture will aid in decreasing the importation of products, provide meaningful employment opportunities subsequently assisting the growth of the Jamaican economy.”
AMG Packaging ventures into the new ventures at a time when it appears that real growth in it’s existing business has slowed considerable in the past year, the new business is likely to boost sales volume and ride on some of the existing overhead costs of the current Packaging operations.
AMG Packaging, currently, involved in the manufacturing of boxes, for packaging, reported a 42 percent jump in the nine months’ profits to May 2015 of $52 million, compared to $37 million in 2014. Profits grew 58 percent for the latest quarter to $21 million over that of 2014. Sales revenue rose just 4.5 percent for the nine months to May, this year, to reach $462 million and is up by 6 percent for the last quarter, hitting $161 million. The increased revenues in the May quarter and nine months to May this year, is well down on the strong 36 percent rise in the May 2014 quarter of $152 million and 40 percent in the nine months to May, to reach $442 million.
Toilet tissue and hand towels are products that are sensitive in nature including pricing, is likely to have a wider market than the existing products of the company.
Big new income stream for JSE
 The Jamaica Stock Exchange is to receive another big shot in the arm, with a totally new source of income flowing from the decision of the Financial Services Commission that all retail repurchase agreements, must migrate to the Jamaica Central Securities Depository Trustees Services (JCSD) effective 31st of August.The total book of repurchase agreements amounts to approximately $500 billion as of March this year, the amount to be transferred may be lower has the FSC new regulations require that the minimum amount for a retail repo that is now J$500,000 and US$5,000 and is scheduled to be increased on a phased basis to $1 million and US$10,000 by December 31, this year.
Based on the fee structure the JCSD should earn around $50 million a year in fees from the securities supporting the repos. There will also be fees to be paid for each repo transaction, such transactions will be evidenced by an account held in the purchasers name at the JCSD. According to Robin Levy, Manager of the JCSD they will be trustees for the assets that back the repos, as such the dealers will no longer hold them directly in their name thus legally separating the ownership from the repo issuer during the duration of the repo agreement.
 The stock exchange group will earn an annual fee for each dealer who is registered to deal in Repo securities by the JCSD. The fee structure listed on the Jamaica Stock Exchange has the annual fee at $100,000 with 20 dealers in the country the income from this source will be small only around $2 million per year if all of them sign on. The repo registration fee is likely to be the big income generator as each transaction will incur a fee based on its value.
The JSE enjoyed a very good first quarter this year with huge increase in income, a fare bit coming from one off type transactions but in addition increased trading activities flowing from increase trading levels on the JSE this year contributed to improved profits for the year to date. The JSE stock last traded at $6.23 on the JSE on Friday to gain over 300 percent for the year to date, but with earnings per share now looking like heading towards $1.50 level there is room for another surge forward for the stock. The company’s 2015 second quarter numbers should be out this week based on the released of the June 2014 quarter results on the July 23, last year.
Milk powder at 3 years low
 Milk powder and butter cream are two of the largest inputs into the production of ice cream, Christopher Clarke Chief Executive of Caribbean Cream makers of Kremi ice cream informed IC Insider.
The world market price for powdered milk has declined to the lowest price in three years with the trajectory pointing to still lower prices ahead. What this means is that makers of ice cream should be enjoying lower input cost of milk powder in the months ahead. The data was obtained from GlobalDairyTrade.
Some big Buy Rated gains more ahead

Hardware & Lumber with its Rapid True Value retail arm gained 265% since place on BUY RATED list
Blue Power is now removed based on flat sales for the year to April and no immediate signs of a pickup. Dolphin Cove that was added in May last year and gained 48 percent is being moved to hold as revenues in the other half of the year to December is unlikely to grow to justify market out performance. The company had only a 6 percent increase in first quarter revenues down from 13 percent in 2014 and profit fell 10 percent to $133 million. Hardware and Lumber with buy out talks to acquire majority ownership with a maximum price of $18.50 and Scotia Investments are shifted to hold while JMM Group is moved from Buy Rated to Watch or accumulate based on the current price of $7.50.
As much as stocks with high gains may be view as already providing rich returns, there are much more gains left to be made. Carib Cement should report earnings in the $1 region this year with reduced cost, increased sales and the future should be even brighter as the local economy moves slowly into growth and lower interest rates will help boost building construction. Caribbean Cream has more than doubled this year in price but with lower input cost and increased sales should earn around 60 cents per share this year, at the present price of $1.60, there is room for growth.
 Jamaica Stock Exchange has had a phenomenal run this year with increased revenues and profit. Profit this year could reach $1.20 which should lift the stock some more and 2016 could be an even bigger year for it. Paramount Trading at $6 is still about 50 percent undervalued based on 2015 earnings and even more based on 2016 projected earnings. Lasco Manufacturing is yet to deliver in price movement but the 78 percent jump in the March quarter profits is a development that investors should be paying attention to.
Over in Trinidad, investors keep on ignoring Trinidad Cement but they should not, even with the 190 percent gain in the stock price. IC Insider sees higher profits flowing from increased sales, cost reduction including interest cost on loans. National Flour which we added in May is now up 21 percent still has more room to grow. The Trinidad market is likely to experience slow growth this year as such, many of the listings may not deliver much in the short term but investors should keep their eyes on Scotiabank that produced a nice lift in second quarter profits.
LascoMan profit jumps 78% in Q4
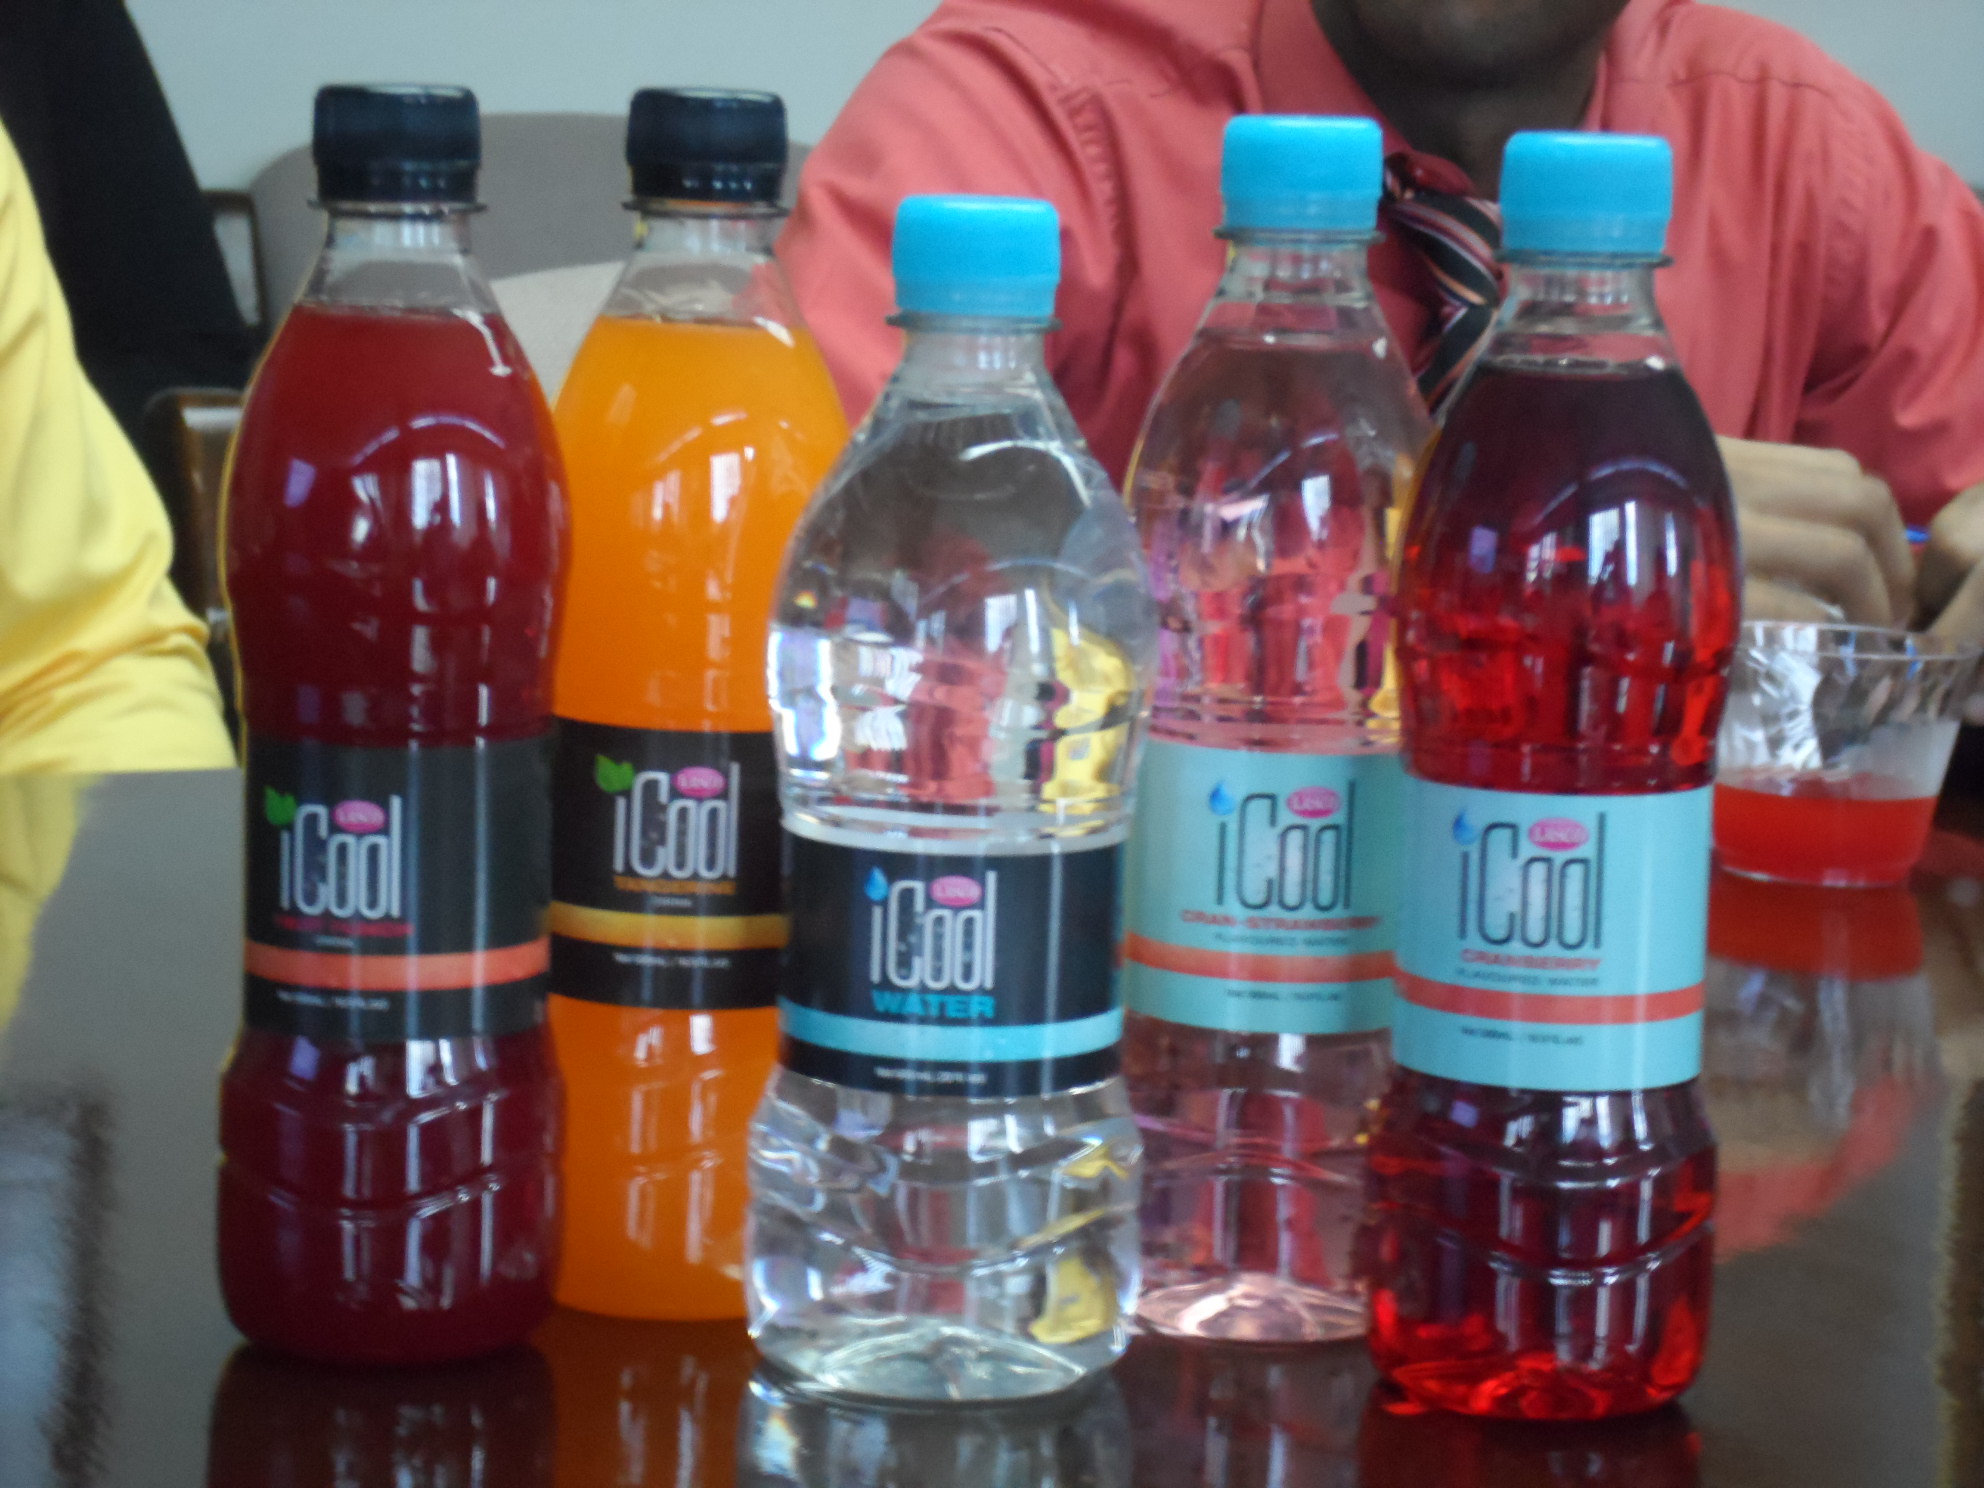
Lasco’s new I Cool drink where demand is resulting in an increase in the plant size.
For the financial year, revenues climbed 19.4 percent to $4.8 billion from $4.03 billion and profit of $669 million is up from $584 million. Gross profit climbed 34.7 percent well above the growth in revenues, a very positive development. Gross profit for the quarter jumped a huge 86 percent helping to deliver the stunning increase in profit for the quarter and augurs well for results for the coming fiscal year, and is a result of new products now being produced by the new plant.
Administrative expenses climbed 44 percent to $555 while finance cost moved from $73 million to $125 million. The average number of persons employed by the company during the year was fifty-one up from forty-two in 2014 helping to push labour cost from $147 million to $209 million. With the new factory facilities operational, depreciation ended at $67 million up from $27 million in 2014 but is set to jump in 2016 with only a Borrowingfraction of the annual charge booked in 2015, additionally, there are more assets to be transferred to fixed assets that will give rise to even higher depreciation charges.
Borrowing climbed to $1.64 Million from $1.49 billion at the end of March 2014, the increase helped to fund capital expenditure of $523 million during the year. A total of $329 million was paid back on loans during the year.
The last quarter numbers suggest that profit could end around $1.2 billion for the year or around 30 cents per share. While the company becomes taxable this year capital allowances coupled with tax payable at 12.5 percent, will result in little or no taxes being paid on profit for the year.
The net book value of property, plant and equipment includes assets under construction amounting to $1.34 billion. The cost will be depreciated once the property is complete and available for use. The estimated additional cost of completion of the facility is $373 million.
The company is listed on the junior market of the Jamaica Stock Exchange and last traded at $1.31 for an historical PE of just over 8 and around 4 based on IC Insider’s projected earnings. The stock should deliver a healthy increase in price during the fiscal year.
Little profit in Q4 for Lasco Financial
 Lasco Financial Services reported profit of $191 million or EPS of 15.5 cents for the March 2015 year, an improvement of 8 percent over the $177 million made in 2014. The last quarter was poor with only $10 million in profit, down sharply from $41 million made in 2014, due to a combination of developments.
Revenue for the last quarter hardly grew, ending at $148 million versus $145 million in the 2014 quarter while expenses grew by $28 million due mainly to increased spend on marketing and selling expenses. Jacinth Hall-Tracey, Managing director indicated that the period suffered from squeezed margins on foreign exchange trading and foreign exchange losses in the quarter, resulting from the revaluation of the Jamaican dollar and greater stability of the exchange rate. Loan disbursements slowed as credit rating data used in assessing potential clients resulted in lower loan approvals.
The PE ratio of the stock is 13 based on the last reported earnings, normally the ratio would not be that high. Mayberry’s acquisition of 20 percent of the company’s shares has changed the dynamics and remove some supply from the market.
The company has cash of $500 million and is generating over $200 million per year. If the company can find the formula to ramp up good quality lending successfully, the profit outlook can be transformed considerably with high profit margins for lending. “We are working on a number of initiatives that will help in the transition from lower income in foreign exchange activity” Hall-Tracey said. The area of credit approval is one that they is being revisited as the use of credit rating information is stymying lending. But Hall-Tracey expects profit for this year that ends March 2016 to be higher than for the year just ended, subject to taxes on profit which the company will start bearing at fifty percent of the official tax rate of 25 percent.
The equity capital of Lasco is $812 million and is well below that of its two siblings who have equity in equity of more than $2.4 billion each. The company has done well from the money remittance and cambio operations but it is in the lending that the future growth prospects seems to rest. Hence the connection between Mayberry with the know-how having been exposed at Access Financial. The company has the free capital to increase lending with only $147 million in loans at March.
Undervalued Caribbean Flavours
 The company seems poised to hit earnings of 65 cents per share for the June 2015 financial year, making it attractive for some short-term gains with the current price of $2.09 at a PE ratio of 3 times earnings, having earned 19 cents per share for the quarter and 43 cents for the nine months, to March 2015.
Caribbean Flavours & Fragrances enjoyed a moderate increase of 16 percent in profit for the March 2015 quarter over the similar period in 2014. The increase was helped by an improvement in gross profit margin that moved from 39.6 percent to 44 percent. Profit came in at $17.3 million for the quarter versus $15 million in the similar period in 2014. For the nine months to March, profit declined slightly from $39.7 million in 2014 to $38.9 million.
Sales were up moderately in the quarter from $62.8 million in 2014 to $67 million. For the nine months to March sales grew 11.7 percent to $210.6 million from $188.6 million but cost of sales rose faster than the growth in revenues from $111.7 million to $133.5 million in the nine months or 18.75 percent. Administrative cost increased 21 percent in the quarter, and just 2 percent for the nine months, vastly better than the high double-digit increase in the prior year. The return on average equity an attractive 33.5 percent per annum. The negative is that for its small size there is limited growth from existing operations.
The balance sheet is in a healthy state with equity of $195 million or $2.17 per share. There are no borrowed funds while current assets is $210 million versus payables of only $16 million.
The principal activity of the company is the manufacture of and distribution of flavours mainly for the beverage, baking and confectionery industries. The company also sells food colouring and fragrances.The stock is listed on the Jamaica Stock Exchange junior market and is recommended as a buy by IC Insider.