Mayberry profit crushed

Profit fell sharply at Mayberry Investments for the year ending December 2013, falling to $102 million as it declined sharply from $439 million reported in 2012. Earnings per share came out at only 9 cents as profit took a big hit of $337.5 million from the transaction in connection with the Government  National Debt Exchange Programme (NDX) in February last year. Without the NDX charge, earnings per share would have been around 22 cents in 2013.

Mayberry recorded a decline of $238 million in total revenues driven by declines of $112 million in net interest income, $111.4 million in fees and commissions and $42 million in dividend income and $129 million in net unrealized losses on trading portfolio. There were gains on disposal of a small portion of the associated shareholding of $60 million as well as increase in net foreign exchange gains $105 million.

Total expense for the year was 10 percent lower than for 2012 coming in at $681 million for 2013 and flowed from reduction in staff cost of $32 million and reduced provisions of $91 million as the company recovered some loans.

Mayberry_banner600X250Mayberry operating profit fell to $213 million from $374 million in 2012 before the NDX charge due mainly to lower net interest income and losses on investment valuation.

In the final quarter, Mayberry reported only $3 million pretax profit compared with $162 million in 2012 and after booking a tax credit, ended up at $42 million in the last quarter, still lower than the $176 million reported in 2012. In the last quarter, the company suffered from lower net interest income and reversal of credit loss gains achieved in the prior period.

Assets grew by $1.2 billion during the year to $22 billion partly funded by increased liabilities.

Related posts | Mayberry profit bleeds from NDX | Mayberry’s tough year so far

Margaritaville, down the road with risk

Come Monday March 3, the Margaritaville Turks IPO opens to the public with 21,156,555 ordinary shares on offer at a price of 10 US cents per share payable in US dollars. The IPO aims to raise US$2 million through the issuing of 5,260,740 new shares with the company pocketing the net proceeds. The remainder are existing shares being sold by the parent company Margaritaville Caribbean.

If the issue is successful in selling the minimum amount of 13.5 million shares, they will be listed on the main market of the Jamaica Stock Exchange. The company, incorporated in the Turks & Caicos Islands, now has 62,239,259 issued Ordinary Shares to Margaritaville Caribbean. After the issue, it is expected that the issued shares will climb to 67.5 million units and the ownership of the parent will fall 69 percent. The company is a small one with equity of US$3 million but the only debt are amounts due to creditors of $725,000 and current assets of only $841,000.

Value | For the six months to November 2013, revenues climbed by a strong 38 percent to hit $2.74 million with profit more than doubling to $442,000 and should be approximately US$900,000 for the full year to May 2014. For the year ending May 2013, revenues fell to $4.5 million from $4.79 million in 2012 with profits of $598,000 down from $880,000 in 2012.

Revenues were $4.86 million in 2011, $4.3 million in 2010 and $3.55 million in 2009. Profits during this period have not grown in line with revenues, with profit of $842,000 in 2011, $943,000 in 2010 and $1 million in 2009. No doubt the global downturn had a negative impact on the operations. The worsening profit out turn is tied to slipping margins, which was mostly in the 170 percent range between 2010 and 2011 but fell to 143 percent in 2012 and 105 percent in the 2013 fiscal year, and a recovery to 156 percent in the latest six month period as at November 2013. The level in the November quarter slipped to 149 percent.

margaritaville_entranceThe six month earnings to November 2013 work out at 14 cents per share with the PE ratio at 7 times earnings, a bit rich for main market companies. This is like a junior market listing. As such, the valuation is in keeping with those smaller companies.

US$ earnings | As the earnings are in US dollars, many investors may see much more in the IPO than the real numbers suggest. The shares are priced at 2 times book value, which is not out of line with many companies of similar size on the market. In fact, the net book value valuation is below several junior market companies and is selling at roughly one times sales, which seems to be on the high side compared with the majority of listed companies. The above suggests that investors may have to wait sometime for a rich payoff.

There is added risk | For one, the company has managed to cut cost of sales by what it says is “renegotiated price from suppliers” but this cannot go on forever. A positive is that revenues are up in 2013. Income is highly dependent on one location in a small territory, the Turks & Caicos, and continuity is subject to lease arrangements with Carnival Cruise Lines, the only cruise line doing stopovers at that location. The success of the business is highly dependent on visitors coming to the island by cruise ship and the facility is only open on those days that ships are in. In other words, absent the ships, absent the business.

The company appears to have business interruption insurance coverage for a major catastrophe, but it’s unlikely to cover any downturn flowing from less customers going on cruises. This doesn’t seem to be a problem in the short run with the increased revenues generated to date and the promise of increased visitors in 2014, but could occur at any time.

The Directors are planning to roll out a new Margaritaville menu early in calendar year 2014, which aims to increase average consumption per customer. The Directors also anticipate growth in the Company’s revenues in future, given the following factors:

  1. A continued increase in the number of ship calls to the Grand Turk Cruise Centre destination.
  2. Increase in the number of passengers visiting the Cruise Centre. Data received from the Carnival Corporation show an estimated 750,000 passengers sailed to Grand Turk and the number is expected to reach 1 million in calendar year 2014 based on pre-bookings.
  3. The addition of 4 new bars, and the upgrading of existing bar outlets, the addition of a new revenue centre with introduction of the new casual “Grab N Go” convenience dining concept, the opening of the South Beach Bar and Grill, which the directors anticipate will provide an alternative option for passengers who prefer a more sedate dining environment to that of the Company’s main restaurant, Margaritaville.
  4. The expected improvement of the Company’s average customer spend resulting from upgrading of remote point of sale (POS) system introduced in calendar year 2013, that facilitate the order process for customers’ convenience.

The Company is a part of the Margaritaville Caribbean Group and a wholly owned subsidiary of Margaritaville Caribbean. The Group operates the Margaritaville chain of restaurants in various Caribbean destinations, inclusive of the flagship restaurant in Montego Bay. The IPO listing will only offer shares in the Grand Turks-based cruise pier operation.

The stock may not take off big time in the short run, but it provides a means for investors to diversify their portfolios if they are prepared to accept what appears to be higher risk.

Blue Power profit slips

Blue Power profits slipped for the quarter to January this year as the profit margin got squeezed resulting in profit of $15 million compared to $23 million in the same period in the previous year. The Lumber Depot division contributed under $8 million and the Blue Power division added just over $7 million to the profit.

Profits for the nine months stood at over $70 million compared to $67 million in the same period last year, an increase of just over 5 percent. The contribution of Lumber Depot division was over $37 million, while Blue Power division added $33 million.

Earnings per stock was $1.25 for the nine months compared to $1.18 in the previous year.

Sales for the nine months ended January, 2014 were $780 million compared to $706 million for the same period last year, an increase of $74 million or 10 percent. For the period, sales for the Lumber division amounted to $543 million versus $466 million the previous year, an improvement of 16 percent while Blue Power soap division remained basically flat with sales of $237 million against last year’s $239 million.

Sales for the quarter ended January this year were $259 million versus $266 million for the comparative period in 2013. For the third quarter, Lumber Depot division achieved sales of $176 million versus $178 million the previous year, while Blue Power moved down from $88 million to $83 million.

BluepowerclotheslineReasons for fall | “Small declines in sales in both divisions reflect the tightness in the economy, which is being experienced by our customers, and which has also resulted in downward pressure on prices and margins. Our response to these challenging economic circumstances is to focus on keeping, as much as possible, a lid on price increases, reducing costs especially by investing in solar technology, improving packaging and quality to get greater market share, introduction of new products and bulk-buying to obtain better prices.” the company’s management stated in their release to shareholders.

Blue Power was able to hold administrative cost slightly below that of 2013 at $34.5 million for the January quarter. In 2013, cost in this area was $35.7 million and in the nine months $99.4 million, which fell to $96.8 million in 2014.

Other revenues almost doubled from $5.7 million to $10.8 million for the nine months and helped to keep profits up.

Margins | Gross profit slipped to 22.17 percent in the latest quarter from 28 percent in the 2013 period and ended pulling down the year-to-date margin to 25.54 percent compared to 30 percent enjoyed in 2013 and 28.6 percent in the full year to April 2013.

It is quite likely that with government slashing the fiscal deficit from $54 billion in 2013 fiscal year resulted in increased tightness in the economy. Much of the measures that led to the wiping out of the fiscal deficit would have been increased taxes and a sharp cut in interest cost. There is no new tax take for the 2014/15 fiscal year and the economy should be freer to function with some amount of growth. As such, the environment should start to look better in the latter part of this year for companies such as Blue Power.

Finances | The company’s finances are in a very healthy state with no borrowed funds and working capital increasing to $356 million from $302 million at the end of April 2013. Cash funds on hand amounts to $133 million. Amounts due to creditors is only $59 million. while receivables amounts to $77 million but inventories are at $203 million up from $177 in April 2013.

Stock outlook | At the time of writing, the stock was in strong demand by one broker at the $9 level. The weakness shown in the latest quarter sends cautionary signals which may be temporary. We see the current quarter continuing to reflect some of the weakness of the January quarter and we are forecasting earnings of $1.50 per share for the year ending April 2014 and $1.80 for the 2015. We leave the stock as a cautious Buy Rated around the $9-10 region based on the tendency for limited supply and strong current demand for it.

Related posts | Blue Power profits continue up  | Blue Power profit up 20%

Recent insider trades

Trading by insiders in their company stock on the Jamaica Stock Market can give insights to investors.

National Commercial Bank Jamaica advised that a related party purchased 1,590,083 of its shares on February 21, 2014.

National Commercial Bank Jamaica Limited advised that a connected party purchased 498,100 of its shares on February 14, 2014 and also advised that a related party purchased 46,986 of the shares on February 11, 2014.

National Commercial Bank Jamaica advised that a related party purchased a total of 20,089,111 of the bank’s shares on February 4, 2014. Shares totalling 18.25 million were traded on the Trinidad Stock Exchange and the rest on the Jamaica Stock Exchange.

Scotia Group advised that a senior manager sold 50,000 of the group’s shares on January 31, 2014.

Mayberry Investments (MIL) advised that a related party purchased 1,222,206 of the company’s shares on January 23, 2014.

KLE Group Limited has advised that a director sold 56,860 of the company’s shares on January 21, 2014.

The Gleaner Company advised that a senior manager sold 210,000 of the company’s shares on January 21, 2014.

Grace Kennedy has advised that as at January 2, 2014 a total of 1,440,062 of the company’s shares were purchased under the Share Buy Back Programme

Mayberry Investments (MIL) advised that a related party purchased 249,771 of the company’s shares during the period January 6 -10, 2014 and a related party sold 12,862 of the shares on January 9, 2014.

Mayberry Investments (MIL) reported a big inside trade on December 24, 2013 when a related party purchased 10,000,000 MIL shares from a related party who sold 10,168,266 of the company’s shares. The shares were traded between $2 and $2.02.

Desnoes & Geddes Limited (DG) reported that a director purchased 390,000 shares of  on December 24, 2013, the price the stock traded at was $5.

Scotia Group Jamaica Limited (SGJL) reported that a Senior Manager purchased 5,050 shares on December 20, 2013, the stock traded between $19-20.

Pan-Jamaican Investment Trust Limited reported that senior managers were issued a total of 45,740  shares under the Pan-Jam Long Term Incentive Plan on December 24, 2013.

National Commercial Bank (NCBJ) advised that a related party sold a total of 27,111,000 NCBJ shares on December 30, 2013. The stock traded at $17.50 and Scotia Investment was the selling broker with Mayberry Investments to buying broker. Additionally, two directors purchased a total of 15,553 of the company’s shares on December 19, 2013.

Consolidated Bakeries advised that a senior manager purchased a total of 170,300 of the company’s shares on December 20, 2013.

Grace Kennedy Limited advised that Non-Executive Directors acquired a total of 84,880 GK shares on December 13, 2013.

Scotia Group Jamaica Limited (SGJL) advised that a senior manager purchased 2,400 of the group’s shares on December 10, 2013.

Gleaner Company advised that a director purchased a total of 398,946 of the company’s shares during the period December 2 – 19, 2013.

Desnoes & Geddes Limited (DG) advised that a director purchased director purchased 500,000 of the company’s shares on November 19, 2013 and 32,224 during the period November 29, 2013 to December 2, 2013.

Consolidated Bakeries (PURITY) advised that a director purchased 223,000 shares during the period November 13 – 20, 2013.

Buy Rated: Ja Teas & JMMB big gains

Friday, 21st February 2014 |  This week on the Jamaica Stock Exchange, Jamaican Teas gained 19 percent and on the Trinidad Stock market, Jamaica Money Market Brokers (JMMB) 11 percent on the Trinidad market.

Meanwhile, Cable & Wireless, a new selection to the Buy Rated list gained 6% during the past week. General Accident also increased by 6 percent.

Lasco stock continue to be lacklustre with Lasco Distributors and Lasco Financial both shedding 7 percent and Lasco Manufacturing down 8 percent.

BuyRatedTable21FebUpdated reporting | The performance tracking of the Buy Rated Stock Chart shows details of stock gains since selection and now shows the performance for the week. Accordingly, there will no longer be weekly comments on changes as the chart shows the latest movements.

Related posts | D&G, Carreras & C&WJ now Buy Rated | Teas profit up 32 percent | JMMB Q2 profits jumps 56%

Little change to TTSE PE values

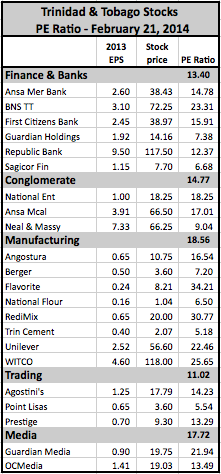
Friday, 21st February 2014 | Prices mostly edged down during the past week and five stocks perked up on Friday but the movements had little impact on the market valuation of the stocks.

TTSE_PETable21FebThe general tone on the Trinidad market is more in line with sidewards movement. However, the potential for investors still rests with stocks that can gain over 100% like Trinidad Cement at 325%, Point Lisa (261%), Berger (206%), Guardian Holdings (198%), National Flour (154%), and Neal & Massy (151%).

Related posts | D&G, Carreras & C&WJ now Buy Rated | Buy Rated: Ja Teas & JMMB big gains

Eppley profit jumps

Eppley is an interesting play with limited income and limited cost in the short term but profit could explode to the upside in 2014 as increased funds under management are put to work.

The company reported a big jump in profits of $34 million or $61.04 per share earnings (EPS) for 2013. In 2012, profit was just $15 million and EPS of $50.21. In the December 2013 quarter, EPS came out at $13.88 as profit amounted to $11 million as no tax was charged due to the exemption for Junior Market companies.

The full year earnings came from income of $65.3 million. Operating expenses were $34 million and interest expense $16.5 million. Eppley generated $24 million in Other Income. Net interest income for the full year was roughly the same as in 2012 at $48.7 million, 2012 $50 million. Income should grow in 2014 as the proceeds of the preference shares issued at the end of 2013 which brought in $387 million at 9.5 percent per annum starts to generate income.

eppleytype150x150At the end of 2012, there was $463 million total assets under management but that has grown to $814 million, almost doubling the amount. Except for a very small amount, the remainder of the assets are all potentially income generating. At the end of December, only about $160 million of the assets was not placed to maximize returns and that should be corrected in 2014.

Stock outlook | The company stated that it had a $757 million portfolio with an average yield of 15 percent at year end; $474 million of these funds are borrowed but at lower cost than the rate being generated by the portfolio. Earnings for 2014 should be in the region of $60 million or $107 per share after paying preference dividends. If this materializes, the stock could move strongly upwards if enough trading takes place. Eppley announced a $9 per share dividend payable on February 28, 2014. The stock, which trades infrequently, last traded at $380.

Related posts | Eppley preference shares over | Profit up 92% for Eppley | IPO: What or who is Eppley?

Carreras is back

Profits at Carreras is back on track dollar wise, as revenues hit $3.66 billion in the 2013 December quarter versus $3.745 billion in 2012.

Gross profit is above the 2012 period of $1.69 billion at $1.75 billion in 2013. Selling and administrative expenses declined in the latest quarter, which would have pushed the 2013 results above 2012. Carreras booked interest due on the debt owed by the tax department of $1.8 billion as other income, resulting in profits growing to $2.18 billion after tax, versus $1.17 billion in the prior year. Gross profit is down for the nine months to $3.98 billion from $4.34 billion in 2012. Profit after tax for the year-to-date is $3.1 billion versus $5.1 billion, with both periods having swollen figures due to exceptional income.

CarrerasTobaccoFree280x150Volumes are still down, but not as badly as in the June quarter, when sales were negatively affected by the hike in cigarette prices in March 2013 and the stock piling of inventories by the trade ahead of the price hike, a practise that goes back for several years. The December quarter’s performance is in stark contrast to the June quarter when revenues plummeted from $3.1 billion in June 2012 quarter to just $2.16 billion, a sharp 30 percent drop, but profit after tax fared even worse, dipping by 40 percent.

Expenses rise | Administrative, sales & marketing expenses fell in the latest quarter to $600 million from $710 million in 2012 but is marginally up to $1.655 billion for the nine months compared to $1.58 billion for the same period as of December 2012.

Tax Recovered | The tax now recoverable is down to $980 million from $1.733 billion at the end of March and is expected to be fully recovered over the next 12 months and will most likely be distributed as dividends to shareholders.

Carreras ended up with cash funds of $3.8 billion at the end of December, equity is at $4.7 billion or $9.60 per share.

Earnings appears to be back on track to deliver around $6 per share annualised, which would result in some increase in the quarterly dividend that was cut from $1.50 to $1 last year in light of the drop in profit. Carreras declared $1.62 as the latest dividend to be paid March after paying a special capital cash distribution of $1.18 on January 30, 2014.

Carreras is an IC Insider Buy Rated Stock.

Related posts | D&G, Carreras & C&WJ now Buy Rated | Carreras pays out liquidation money | Carreras takes a big hit but tax recovery starts | Carreras grew income

D&G, Carreras & C&WJ now Buy Rated

IC Insider has added Desnoes & Geddes, Carreras and Cable & Wireless Jamaica to the Buy Rated list.

Desnoes & Geddes reported gains of 21 percent for the six months to December, earnings excluding one-off items and is poised to earn 80 cents for the full year ending in 2014. Forecasted earnings for the 2015 year is $1.10.

For Carreras the worse seems to be over with the last set of interim figures showing sales starting to recover from the impact caused by the price increase and the stock piling of cigarettes in the 2012 December and March 2013 quarters. IC Insider’s forecast is for earnings of around $5 per share for the year to March 2014.

Cable & Wireless’ sharp increase in cellular revenues and cost cutting will change the bottom-line markedly going forward.

Berger Paints Jamaica has been added to the market watch list flowing from a revival in earnings for the March 2014 year.

Related posts | D&G elevated to Buy Rated! | Carreras is back | CWJ loss down with much progress | Berger keeps profit gains

BUY&WATCHFeb12th

Image courtesy of suphakit73/FreeDigitalPhotos.net

Caribbean Producers results pushes stock

Investors were evidently impressed with the results of Caribbean Producers Jamaica (CPJ) for the half year to December 2013 and pushed the stock price up to $3 on Thursday, February 13th, the first trading day after the release.

The company released second quarter results to December showing profits up by 202 percent to US$1.624 million for the six months and 65 percent for the December quarter to US$1.18 million from US$711,712 in 2012. Earnings per share for the six months amounted to US$0.148 cents.

Sales revenues rose by 24 percent for the December quarter and 22 percent year to December hitting US$37.5 million for the 6 months and US$20.46 for the quarter. Gross profit margins came out at 41 percent for the quarter and 42.4 percent year to December. In the prior year, the margins were 42 percent for the quarter and 39.8 percent for the six months period.

CaribbeanProducers(CPJ)280X150Expenses up | Selling and administrative expenses are up 16.4 percent in the December quarter and 18.2 percent for the six months, while finance cost rose by 19 percent in the latest quarter and 14.4 percent for the year to December. Depreciation charge also rose sharply due mainly to their expansion into meat and juice processing.

CPJ’s performance for the next quarter should push profits up quite sharply as historically the March quarter generates the highest amount of sales and profit during the peak winter tourist season. IC Insider has forecast earnings for the full year at 70 cents Jamaican and J$1.35 for 2015 fiscal year.

Finances | The company is still not comfortably funded with borrowed funds of US$25 million at an elevated level and in excess of equity of just US$14.7 million. Short term loans are at $11 million, well in excess of the annual cash flow of approximately US$9 million.

Caribbean Producers is an IC Insider Buy Rated stock.

Related posts | D&G, Carreras & C&WJ now Buy Rated | Caribbean Producers’ impressive profit | CPJ’s new St Lucia venture