 Cargo Handlers made profit of $31.6 million for the third quarter, ending June and $83 million for the nine months. The 2014 results are up 40 percent from $22.6 million and 31 percent over the $63.6 million earned last year, respectively.
Revenues excluding interest income, grew 32 percent for the Montego Bay based and junior listed company, over the June 2013 quarter, to hit $56 million, and reached $155 million for the nine months to June, an increase of 23.5 percent over the $126 million in the prior year. Some of the growth is driven by $3 million in management fees relating to management of the petroleum transport business, pending finalization of acquisition of the transport company. Movement in the value for the local dollar also played a role in the revenue growth, management confirmed with IC Insider.
Other operating expenses grew from $17.7 million to $22.6 million, an increase of 12.7 percent for the June quarter, and reached $65 million in the nine months, up by 17 percent. Administrative cost were flat for the quarter at $2 million and up from $6.4 million to $7.8 million for the year to date.
Earnings per share rose from 60 cents to 84 cents in the quarter and $2.22 for the nine months. Earnings for 2014 which ends in September, should be $3 per share. For the year to September 2013, the company earned $2.27 per share.
The company had earlier indicated that the acquisition of the transportation business should be concluded during February. At the time of reporting, this has not yet been concluded. From all indications, concerns regarding the transport company’s audited financial reports seem to be at the heart of the delay. Cargo Handlers had deposited $69 million against the purchase. Most of these funds seem have been used to acquire fixed assets which jumped by $48 million in June this year. Cash is down to $77 million and investments at $16 million at the end of June. The company remains debt free.
A dividend of 50 cents per share was just declared by the company and is payable in March 6 and another of $1.30 per stock unit will be paid on September 16. The dividend yield at the current stock price of $14.10 is 12.76 percent. The stocks is priced at a PE of just under 5 times 2014 earnings, but supply and liquidity are very low.
Cargo Handlers’ impressive June quarter
Scotia Investments reports down profits
 Scotia Investments Reports profit of $1.34 billion for the nine months to July and net profit for the quarter, of $504 million. For the year to July, profit is down $82 million or 6 percent from the same period last year, but up $89 million or 21 percent above the $415 million earned in the April quarter and down from $563 million in the 2013 quarter.
Earnings per share (EPS) for the period, is $3.17 compared to $3.36 for the same period last year, and should end up in the $4.40 range, by this October year end. Return on Average Equity (ROE) is 13.87 percent, down from 16.10 percent last year.
Operating Income, comprising net interest revenue and other income of $3.19 billion for the nine months, is down $48 million from the same period last year. Total operating income for the quarter was $1.13 billion, up $58 million or 5 percent recorded last quarter, Net income for the quarter of $580 million was flat quarter over quarter, but is down $113 million or 16.3 percent from the July 2013 quarter, due to a big jump in interest cost. Net interest income after impairment losses for the nine months period is $1.8 billion, down $288 million or 14 percent below the same period last year.
Non-Interest Income|Non-interest income, amounts to $1.4 billion for the period, up $240 million or 21 percent over the year to July 2013 and $549 million for the quarter, up $55 million or 11 percent compared with the last quarter; due primarily to gains on financial assets. The 2014 outturn represent an increase over the earnings of $486 million generated in 2013 July quarter. Non-interest income, includes fee income, securities trading gains and net foreign exchange trading income.
Total operating expenses for the period were $1.26 billion, up $50 million or 4 percent compared with the same period last year; $396 million for the quarter, down $47 million or 11 percent from last quarter due mainly with increased asset tax but the cost is up from the $366 million incurred in the 2013 quarter.
“Overall, our fund management business has grown 9 percent year over year; and our flagship money market fund, The Scotia Premium Money Market Fund has experienced a 105 percent increase year over year, with a net asset value of over $9 billion,” Lissant Mitchell, CEO of Scotia Investments said.
“Total assets of $73 billion remained flat year over year and quarter over quarter; consistent with our strategic initiative to focus on growth of our off-balance sheet portfolios. Assets under management including the company’s custody book were $135 billion as at the end of the period, up $21 billion or 18 percent above last year and $6 billion or 5 percent over last quarter. The growth was driven by the improved net asset values on managed funds.” The Investment Bankers reported to shareholders.
The company’s stock traded at $21.40 on Friday with a PE ratio of 4.75 that is low but presently reflects overall market conditions. There is not much supply on sales at current prices. The forward PE is lower than the above. The company’s performance is not electric presently but lower interest rates on government paper that has be falling since May and continue growth in their asset portfolio should have improve profits for 2015. As such the Buy Rated accolade remains.
Scotia Group’s profit down, future much brighter
 Scotia Group Jamaica made profit of $2.6 billion for the third quarter ending July, $337 million above the previous quarter ended April but $278 million below the quarter ended July 2013 and $7.4 billion for the nine months period, down from $8.2 billion last year.
The group increased bad loan provisions by $130 million to $497 million for the quarter over April this year and an Increase of $320 million over the July 2013 level. For the nine months to date provisions for loans is up $550 million to $1.376 billion.
Operating expenses have been under control with an increase of 7.3 percent for the quarter and 6.7 percent year to date but this is much higher than the 2.7 percent increase in income, net of interest cost for the quarter, and 1.4 percent increase for the nine months to July. “This is due primarily to higher staff related costs of $279 million and operating expenses of $579 million, reflecting an increase in the asset tax of $498 million, resulting from the recent increase in the rates,” management said in their report to investors.
The group would have enjoyed higher income from foreign exchange trading in 2013, as the value of the Jamaica dollar slipped more than it has done during the current period, leading to a $300 million decline for this line item. Importantly, while gross interest income was flat, at $15 billion up to April versus 2013, it has grown in the July quarter, due to the stronger loan growth.
Earnings per share (EPS) for the nine months is $2.36 compared to $2.64 for the same period last year and seems set to report $3.45 for the full year ending October and $4.50 for the next fiscal year.
The Return on Average Equity was 13.74 percent, down from 16.67 percent last year.
Scotia approved a third interim dividend of 40 cents per stock unit payable on October 16.
Total assets increased year over year by $12.5 billion or 3.2 percent to $401 billion, due primarily to growth in the loan portfolio of $13.6 billion. Loans grew by 10 percent since July 2013, to hit $144.6 billion. More importantly, while loans grew only by $2 billion up to April from October last year, it jumped $8 billion in the latest quarter, a 20 percent increase, annualised, putting it on track for a big surge in lending going forward if maintained, and strong growth in profits, as well. Deposit declined marginally to $197 billion at the same time. The stock remains Buy Rated.
CWJ making headway, not there yet
 Revenue from core business is up 11 percent while expenses are up by a much smaller 5 percent but Cable & Wireless still ended up with a loss of $712 million in the June quarter, this year, better than the $804 million reported for the 2013 quarter. The 2013 performance is boosted by other income representing, gain on sale of fixed assets of $130 million, putting operating income at $934 million than the reported figure. The company had a $580 million improvement in operating profit in 2014 excluding the gain on sale of fixed asset.
Cost rose by $250 million in the quarter as amortization cost, administrative, marketing and selling expenses and interest cost rose, offset by lower out payments for calls to other networks and labour cost. The company increased marketing spend during the quarter to drive sales of it MVP data and talk EZ plans, during the 2014 World Cup tournament. They were the leading sponsors of the CVM TV live broadcast of the games. The largest cost increase, is finance, rising 69 percent to $962 million, due mainly to a sharp rise in the interest rate charged by the parent company, based on higher Jamaican Treasury bill rates. Up to March this year the rate was 7.7 percent effective May 11th, it moved to 10.03 percent, the rate should decline by time the next reset date comes around November 11 this year as Treasury bill rates have been on the decline since May and should get even lower than currently, when the rate resets.
The company continues its focus on attracting new cell customers as well as internet data users, while trying to maintain landline business. The results show, in the strong growth seen in the June quarter, compared with June 2013. Mobile subscriber base increased by 37 percent with revenue up 34 percent, broadband base increased by 12 percent with revenue up 39 percent, in addition total revenue for the quarter is up on the inflows of $4.7 million for the March quarter.
The next two quarters, are periods when the company places emphasis on aggressively growing the customer base, as a result increased focus on marketing spend, can be expected to continue to increase revenue. While data suggest the possibility of profit this year based on continuing growth in revenues, a lot will be dependent on the aggressiveness of customer acquisition and by extension the cost to acquire them.
Cable & Wireless has a negative book value of $25 billion or $1.46 per stock unit, having written off large portion of its assets in recent years. The business as it now exists has a positive value, as such the net value per share could be far better than the book value indicates. The real value to shareholders must be its ability to convert losses to profit and soon. Investors in the market are sensing the improvement, driving the stock price up from 16 cents at the start of the year to 35 cents presently. Importantly, selling of the stock is down from what it has been in 2013 and in the early months of this year.
Of course the company has to depend on its parent company for financial support for capital in the short term but it is close to a positive cash flow from operations.
C2W Music reports 1st profit
 Start up C2W Music is reporting its first quarter of profits since it was listed on the junior market in 2012. The company that had chalked up losses in each quarter since listing, shows a profit of US$16.6000 for the June 2014 quarter, in its latest release of results.
The company booked copy right income of US$30,000 in the quarter and royalty of only US$189, but with administrative expenses of $12,193 and finance cost of US$1,396 the income was enough to leave a surplus for the quarter. This compares with a loss of US$157 million in the 2013 quarter. For the six months to date, losses are down to $66,000 versus $346,000 in 2013. Is this the light at the end of the tunnel? Management seems to think so as the quote to shareholders show below suggest.
“The Company negotiated an extremely strategic joint venture music publishing deal with one of our songwriters and an extremely successful music publisher, Rebellion Corps/Notting Hill Music. In this joint songwriters and an extremely successful music publisher, Rebellion Corps/Notting Hill Music. In this joint venture, they will help us in securing homes for more of our copyrights, which will result in increased revenue for the Company. The Company continues to work closely with the Caribbean Performing Rights Societies to recognize our rightful revenue, as their new royalty distribution systems are now in place. The Company continues to exploit our own catalogue and continues to have success in this area. We are also proud and happy to know that the Maxi Priest album is doing very well with two of our songs on the album, and the Etana album is heating up to be a success story also,” Ivan Berry the company’s CEO stated in commenting on the results.
At the end of the quarter, the company had equity of only US$34,000 having racked up net losses of US$1.25 million, loans of $75,000 and cash of only $2,000.
Medical Disposables revenue up 26%, profit 13%

Winston Boothe – Chairman Medical Disposables & Supplies
Profit after tax is up 55 percent as there was no tax charge in the June 2014 quarter, but tax ate up $4 million of the 2013 profit. “The main reason for the growth in revenue is the strategic focus on new and wider product offerings and greater market penetration”, Kurt Boothe, General Manager stated in his report to shareholders.
Gross profit grew 27 percent to $65.6 million from $51.66 million and gross margin moved to 36.24 percent in the quarter, from 33.78 percent in the 2013 June quarter but down from 42.15 percent in the March 2014 quarter. “This improvement was due to the product sales mix, increases in sales of products with higher margins and consistent review of our pricing structure to maintain the gross margin efficiency” Boothe stated. The audited accounts showed Gross profit margin of 35 percent for 2013-14 fiscal year.
Operating expenses climbed 49.7 percent in the June quarter over the 2013 quarter and “was driven mainly by staff related expenses, professional fees and special bank charges. Staff related expenses, in particular, were driven by the strategic decision to realign the staff complement and compensation to sustain the current growth, development and expansion of the business,” the general manager stated.
Earnings per share for the June quarter was 6 cents per share with the full year set to come in around 25 to 30 cents per share based on existing operations. At a stock price around $2 there is not much room for the price to make any major moves in the short term, unless the stock market becomes bullish.
Medical Disposables was listed on the junior market of the Jamaica Stock Exchange in December 2013, when it sold 63,157,895 Shares at $1.83 each and raised $113.7 million in its IPO.
Year over year current assets climbed from $370 million to $514 million due mainly to the IPO funds raised, while current liabilities stood almost static at $221 million. Shareholders’ equity jumped to $369 million from $163 million in March 2013 while borrowed funds are down from $147 million to $128 million, or just under two years’ cash flow.
Big jump in RJR Q1 profit (BUY RATED)
Radio Jamaica’s (RJR) profit for the first quarter to June jumped by 829 percent to $15.2 million up from only $1.6 million in 2013. The bottom-line improvement came from an increase of 7 percent in revenues for the June quarter, to $507 million.
Revenues from operation actually rose by 10 percent but a fall in other income from $35 million to $21 million, pulled the overall revenue gains down. Gross profit grew 27.6 percent to $272 million and gross margin hit 127 percent in the quarter, up from 94 percent in 2013. The improvement came primarily from new revenue streams outside of Jamaica in the Caribbean region, Management stated in their commentary on the results as well as shared sporting activities and some cost reduction in the cost of covering sports.
Operating expenses climbed 11 percent in the 2014 quarter over the 2013 quarter, to hit $268 million. The audited accounts showed gross profit margin of 35 percent for the last fiscal year to March. For the twelve months to March this year, RJR made profit after tax of just $59 million, having just breaking even on its main operation. In 2013, the group made a loss of $77 million before taxation and $30 million, after recording a tax credit of $47 million. The group would have benefited from increase sponsorship and advertising income emanating from the broadcast of the world cup football on radio as well as the staying of commentary on Television. As such some of the improvements in both revenue and profits may not repeat any time soon. What seems of import is that the worse seems behind them now and with prospects of an improving economy ahead, added revenues should flow mostly to the bottom-line as most cost are substantially fixed. The stock is now accorded a BUY RATED rating.
IC Insider is forecasting $131 million or 35 cents per share earnings in 2015. They should generate gross cash of $250 million for the full fiscal period which should a far way in reducing their indebtedness.
On the negative side cash is down from $155 million in March this year to $113 million and receivables is up to $456 million from $370 million and borrowings are stable at $246 million.
Trinidad Cement making strides but debt a bother
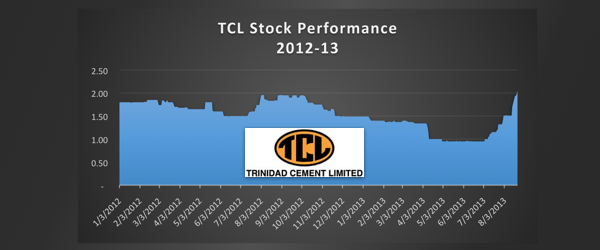 Trinidad Cement’s June quarter profit before tax bettered by a small amount the results of last year, coming in at $26.5 million versus $23.4 million, but after accounting for a non-recurring charge of nearly $26 million and lower finance cost.
Profit after tax due to shareholders of the company, amounted to $19 million for the quarter and in 2013 $46 million, helped by a tax credit of $33 million and for the year to June, the group reports profit after tax of $30 million versus $70 million in 2013. The non-recurring charge arose from a provision for retroactive pay increases and a charge of $16 million, mainly legal expenses incurred on the aborted debt refinancing exercise initiated earlier in the year. Had these charges not occurred, profit before tax would have been $52 million in the latest quarter. IC Insider is forecasting earnings of 45 cents per share for the full year.
“Key markets of Trinidad, Guyana, and Suriname remain buoyant whilst the others have stabilized and accordingly, the Group expects better second half results from operations, as the annual plant stops at the two largest plants have already taken place in the first half,” management, in its comments of the outlook stated.
Revenue in the quarter grew 9 percent to $512 million and for the 6 months from $994 million to $1.07 billion or 8 percent. Operating profit came out at $132 million in the June quarter, versus $114 million in 2013 and for the half year $232 million for 2014 versus $233 million in 2013. Finance cost slipped from $58 million in the June 2013 quarter, to $47 million, due to minimal devaluation in Jamaica compared to 2013. For the six months finance cost fell to $97.5 million from $123 million in 2013.
For the half year, Trinidad Cement generated cash flow of $144 million before loan repayment, up from $90 million last year. After loan repayment and the funding of investment activities, the group was left with $77 million of cash funds, up from $52 million at the end of June 2013. According to the 2013 audited accounts, the group was committed to repay $179 million during 2014 but that would still leave them with total loans of $1.77 billion and equity at the end of June of $573 million, therefore remaining in a highly over leverage position.
Investment in the stock is not without risk, with the heavy debt, in addition, the shareholders’ squabble to change directors, can create negatives for the group as well as it could be positive when everything is resolved. No one really knows how that will pan out. Based on the profit out turn and the likelihood for increased profits to come, IC Insider still accords the stock a BUY RATED status.
WITCO Q2 profit jumps 23.5%
 Trinidad’s West Indian Tobacco company profit jumped 23.5 percent in the June quarter, to hit $127 million as revenues climbed by a smaller 15 percent, to $324 million.
For the six months to June, profit is up to $224 million from $188 million, a 19 percent spurt, from revenues of $590 million versus $556 million in 2013. For the year to June, distribution, administrative and other cost were flat at $72 million, but corporate taxes was up to $73 million from $66 million. Earnings per share came in at $1.50 for the quarter and $2.65 for the half year. Earnings for the full year to December should reach $5.70 per share. The stock last traded for $118 in Trinidad putting the PE at 21. Witco will pay a dividend of $1.20 for the June quarter and $2.18 for the six months, an increase over the payments last year of $1.04 and $186 respectively.
West Indian Tobacco is listed on the Trinidad Stock Exchange and is a subsidiary of British American Tobacco, it is a fellow subsidiary of Carreras in Jamaica to whom it is the major supplier of cigarettes.
Witco has no borrowed debt but has shareholders’ equity of $284 million and cash funds of $191 million at the end of June. All currency are in T&T dollars.
Paramount’s Q4 profit jumps 108%
Paramount Trading’s profit after tax jumps 108 percent in the May quarter, on a pretax basis, it was up 73 percent while revenues came in at just 5 percent higher, for the quarter.
 Profit in the May quarter after tax is $43.6 million compared with $21 million for the similar 2013 period. The improved results for the company’s final fiscal quarter, came from revenues of $199 million versus $189.6 million in 2013. The final quarter numbers are a marked improvement over those for the February quarter, when only $14.6 million in profit was reported form sales of $181 million. For the full year, Revenues amounted to $720 million from $682 million in 2013. The 2013 numbers were boosted by one off income from the amalgamation of the trucking operation – Stamina Trucking and cancelation of related party debt amounting to $21 million, this also swelled the profit by a similar amount. In 2013 the Paramount incurred taxes on profit amounting to $10 million but in 2014 there was a tax credit of $425,000.
Noticeable, was a fall in administrative cost, from $35 million in the February quarter, to only $23 million in the final quarter. Gross profit margin climbed in the three months to May to 50 percent from 49 percent in the February quarter, compared to 47.7 percent for the full 12 months. The improvement in the profit margin is a welcoming development, especially as sales have not been growing at a fast pace.
Profit is projected to come in around $125 million in 2014/15 year or around 80 cents per share from current operations. At the current price of $2.70 the stock would be priced at a PE of only 3.4 making it a buy bearing in mind that that many junior listings have been valued around 8 times earnings.
Financials| The company earned an average rate of return of 29.7 percent, on the equity of $345 million at the end of May. Borrowed funds amounted to only $52 million compared to the level of equity. Cash stands at $56 million while receivables climbed to $172 million from $146 million, a much faster pace than the increase in sales. Inventory is at $203 million and increase form $172 million at May 2013, but payables moved up from $110 million to $128 million over the same period. Inventory levels may be on the high side as a protection against the devaluation of the Jamaican dollar, the same would not be true for the increased receivables.